


- Progressive's earlier lead in telematics driven pricing power has narrowed as rival insurers adopt similar tools, while the insurer now faces slower earnings growth compared with its prior pace.
- The core question now is how Progressive manages a world where its once distinctive data edge becomes more common, yet operational execution still has to handle claims costs and competitive pricing pressure at the same time.
- We will now explore how Progressive's investment narrative could be reshaped by concerns that its telematics pricing moat is narrowing.
Compare Progressive's fading telematics edge with peers that may still have stronger pricing or underwriting levers working in their favor by scanning our curated list of 31 resilient stocks with low risk scores.
Progressive Investment Narrative Recap
To own Progressive, you need to believe its edge in pricing and execution still matters even as telematics tools look more similar across the industry. The short term swing factor remains how well management balances competitive premiums with claims severity after the recent move in the consolidated combined ratio from 86.2 to 87.3. That shift, alongside slower earnings growth, puts more weight on day to day underwriting discipline.
The key risk right now is that a more aggressive and deflationary auto pricing environment, combined with higher bodily injury and physical damage costs, keeps squeezing net margins. If claims trends stay tough while rivals reprice quickly, Progressive could see profitability and earnings pressured further, even if policy volumes hold up.
Recent financial data gives helpful context to this telematics story. Progressive reported net income of US$11.7b on revenue of US$91.0b, with net profit margins of 12.8% compared with 12.7% a year earlier. June 2026 net income of US$779m was 31% lower, tying the current debate on the stock directly to underwriting outcomes and claims management rather than just technology branding.
Analysts now expect earnings to decline by an average of 6.9% per year over the next 3 years, even though revenue is forecast to grow 3.3% annually. That mix underscores why the narrowing data moat matters. With earnings pressure already in the numbers and a more competitive market, execution on pricing, loss ratios and expense control looks central to any future re rating of Progressive.
What The Current Forecasts Assume For Progressive
Progressive's narrative projects US$99.0b revenue and US$9.5b earnings by 2029. That profile lines up with analysts building in 2.9% yearly revenue growth and an earnings decline of US$2.2b from US$11.7b today to the US$9.5b consensus figure.
Uncover why Progressive's fair value signals a 9% potential upside to its current price that may not last much longer.
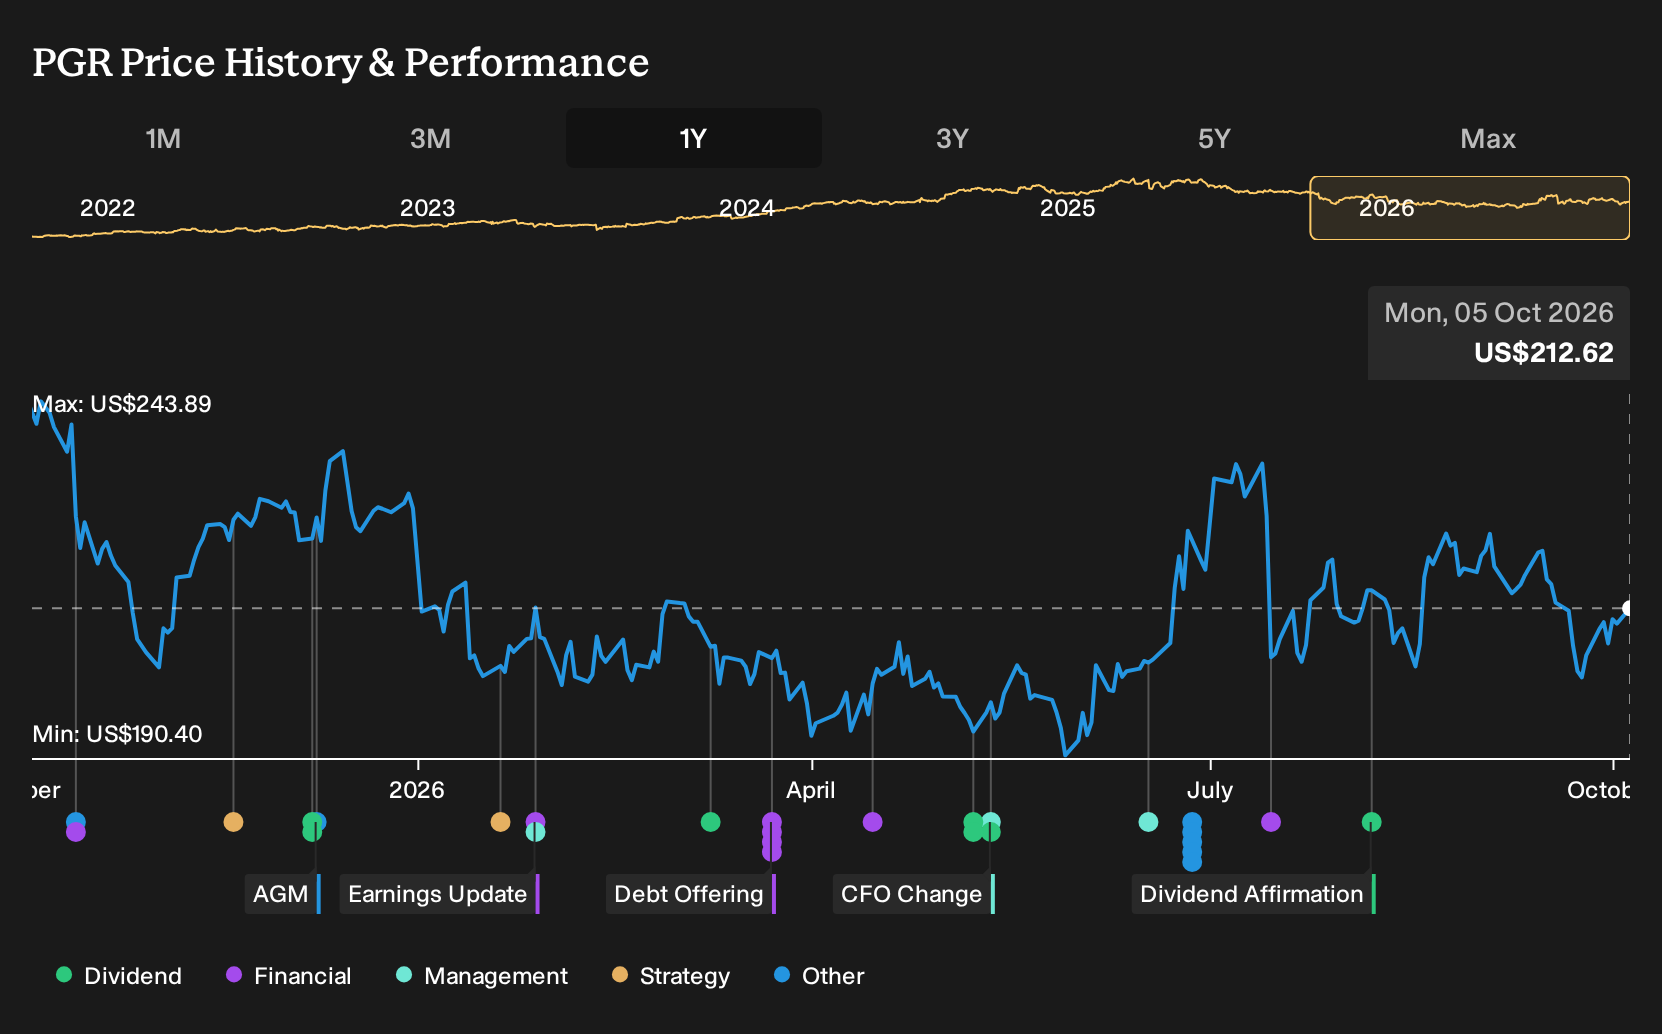
Exploring Other Perspectives
You are seeing one optimistic twist on Progressive. The most bullish analysts focus less on telematics risk and more on bundling potential, pointing to earlier forecasts of US$106.0b revenue and US$9.4b earnings by 2029. These views were set before this news, so you should expect opinions and narratives to evolve from here.
Explore 3 other Progressive fair value estimates, including one that suggests as much as 115% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Progressive research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Progressive. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Progressive's overall financial health at a glance.
Looking For More Investment Ideas Beyond Progressive?
Once you have a clear view on Progressive, it often helps to compare that thesis with other companies that have very different risk and return profiles. The Simply Wall St Screener can point you toward stocks that better match your own tolerance for volatility, income needs, and balance sheet comfort.
- If you want potentially steadier rides and fewer unpleasant surprises, start with 31 resilient stocks with low risk scores that currently screen well on resilience and lower risk scores.
- For investors who care most about strong finances and room to reinvest, there is a focused 19 high quality undiscovered gems that might not be widely followed yet.
- If reliable cash flows and income matter more to you than rapid price swings, give yourself a head start with a curated 7 dividend fortresses that already clear a 5%+ yield hurdle.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com