


BorgWarner (BWA) has been drawing fresh attention after recent price moves, with the stock down about 11% over the past month and roughly 6% over the past 3 months. Investors are reassessing what current levels imply.
Set against a stronger backdrop over the year, with the year to date share price return up 29.2% and the 1 year total shareholder return at 37.32%, the recent pullback suggests that momentum in BorgWarner is fading near the current US$60.26 level as investors reassess both growth prospects and perceived risks.
Compare BorgWarner's recent pullback with other potential opportunities by scanning a curated 27 high quality undervalued stocks that pairs solid fundamentals with currently discounted prices.
BorgWarner’s recent slide after a strong 1 year run leaves a clear fork in the road. Is this a reasonable entry now, or does patience for a deeper reset make more sense once the valuation work is done next?
Most Popular Narrative: 24.6% Undervalued
BorgWarner’s most followed narrative pegs fair value at $79.93, which sits well above the recent $60.26 close and presents the current pullback as a valuation gap rather than just a sentiment swing.
Expansion into data center power through the turbine generator program, supported by a 2 GW plant in North Carolina and expected revenue of about $300 million in 2027 at mid teens incremental margins, adds a new earnings stream that is not fully tied to light vehicle cycles and could support operating margin and EPS resilience.
See why 23 investors see BorgWarner as 25% undervalued.
Result: Fair Value of $79.93 (UNDERVALUED)
Still, the BorgWarner story can weaken if demand for combustion product lines fades faster than expected or if the battery segment continues to drag on overall results.
Find out about the key risks to this BorgWarner narrative.
Another View: BorgWarner Looks Expensive On Earnings
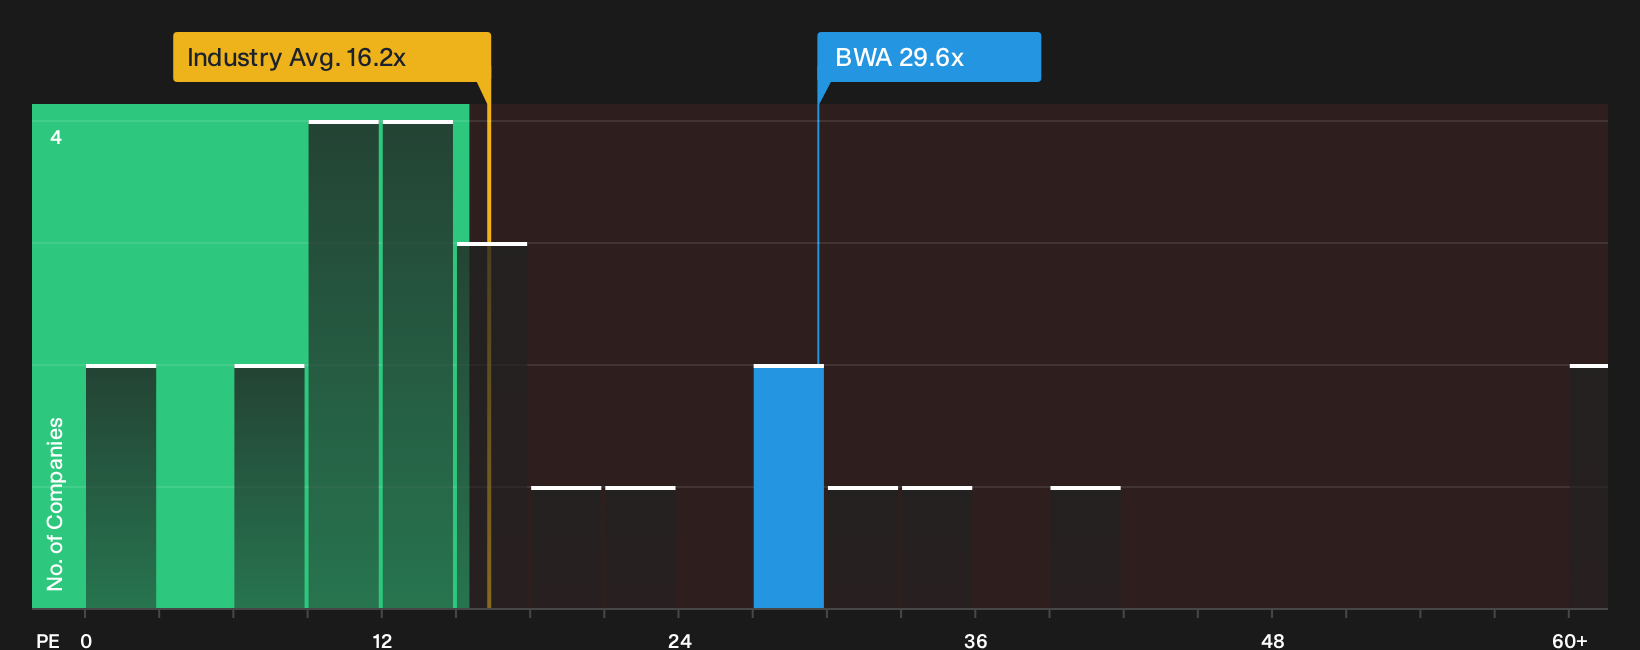
On the flip side of the story, BorgWarner screens as expensive on a simple earnings yardstick. The stock trades on a P/E of 29.6x, while the US Auto Components industry sits at 16.2x and close peers at 14.2x, compared with a fair ratio estimate of 17.6x.
That gap suggests investors are already paying a rich price for every dollar of current earnings, even though revenue is forecast to grow 4.6% a year and profits 15.9% a year. The question for you is whether the narrative and future cash flows justify that higher bar.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on BorgWarner so far. If the split between risks and rewards has you on the fence, review the details yourself and pressure test every assumption with the 4 key rewards and 2 important warning signs
Hunting Beyond BorgWarner For Fresh Ideas?
Do not stop with BorgWarner. Use this pullback as a trigger to refresh your watchlist with new angles and potential opportunities using targeted screeners.
- Target steadier potential outcomes by reviewing a 31 resilient stocks with low risk scores that focuses on resilience when markets turn choppy.
- Spot future leaders early by scanning a 19 high quality undiscovered gems built around quality fundamentals that the crowd may be missing.
- Strengthen your core holdings by running through a list of solid balance sheet and fundamentals (25 results) that highlights financial durability before sentiment shifts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com