


Marriott International (MAR) just refreshed its main credit lifeline by signing a Seventh Amended and Restated Credit Agreement that lifts total commitments, extends the maturity to 2031, and adjusts pricing and potential environmental incentives.
Recent trading reflects that mix of flexibility and scrutiny. Marriott International’s share price has eased over the past week but still shows a 30 day share price return of 5.76% and a year to date share price return of 13.55%. The 1 year total shareholder return of 34.18% and 5 year total shareholder return of 135.77% point to longer term momentum, which this expanded credit facility could either reinforce if investors see growth potential or temper if they view the higher commitments as adding financial risk.
Scan how Marriott International’s new credit firepower compares with peers by weighing it against 31 resilient stocks with low risk scores, which is built to spotlight balance sheets that aim to keep funding risk contained.
The credit move arrives just as Marriott International’s rally cools at the edges. Are investors reacting to fundamentals being repriced or sentiment catching its breath, and how does that show up in the current valuation?
Most Popular Narrative: 6.5% Undervalued
Against a last close of $355.89, the most followed narrative on Marriott International anchors fair value at $380.80, so the fresh credit agreement now gets weighed against an already constructive long term earnings story.
The rapid growth and deepening engagement of the Marriott Bonvoy loyalty program, now supported by new long term U.S. co branded agreements with JPMorgan Chase and American Express and an expected high 30% rise in 2026 global co branded fees, points to a larger stream of high margin fee income that can support net margin and earnings growth.
Ongoing investments in next generation technology, including a new central reservation system, property management platform and the AI powered Ask Bonvoy search tool that is already showing higher conversion and is expected to support ancillary booking and merchandising, can lift revenue per guest and improve operating efficiency.
See why 31 investors see Marriott International as 7% undervalued.
Result: Fair Value of $380.80 (UNDERVALUED)
Still, the narrative around Marriott International can be knocked off course if Middle East RevPAR remains weak or if richer loyalty economics squeeze margins more than fee growth offsets.
Find out about the key risks to this Marriott International narrative.
Another View on Marriott International’s Valuation
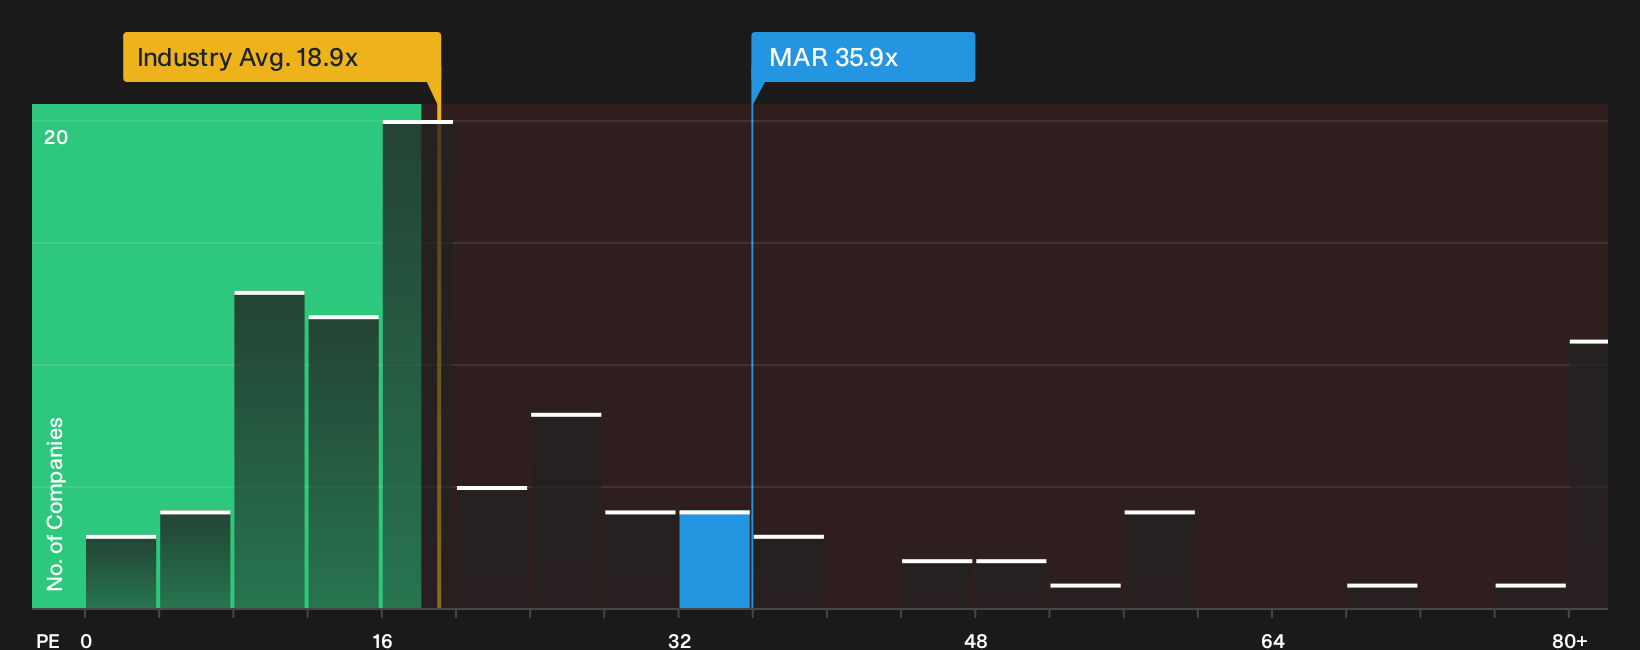
The crowd narrative paints Marriott International as 6.5% undervalued, but the market’s own yardstick tells a different story. The shares trade on a P/E of 35.9x versus 18.9x for the US Hospitality group and a fair ratio of 27x, which points to a rich valuation and less margin for error if growth expectations soften.
For anyone weighing that premium, the question is whether Marriott International’s fee based model and pipeline justify paying so far above both peers and the fair ratio, or whether this is where enthusiasm has already run ahead of the numbers.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Marriott International’s valuation and trading can either nudge you toward caution or curiosity, so move quickly and stress test the story yourself by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Marriott International?
If Marriott International has you thinking harder about price, quality, and risk, do not stop here. Broaden your watchlist so you are not relying on one story.
- Target sturdier portfolios by scanning a list of solid balance sheet and fundamentals (25 results) that focuses on companies aiming to keep leverage and refinancing risk under tighter control.
- Hunt for potential mispricing with the 19 high quality undiscovered gems that highlights lesser known businesses with fundamentals that may not yet be fully reflected in their share prices.
- Lean into resilience by checking the 31 resilient stocks with low risk scores that filters for stocks where quantified risk scores stay on the more conservative side.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com