


- H. Lundbeck is sharing new clinical data in movement disorders and migraine, including Phase III work on amlenetug in multiple system atrophy, Phase Ib data on Lu AF28996 in advanced Parkinson’s disease, and positive Phase IV results for eptinezumab in patients with prior inadequate response to CGRP therapies.
- The focus on high unmet need segments such as multiple system atrophy, advanced Parkinson’s disease and treatment resistant migraine gives Lundbeck more shots on goal across complex neurology, while also aiming to deepen utilization of its existing migraine franchise.
- We will look at how Lundbeck's investment narrative is shaped by added late stage neuroscience data, particularly the new THRIVE migraine results.
H. Lundbeck Investment Narrative Recap
To own H. Lundbeck, you need to be comfortable with a focused brain health specialist that leans heavily on a few key products while pouring cash into late stage neuroscience. The big belief is that a concentrated central nervous system pipeline can offset pressure from forecast revenue and earnings declines over the next three years and ongoing generic erosion.
Right now, the important near term swing factor is how quickly Lundbeck can keep expanding its migraine and psychiatry portfolio without letting higher R&D and one time capital costs squeeze profitability. The Seoul data drop and THRIVE readout do not change that core tension, but they add credibility around the high spend on neurology.
The THRIVE trial is the clearest operational link between the conference news and Lundbeck's nearer catalysts. Eptinezumab was tested in adults who had an inadequate response to a previous CGRP preventive, with 60% of participants remaining in the study reporting they were much or very much improved at 24 weeks and no new safety signals reported.
For an investor, this matters because Vyepti and the broader eptinezumab franchise sit at the center of Lundbeck's attempt to offset expected top line and earnings declines. Evidence in a difficult to treat migraine group can support deeper use of an existing asset, which is important while the firm waits on longer dated readouts from amlenetug and Lu AF28996.
H. Lundbeck's current analyst narrative assumes revenues of DKK 24.2 billion and earnings of DKK 3.9 billion by 2029, implying a 2.3% yearly decline in sales and flat profits compared with earnings today of DKK 3.9 billion.
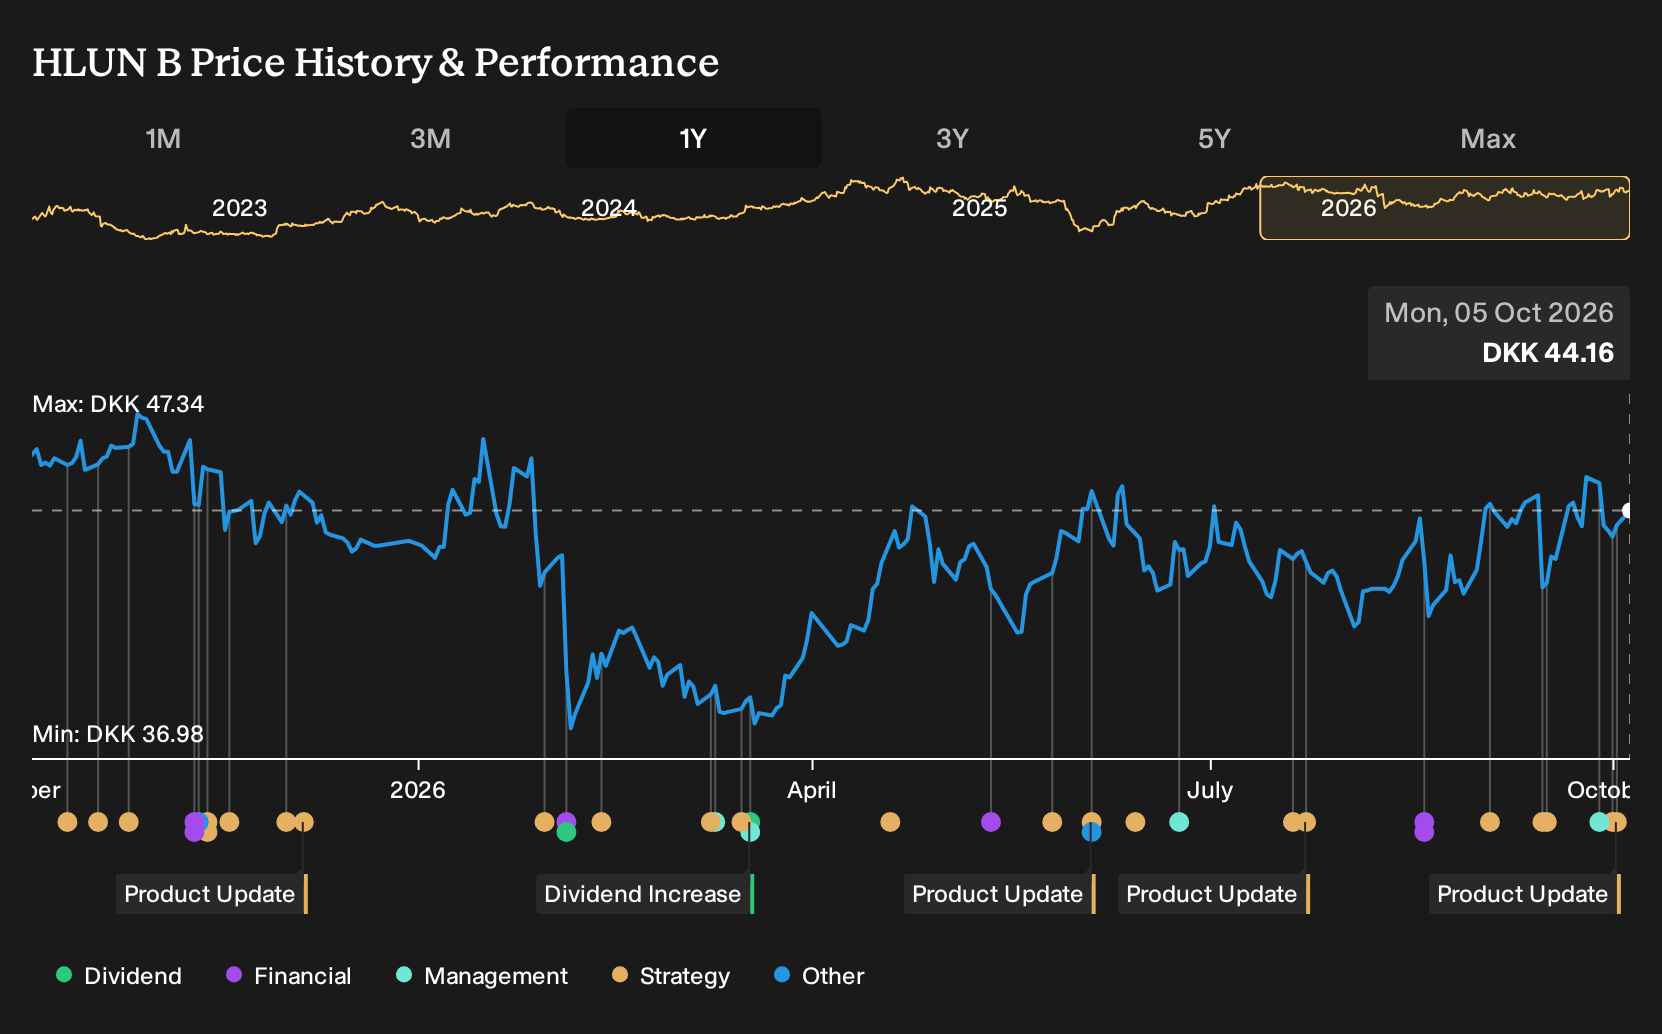
Uncover why H. Lundbeck's fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value opinions inside the Simply Wall St Community already span a wide range, from about 48.73 to 101.67 across 4 different retail investor models, so you are looking at genuinely split views on H. Lundbeck. When you set that against patent risk, heavier R&D spend and fresh migraine and movement disorder data, it becomes even more important to study multiple perspectives before deciding how this story fits into your portfolio.
Explore 3 other H. Lundbeck fair value estimates, including one that suggests it could be worth just DKK 48.73.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your H. Lundbeck research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for H. Lundbeck. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate H. Lundbeck's overall financial health at a glance.
Looking For More Investment Ideas Beyond H. Lundbeck?
If the H. Lundbeck story has you thinking about what else might fit your watchlist, it can help to cast a wider net and compare this neuroscience specialist with companies in very different positions on quality, valuation and income strength.
- For investors who want potential mispricings with stronger fundamentals, check out a carefully curated 615 high quality undiscovered gems that may not yet be widely followed by the market.
- If capital preservation and balance sheet strength sit high on your checklist, consider scanning a focused 226 resilient stocks with low risk scores to see which businesses score well on resilience and financial robustness.
- Income focused investors who prefer cash in hand can review a targeted 161 dividend fortresses that screens for higher yielding payers with an eye on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com