


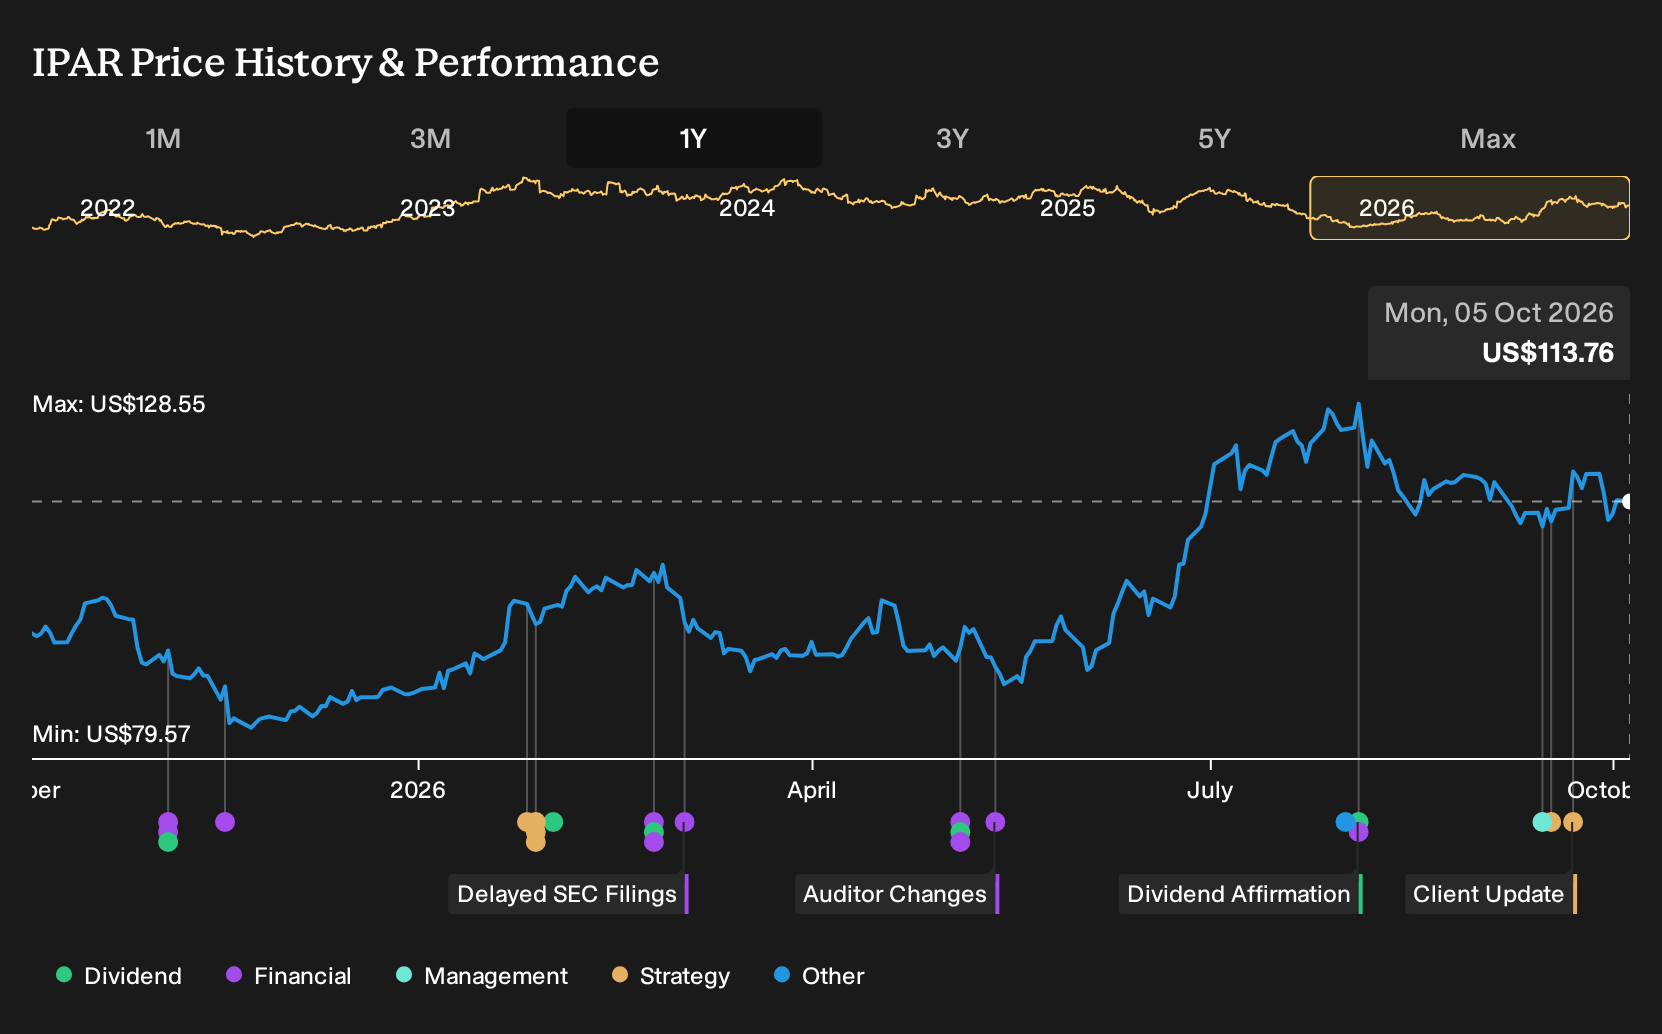
- In September 2026, Interparfums, Inc. reported an exclusive worldwide license agreement with PUMA to create, produce, and distribute PUMA branded fragrances through December 31, 2037, with a first signature lifestyle scent planned for 2027.
- The long dated PUMA deal deepens Interparfums' roster of sports and lifestyle partners. It adds another global label that can be woven into upcoming launch cycles and multichannel marketing plans.
- We will look at how Interparfums' investment narrative evolves as a long term PUMA fragrance license reshapes its portfolio breadth.
Scan how Interparfums' PUMA move compares with other brand driven consumer plays by reviewing our hand picked 19 high quality undiscovered gems in the sector.
Interparfums Investment Narrative Recap
To own Interparfums, you need to be comfortable with a fragrance group that lives and dies by licensed brands and product cycles. The key near term swing factor is how effectively 2026 line extensions and higher advertising spend translate into demand, while the PUMA deal mainly reinforces the 2027 and 2028 launch pipeline rather than shifting the next few quarters.
The biggest risk right now is execution on margins and spending. SG&A rose enough to bring operating margin down to 17.9% in the first half of 2026, even with higher gross margin, so further increases in advertising, royalties and logistics that do not feed through to sales could keep profitability tight.
The PUMA announcement sits alongside another long dated fragrance license, Roberto Cavalli through 2046, which together broaden Interparfums' portfolio beyond existing pillars such as Montblanc, Jimmy Choo and Lacoste. Longer contracts matter because they give the group more time to amortize launch spending and refine positioning across regions and channels.
In terms of potential catalysts, this wider roster interacts directly with the planned 2027 blockbuster cycle and the growing focus on e commerce and digital marketing on platforms such as Amazon and TikTok. As Interparfums adds more brands into that framework, it has more flexibility to shift investment toward concepts and geographies that are performing better if individual licenses underperform or regions under war related pressure remain weak.
Interparfums' narrative uses analyst assumptions that revenue grows at 5.7% per year and that by 2029 the group reaches about US$1.8b of sales and US$184.4m of earnings, compared with US$167.8m of earnings today. This implies an earnings increase of about US$16.6m over that period.
Uncover why Interparfums' fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts already framed Interparfums as a scale story, expecting revenue to reach about US$1.9b and earnings of roughly US$207.1m by 2029. You now have a fresh PUMA license on the table that those forecasts did not factor in, so opinions may spread even further. Use that gap to compare several viewpoints before you decide what feels realistic.
Explore 5 other Interparfums fair value estimates, including one that suggests as much as 105% potential increase from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Interparfums research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Interparfums. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Interparfums' overall financial health at a glance.
Looking For More Interparfums-Like Investment Ideas?
If the Interparfums story has you thinking about what else might fit your style, it can help to line it up against other opportunities with clear financial filters. Use the Simply Wall St Screener to widen your watchlist while still keeping your criteria tight.
- For investors who care most about valuation support, scan companies trading on attractive fundamentals using our 27 high quality undervalued stocks.
- If capital preservation sits high on your list, focus on businesses that score well on stability and risk using this 31 resilient stocks with low risk scores.
- To back firms with stronger balance sheets, compare Interparfums with a list of solid balance sheet and fundamentals (25 results) that can better handle shocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com