


A record US$60b AI chip financing package has pulled AI infrastructure out of the abstract and into hard numbers that investors can track. Capital is being committed, contracts are being written and long-term customers like Anthropic are locking in suppliers such as Broadcom and Google. This article unpacks what that could mean and reveals 3 stocks exposed to this news that may deserve a closer look or a wider berth.
The three stocks covered next are only a sample, and the full screen surfaced another 50 companies with equally compelling AI infrastructure stories that are not included here.
To go straight to the source and actively identify, compare and analyze your highest conviction semiconductor and cloud opportunities, head into the AI Infrastructure Enablers (Semiconductors & Cloud Platforms) screener
Macronix International (TWSE:2337)
Macronix International designs and manufactures memory integrated circuits used in everything from consumer gadgets to AI servers and data centers, with all NT$45.5b of revenue coming from Memory Products and Wafer Fabrication, and the group carries a market value of about NT$240.5b.
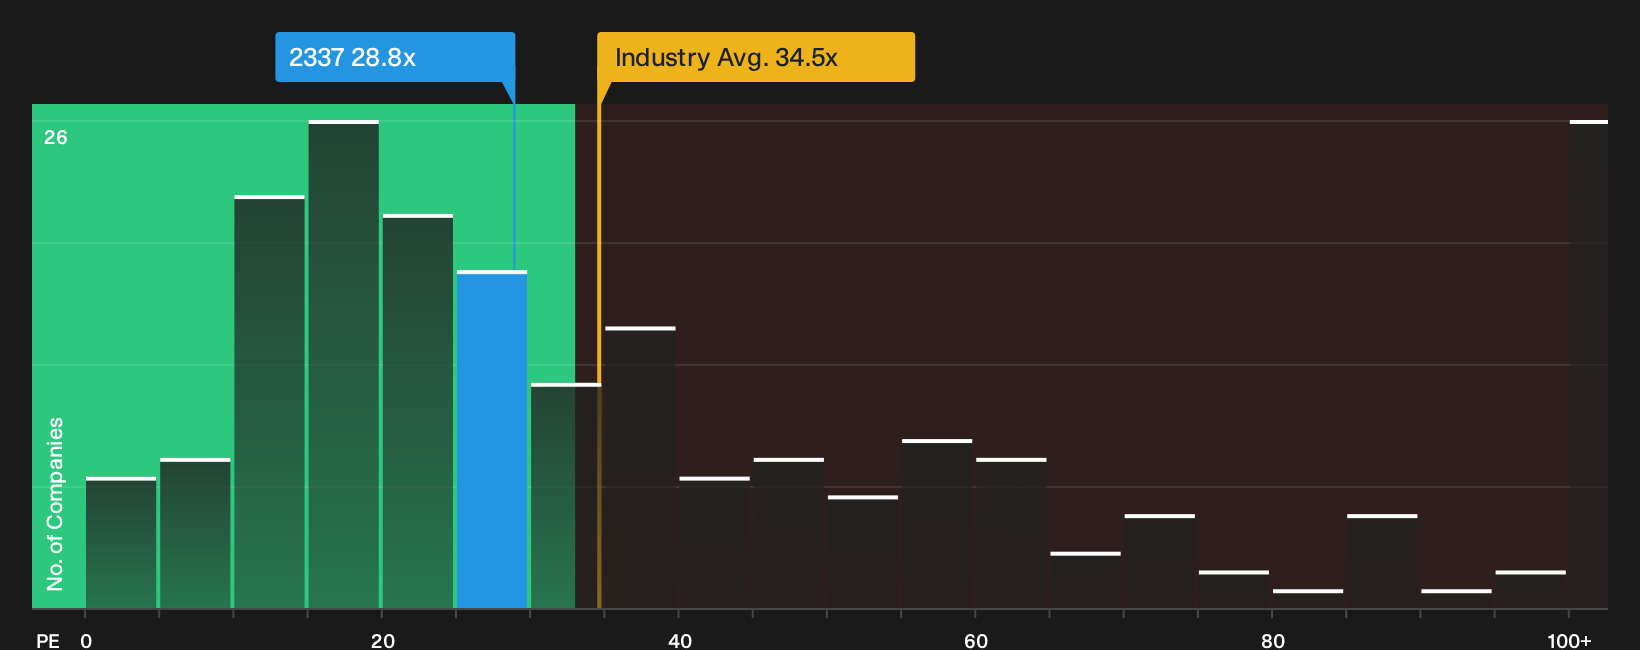
Macronix International provides exposure to the memory side of AI infrastructure, where chips feed GPUs and accelerators with data. The stock combines exposure to AI related capital expenditure cycles with a P/E below the wider semiconductor group, although the benefit to future earnings still depends on how one unseen pressure influences pricing power.
That pressure point deserves a closer look through the 4 key rewards and 1 important major warning sign to see how pricing power and AI exposure might really interact.
Anji Microelectronics Technology (Shanghai) (SHSE:688019)
Anji Microelectronics Technology (Shanghai) supplies semiconductor materials such as chemical mechanical polishing slurries and wet electronic chemicals used in advanced chip fabrication for AI accelerators and data center hardware, generating about CN¥2.9b from Specialty Chemicals, and carries a market value near CN¥48b.
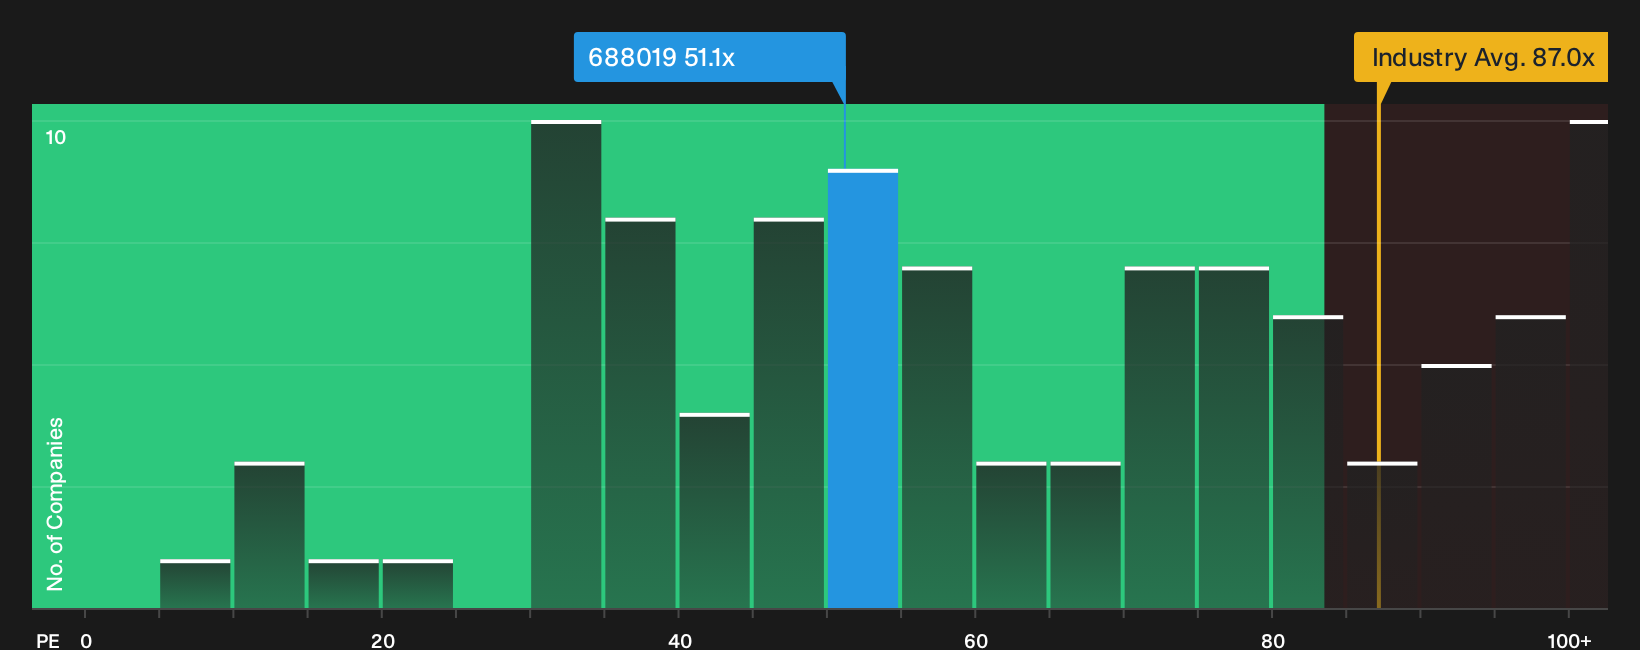
Anji Microelectronics Technology (Shanghai) provides focused exposure to the consumables that keep AI-focused chip fabs running, with Specialty Chemicals tied directly to advanced process steps that underpin GPUs and accelerators. The combination of earnings growth, strong margins and a lower P/E than many semiconductor peers may be appealing to some investors, depending on how one unseen pressure shapes future demand and pricing power.
That pressure could be the swing factor, so review the 4 key rewards and 2 important warning signs (1 is major!) to see where Anji Microelectronics Technology (Shanghai) might be decoupling from peers.
Phison Electronics (TPEX:8299)
Phison Electronics ties directly into the AI Infrastructure Enablers theme because its flash memory controllers and SSD systems help AI servers and data centers store and feed the data that keeps high performance GPUs busy.
Phison Electronics generates about NT$149.8b from flash memory control chip design and related storage solutions that serve AI data centers and other end markets, and the business carries a market value near NT$464.4b.
Successful innovation and commercialization of next-gen PCIe Gen5/Gen6 SSD controllers and proprietary solutions (such as aiDAPTIV+) are positioning Phison as a technology provider focused on higher-value opportunities in AI-driven and high-performance storage applications, with an emphasis on ASP growth and margin improvement over the medium term.
A key test will come if a single unforeseen pressure forces customers to revisit how much they are willing to pay for this storage plumbing.
If that pricing pressure is the real hinge, read the full narrative for Phison Electronics to see how Phison Electronics could turn it into accelerating leverage on AI storage demand.

Curious About What You Might Be Missing?
Fresh ideas can move before the crowd spots them, and strong themes often gather momentum fast. Scan curated opportunities while it matters and get in early.
- Chase resilient compounding potential by reviewing a curated 226 resilient stocks with low risk scores that aim to cushion portfolio swings while still targeting steady upside.
- Hunt for income that works harder than cash by screening a focused group of 161 dividend fortresses built around consistency and balance sheet strength.
- Ride potential upside in digital infrastructure by scanning hand picked 18 cryptocurrency and blockchain stocks positioned around blockchain adoption across payments, platforms and financial rails.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com