The Zhitong Finance App learned that Guoxin Securities released a research report saying that the A-share market and sentiment continued to be sluggish in the third quarter. Investors still have questions about the current stage of the market. Does the bull market still exist? The bank believes that this round of the A-share bull market is in its final stage, and there is still room for market interpretation in the future. Looking ahead to the fourth quarter, the A-share market is expected to usher in a recovery window due to multiple positive factors at home and abroad, and the end of the market can be expected. Structurally, technological growth, which has a comparative advantage in fundamentals, is still the main line of the stock market. As the bull market enters the middle to late stages, the industry structure is also expected to gradually spread. Attention can also be paid to AI applications in technology, resource dividends, and real estate consumption.
Guoxin Securities's main views are as follows:
1. Market Positioning: The bull market is in its third phase
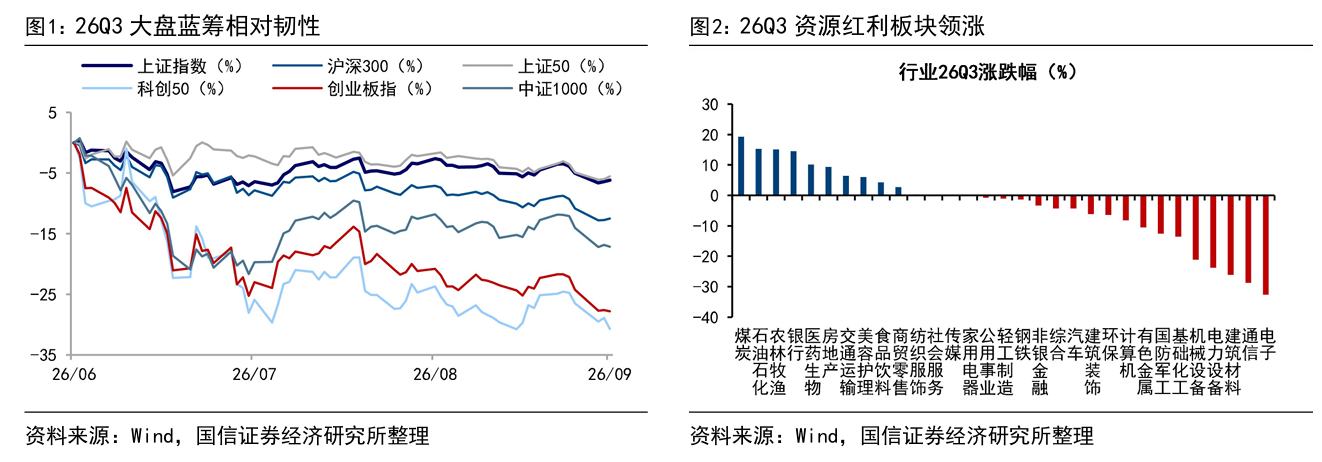
A-share market review for the third quarter: Market shocks and adjustments, industry and style rebalanced. Looking back at the third quarter, the science and innovation sector, which had strong performance in the previous period, was clearly adjusted. The Science Innovation 50 and GEM indices fell by 30.7% and 27.8% respectively (as of 9/30, the cumulative rise and fall rate for the third quarter, same below), weaker than the China Securities 1000 (-17.2%), Shanghai and Shenzhen 300 (-12.5%), the Shanghai Composite Index (-6.2%), and the Shanghai Stock Exchange 50 (-5.6%).
Looking at the stages, the Science and Innovation 50 and GEM indices fell 25.9% and 23.0% respectively in July; the market recovered in August, with the China Stock Exchange 1000 rising 9.8%, the Shanghai Stock Index rising 4.0%, the Science Innovation 50 and GEM Index rising 3.0% and 2.8% respectively; in September, the market declined again, with the Science Innovation 50 and GEM Index falling 9.2% and 8.8% respectively. Overall, big-market blue chips have been relatively resistant to decline in this round of A-share adjustments, while the tech sector, which performed well in the first half of the year, has clearly retreated as a whole.
Structurally, the industry's leading upward direction is shifting from AI hardware to the resource dividend sector. Coal (19.3%), petroleum and petrochemicals (15.3%), agriculture, forestry, animal husbandry and fishing (15.1%), and banks (14.6%) led the way in the third quarter, while electronics (-32.6%), communications (-28.7%), construction materials (-26.1%), and power equipment (-23.7%) had the highest declines.
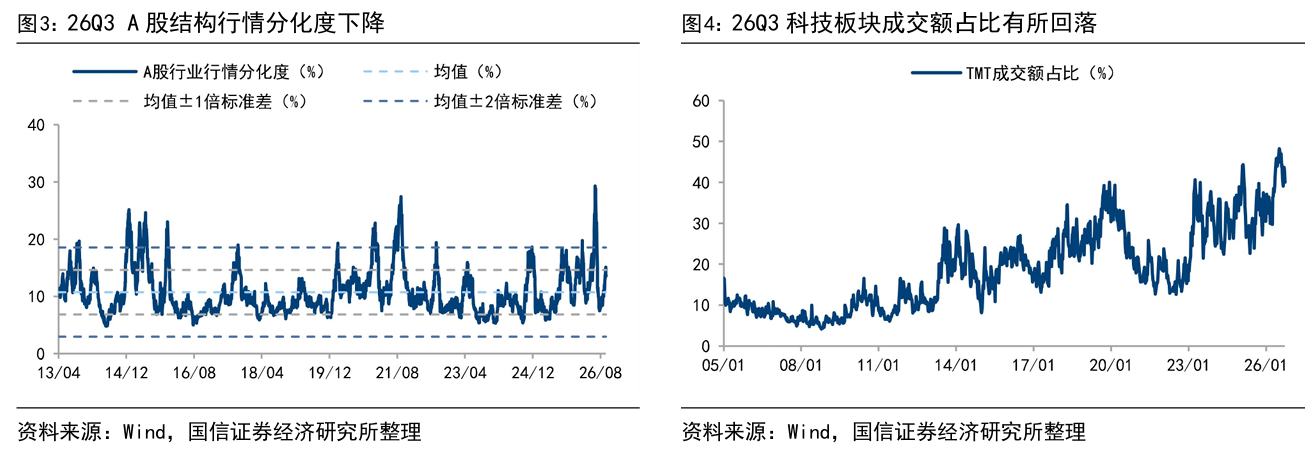
Looking at the degree of industry differentiation, as measured by the standard deviation of the yield of Shenwan's second-tier industry, the differentiation in the A-share industry fell from 28.8% at the end of June to 7.5% in early August, and rebounded to 13.6% at the end of September. It is still below the historical average plus one times the standard deviation, which is a clear convergence from the end of the second quarter. Meanwhile, TMT's share of turnover fell from 48.2% on July 10 to 40.1% at the end of September, indicating that the concentration of transactions in popular technology sectors declined from a high level in the early stages.
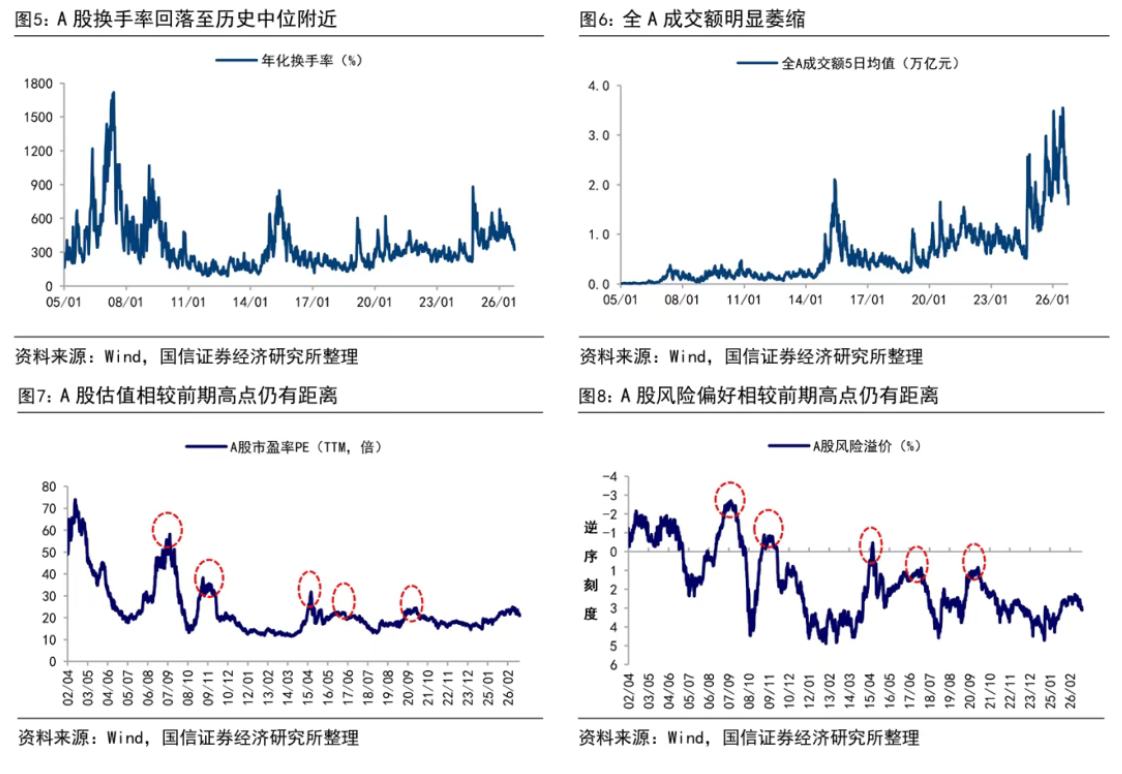
Market position and sentiment: The popularity of transactions has declined, and the valuation cost performance ratio is still in the middle of history. Trading sentiment has cooled down from the previous high. As of September 30, the annual turnover rate for the full A week was about 321%, down from about 373% in the previous week, and is about 59% since 2005. Judging from the daily frequency of transactions, the current 5-day rolling average of all A's turnover is about 1.6 trillion yuan, down about half from the previous June high of 3.4 trillion yuan, hitting a new low in nearly a year. The A-share turnover rate and turnover have declined markedly, indicating that the popularity of trading has subsided.
From the perspective of valuation cost performance, as of September 30, the total A-share PE (TTM) was about 21 times, equivalent to 21 times the historical average since 2005, and ranked from low to high about 66% in history since 2005; the risk premium was about 3.08%, higher than the historical average of 2.04% since 2005, which is about 30% of the historical average since 2005. Overall, the valuation and risk appetite of A-shares have risen markedly since their 24-year low, but compared to history, they are still only near the central position.
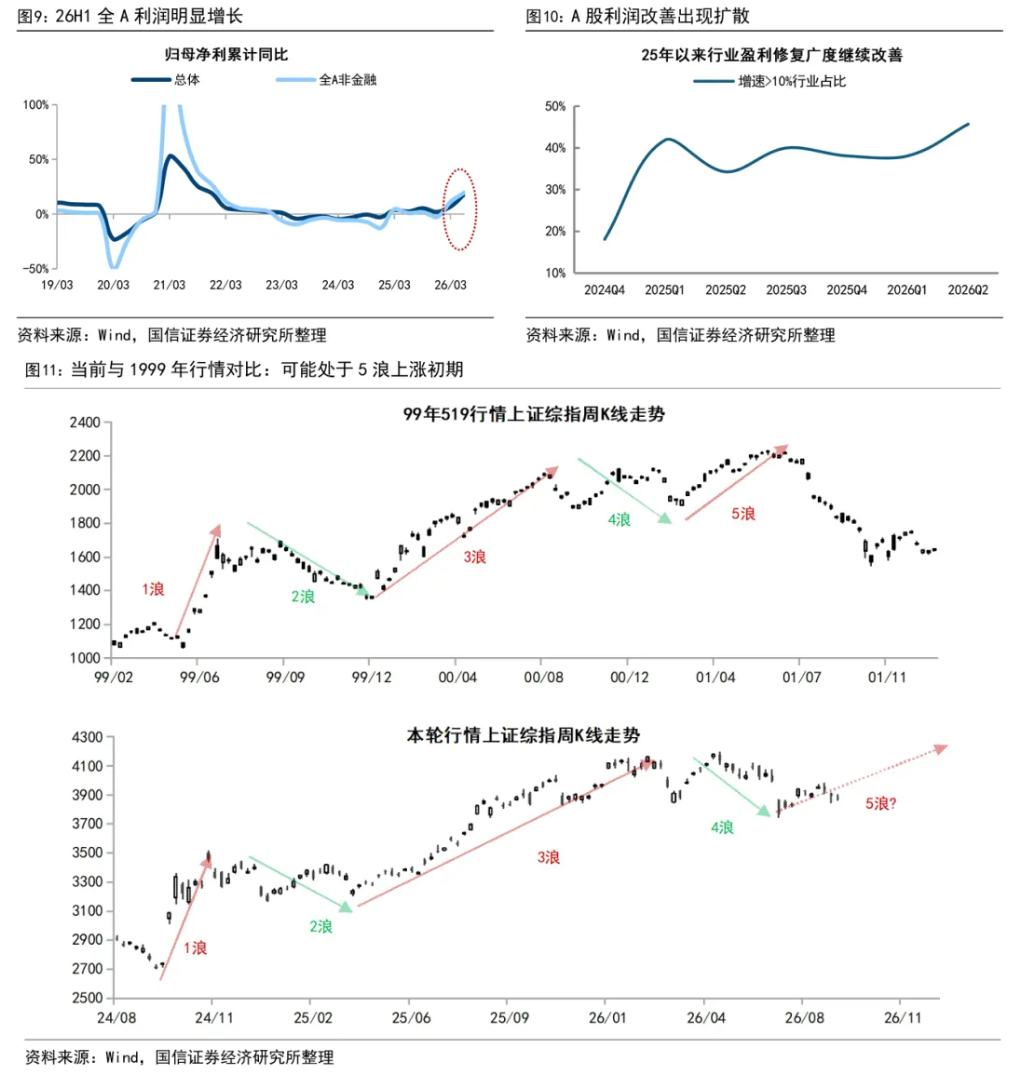
Market cycle positioning: The bull market is in the third phase. Since the July adjustment, some investors' belief in the bull market has wavered. We believe that the current bull market is not over. Market fluctuations in the third quarter are normal adjustments in the middle to late stages of the bull market. The bull market has its own cyclical rules. It can be divided into three stages: incubation period, outbreak period, and bubble period. The driving forces are strong policies, profit improvement, and capital entry. In response to this round of the bull market, the 24-year 924 policy stepped up to start the first phase of the bull market. The second phase of the bull market began in 25Q2. During this period, the net profit of A-shares improved year on year, and profit improvements gradually gained momentum.
Looking at the current point, the corporate profit growth rate continues to recover. The year-on-year growth rate of all A's net profit in '25 was only 2.0%. Excluding finance, growth was negative, but it rebounded to 15.9% and 15.1% respectively in the first half of '26. At the same time, the breadth of fundamental improvements is also expanding. Measured by the share of industries in Shenwan's second-tier industry where net profit growth rate exceeds 10% year-on-year, the breadth of overall A profit improvement increased from 38% in 25Q4 to 46% in 26Q2. Profit recovery combined with residents' capital entry process continues, and the A-share bull market is in its third phase.
We have always compared the market that began in '24 to the '99 519 market. The main reason is that the economy is in a transition period of switching between old and new kinetic energy. Compared to the pace at which the market is running, it is now similar to the end of February 2001. According to wave theory analysis, it is currently in the early stages of the 4-wave adjustment low and the 5-wave rise.
2. Fourth quarter outlook: the A-share market can be expected to end
As mentioned earlier, after experiencing a three-quarter turbulent correction, we believe that this round of the bull market is not over, and there is still room for interpretation. Looking ahead to the fourth quarter, the A-share market is expected to usher in a recovery window due to multiple positive factors at home and abroad, and the end of the market can be expected.
From a domestic perspective, policy increases are promoting the spread and restoration of fundamentals, and there is still room for insurance funds and residents' funds to enter the market. In terms of fundamentals, the current macroeconomic performance is fair. The PMI data for September recorded 50.1%, which rebounded to the expansion range; at the same time, the profit recovery process of A-share micro enterprises continued during the year, and the ROE (TTM) of all A-shares in 26Q2 showed a recovery for the first time in 22 years. However, an important factor hampering the further restoration of macro-micro fundamentals is still K-type differentiation between the old and new economies. Looking ahead to the fourth quarter, domestic policies are expected to be further strengthened. On September 28, the National Standing Committee emphasized the need to “step up countercyclical adjustment of macroeconomic policies” and “introduce a number of pragmatic and practical incremental policies.” On the 29th, the central bank and three other departments jointly issued a document. For the first time, the central government discounted interest rates on commercial personal housing loans. We believe there is still room to increase the domestic demand growth policy in the fourth quarter, which is expected to support the diffuse restoration of macro-micro fundamentals.
In terms of capital in the stock market, the scale of active capital entering the market since this year is quite impressive. In the first half of the year, bank transfers and private equity inflows were about 1.2 trillion yuan and 800 billion yuan respectively. In addition, allotted capital such as insurance capital and foreign capital were also the main forces entering the market, but there were twists and turns in the entry of public equity funds into the market. Looking ahead to the fourth quarter, there are still expectations for incremental capital. On the one hand, the current round of residents' capital entry process may be in the middle and late stages. There is still room for capital entry into the market from the perspective of indirect market entry through public fund channels, and funds related to market risk appetite correction are expected to catch up in the future; on the other hand, benefiting from the increase in premium income of insurers this year, and new regulations on insurance companies requiring listed state-owned insurers to allocate 30% of their equity assets each year. Against the backdrop of declining domestic risk-free interest rates, insurance capital also has room to enter the market.
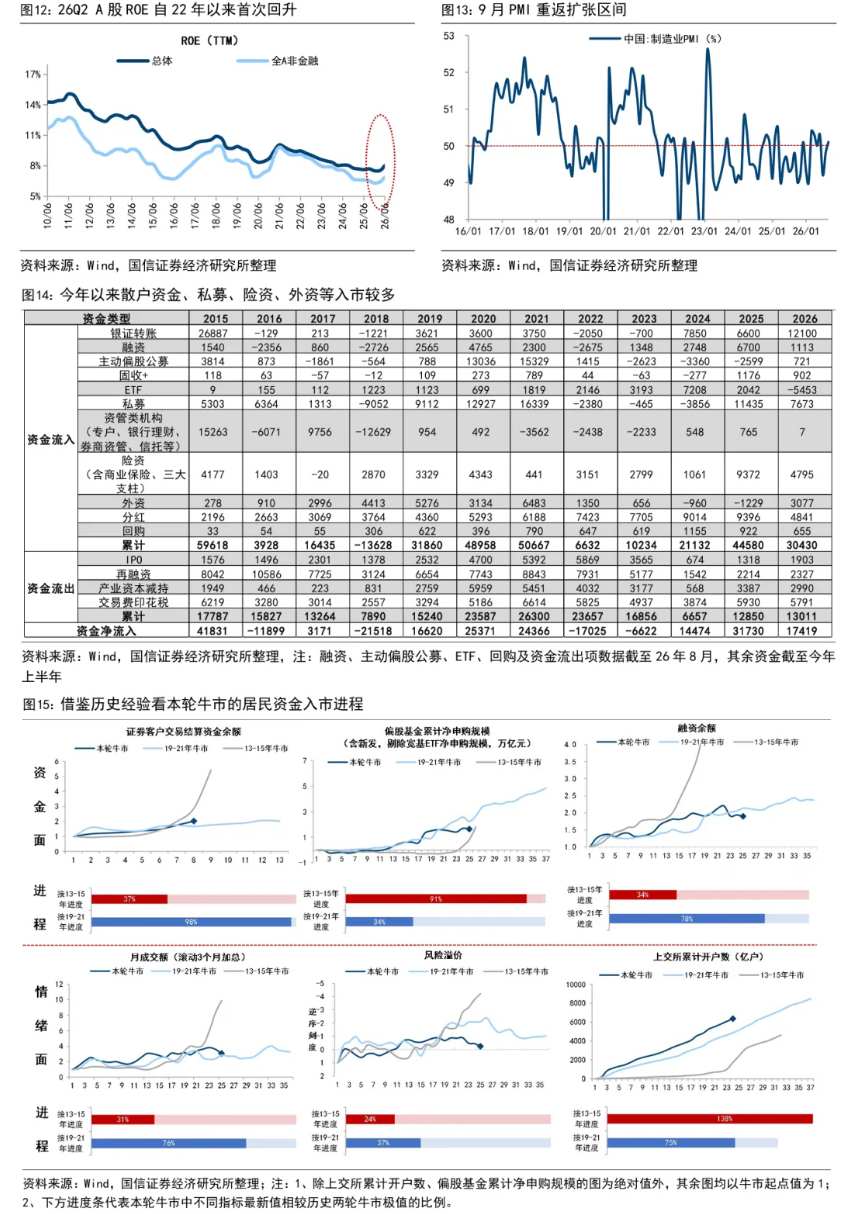
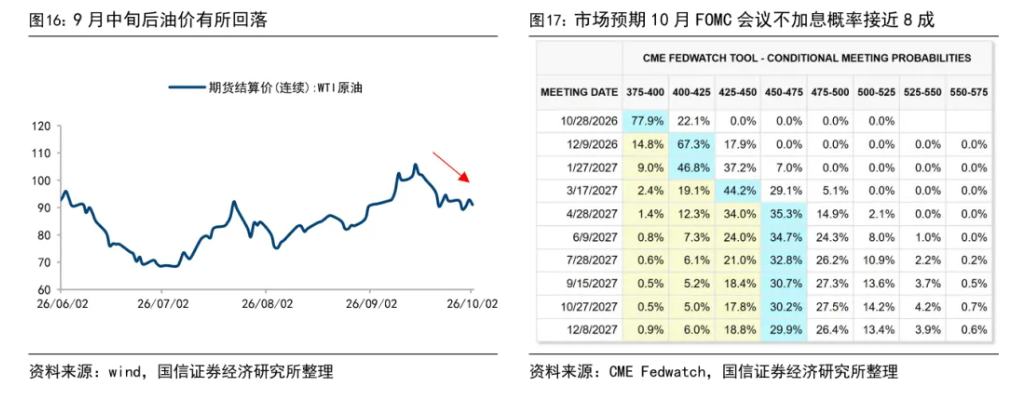
From an overseas perspective, the global liquidity environment may not deteriorate in the future. Looking back at the third quarter, external disturbances that limited the recovery of the A-share market stemmed from geographical conflicts and expectations of global liquidity contraction. Interest rates on 10-year US Treasury bonds once broke through 5.3% on October 1, reaching a new high since 2002. Recently, however, signs of improved overseas liquidity have continued to increase. On the one hand, the number of US non-farm payrolls increased by 29,000, falling short of market expectations of 90,000. The unemployment rate was 4.2%, which is slightly higher than market expectations of 4.1%. The probability of interest rate hikes has cooled significantly from before. Currently, the market expects the probability of not raising interest rates at the October FOMC meeting to be close to 80%; on the other hand, the US and Iran have recently proposed that the EU and IEA member states launch a new round of diesel and crude oil reserves. $106 per barrel fell back to a recent low of $90 per barrel. Judging from the performance of overseas equity assets since October, the stock market's pricing on the tight liquidity environment is slowing marginally. After the 10/2 non-agricultural data was released, the NASDAQ closed up 1.2%, reaching an intraday high of 27,353.7 points, another record high.
Looking back, considering that the US midterm elections are gradually approaching, high energy prices are putting a lot of domestic political pressure on them, or hampering the continuation of the US-Iran conflict. Combined with Iran's need to end the conflict as soon as possible, Iran will also re-evaluate the costs and benefits of continuing confrontation based on factors such as its own economic situation and international diplomatic support. Therefore, it is unlikely that the Middle East geopolitical conflict will continue in the medium to long term. We think we can see an end window around the fourth quarter.
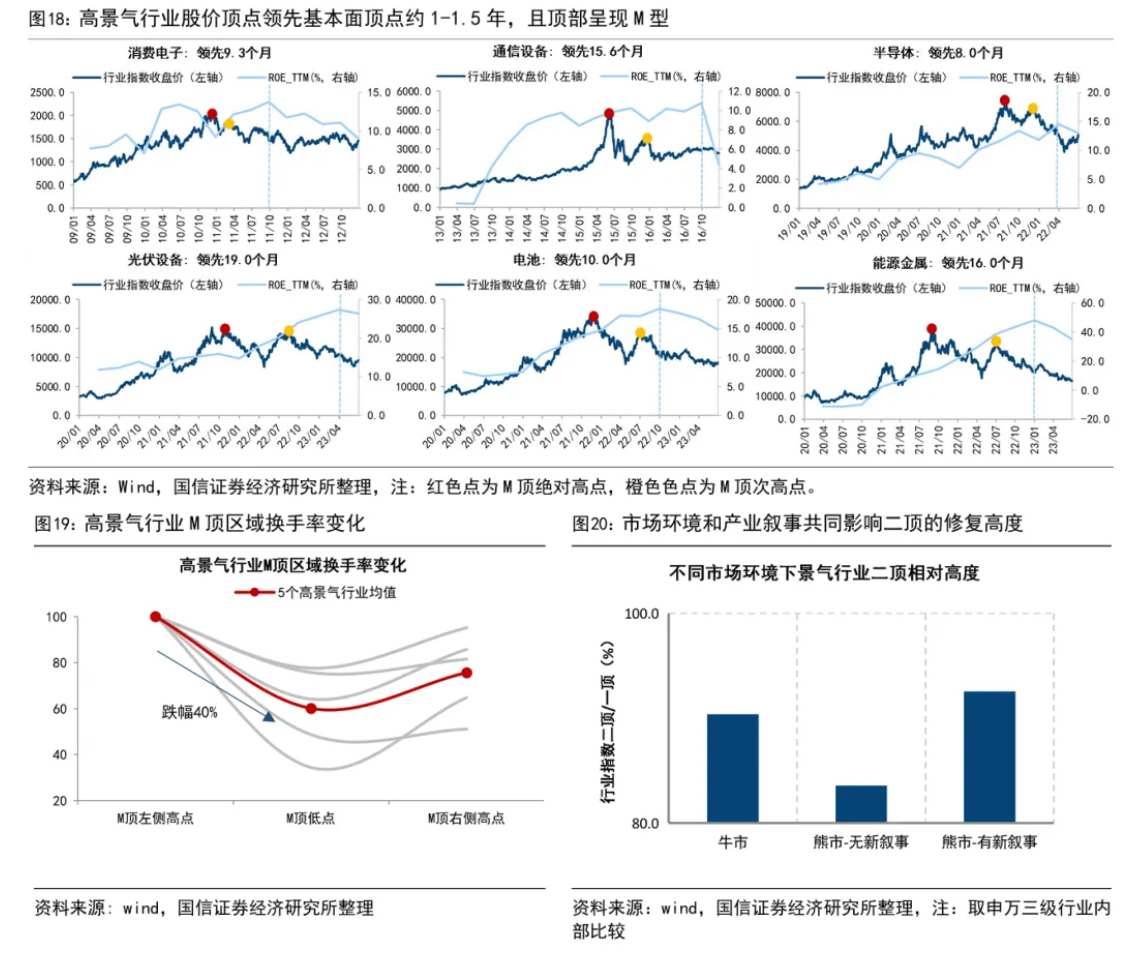
In addition to the macro factors mentioned above, the bull market since the current round of 24/9/24 was a technology bull driven by the AI industry, so the fourth quarter performance of the technology sector was the core variable affecting the final market of A-shares. Our previous reports indicate that this round of technology markets has the characteristics of an M-type double peak, and the second wave is expected to begin around the fourth quarter. Recent positive signals indicate that the second wave of technology markets is about to come out, hoping to support the rise in the market.
Technology hopes to usher in a second wave of gains at the top of M, supporting the rise in the market. The top of the historically booming industry was often M-shaped. In a round of retracement from top to bottom, the average decline was about 40%, the average retracement period was about 4 months, and the average decline in turnover share and turnover rate was nearly 40%. In the future, expectations of policy austerity fell, or early industry concerns were eliminated, and new demand drove up expectations to actually start the second wave of the market. Furthermore, drawing on the experience of a historically booming industry, the deeper the fall in the early stages, the more intense the second wave of rebound after the low point is usually more intense. At the same time, when the market is in a high wind environment, or when the industry is catalyzed by a new strong narrative, the second highest level of the industry can reach a higher level.
Looking at the current moment, we believe that the technology industry is in the midst of a retracement from its first peak to a low point. Since mid-September, due to the resonance of factors such as improving the global liquidity environment, clearing sentiment and chips, and catalyzing a new industry narrative, the conditions for starting the second wave of the technology sector have gradually been put in place. The variables that need to be focused on in the future are mainly the liquidity environment and the verification of industrial sentiment. Recently, the pressure of liquidity contraction has been alleviated. Combined with overseas technology companies releasing new models one after another, it can be seen that positive signals are emerging in the technology sector before and after the holidays.
Overall, as this round of the A-share bull market enters the third phase, and favorable factors at home and abroad resonate, the second wave of the rise in technology is expected to drive the market to rise again. If the oil price center continues to decline, the Federal Reserve's austerity expectations ease, compounded by the continued high growth rate of AI revenue from overseas cloud vendors, and there is room for a rebound. Looking at the longer term, China's industrial upgrading continues to evolve, and the successful conversion of old and new kinetic energy is expected to occur during the “15th Five-Year Plan” period. This will lead to a systematic rise in the ROE level of A-shares. The overall restoration of fundamentals will support the opening of a more comprehensive bull market.
3. Industry configuration: technology still has a second wave of opportunities
The current policy environment is still relaxed, macro and micro fundamentals are gradually being repaired, the trend of residents' capital entering the market is accelerating, and the A-share bull market is expected to gradually enter the third phase. Structurally, technological growth, which has a comparative advantage in fundamentals, is still the main line of the stock market. Furthermore, as the bull market enters the middle to late stages, the industry structure is also expected to gradually spread, and emphasis can also be placed on AI applications in technology, resource dividends, and real estate consumption.
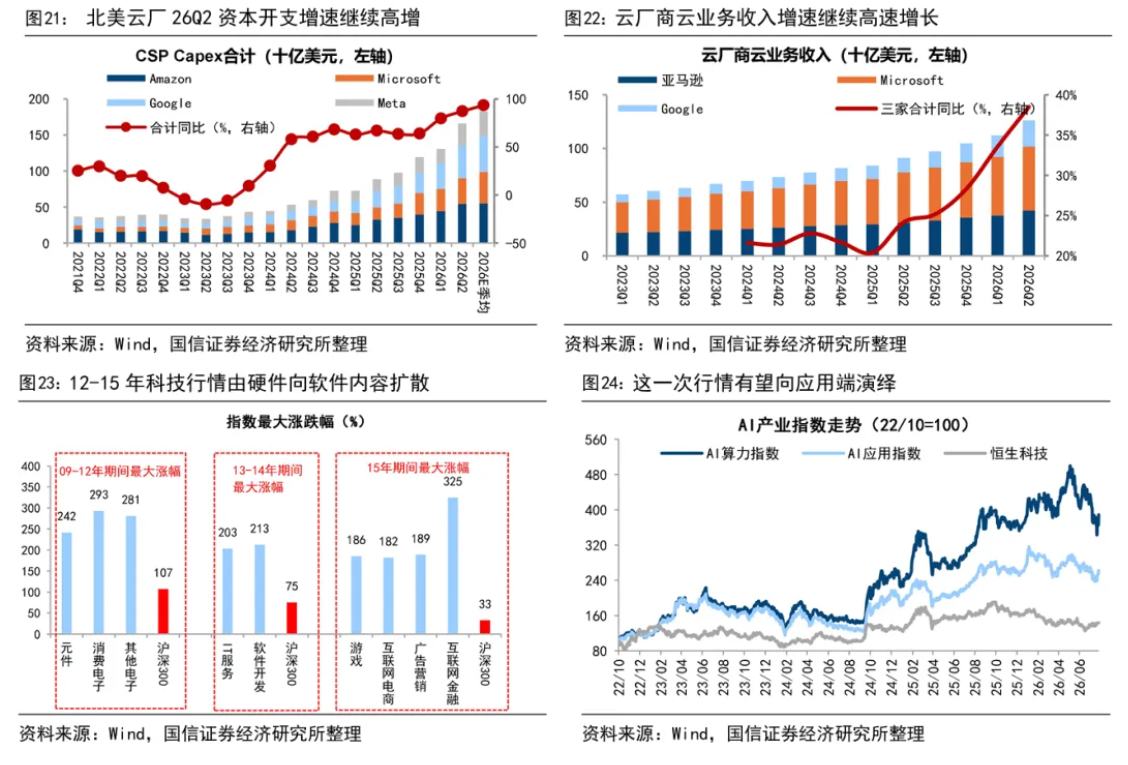
AI technology is still the main line of the industry, and emphasis is placed on the spread of AI applications. The trend of the AI industry continues, the computing power chain boom continues to improve, and the growth space for domestic alternatives is further opened up. Overseas, the capital expenditure support of North American cloud vendors continued to rise. The capital expenditure of the four major CSPs in 26Q2 increased 87% year on year, and the capital expenditure guidelines for the full year 2026 were raised to over US$730 billion. At the same time, Google, Amazon, and Microsoft's 26Q2 cloud business revenue growth rate reached 38.5%, a further increase from 33.6% in Q1, and demand growth supported continued investment. Recently, manufacturers such as OpenAI, Anthropic, and DeepSeek have successively released new models. Training requirements and inference calls are expanding together, which is expected to drive the computing power industry chain to continue to improve. Domestically, domestic computing power substitution is advancing at an accelerated pace. In September, Huawei released the Shengteng 960 supernode with an NPO light engine and full liquid cooling design; at the September Yunqi conference, Ali unveiled the new-generation self-developed AI chip Zhenwu V900, and announced that the self-developed AI supernode will be commercially launched on a large scale starting this season. It can be seen that domestic autonomous computing power construction continues to advance from technological upgrading to large-scale application. After early adjustments, the popularity of trading in the A-share computing power hardware sector has declined markedly, and the chip structure has improved. Combined with the expansion of overseas demand and domestic substitution, computing power hardware is expected to usher in a second wave of the M-peak market.
The AI technology market is also expected to spread to the application side. Looking back at the mobile internet wave in 12-15, the technology industry chain gradually spread from the hardware side to the application side under the catalyst of technological breakthroughs and cost reduction and efficiency. In this wave of AI, as model performance improves and inference costs decrease, the space for commercial AI applications is expected to open up further. At the beginning of September, Meta launched Muse, a personal intelligence device, and expanded Muse to small business scenarios at the end of September, greatly expanding AI application implementation scenarios. Since then, OpenAI has launched DOTS, an agent that continuously performs tasks in the background, to compete with Muse. Giant competition is expected to accelerate product iteration, ecological construction and user cultivation, push AI applications from functional experience to continuous use and commercial payment, and boost domestic application-side expectations. With the rapid development of multi-modal models, artificial intelligence is expected to penetrate many end-side scenarios in the future, and there is plenty of room for growth in fields such as consumer electronics and physical intelligence.
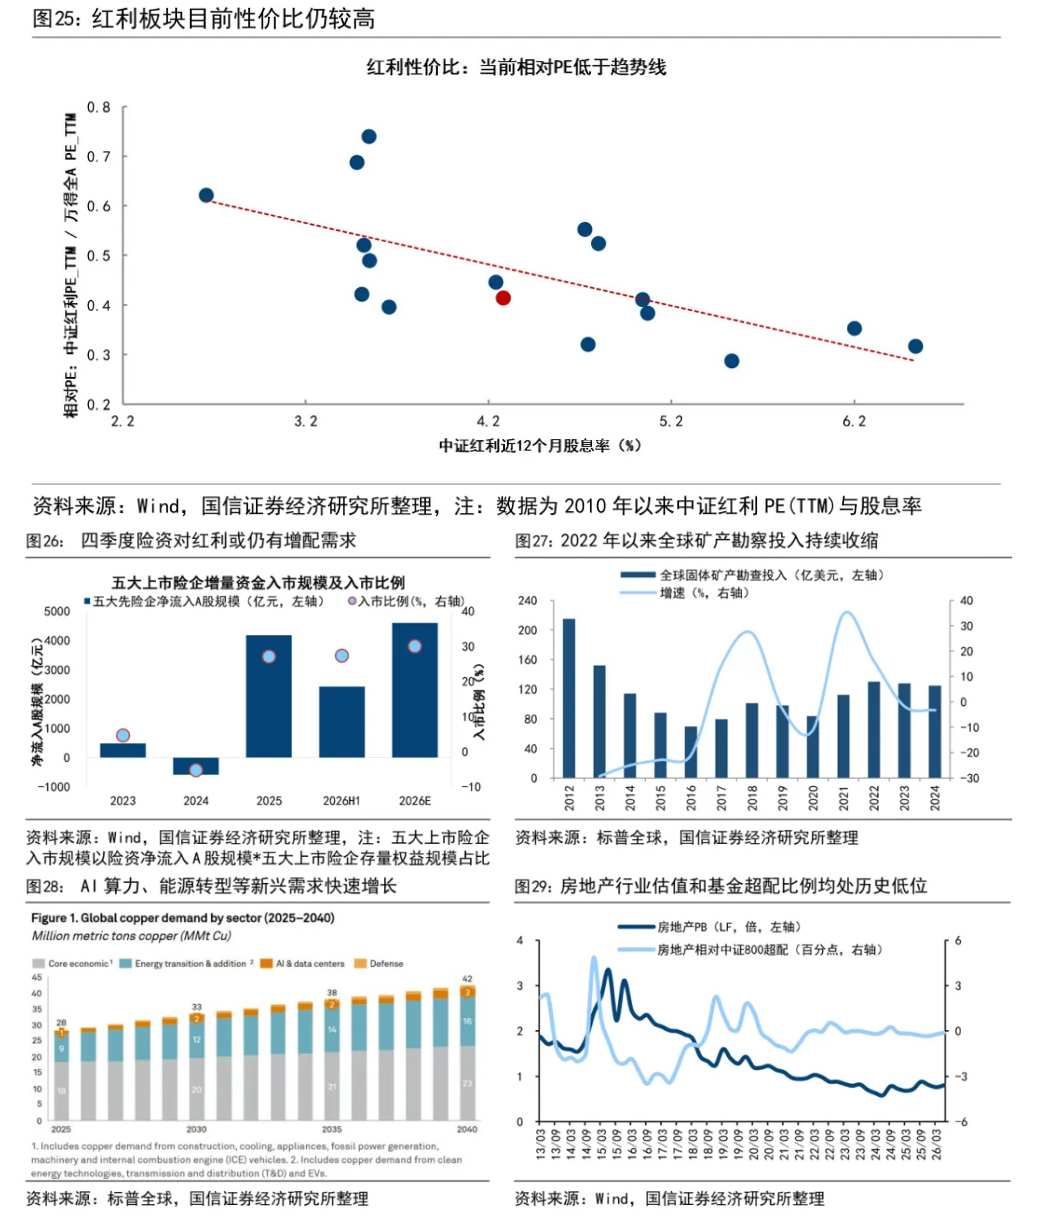
Long-term capital accelerates market entry and the central rise in the price of resource products, with emphasis on resource dividends. Dividend assets have performed well since the third quarter, and are still very attractive. As of 26/9/30, the valuation level of the China Securities dividend compared to Wandequan A was still at an historically low level. The China Securities dividend was 0.41 compared to PE, 40% over 10 years, and 0.49, or 29% compared to PB. Looking at the dividend rate, the current dividend rate (TTM) of the China Securities Dividend Index is 4.2%, which is 51% over the past 10 years, and is near the historical median level. Therefore, from the perspective of historical price comparison, current dividends are still very attractive.
Looking ahead to the fourth quarter, insurance capital may require additional dividends. Judging from the entry of large state-owned insurance capital into the market since this year, the net inflow into A-shares of the top five 26H1 listed insurers is probably 352.3 billion yuan, accounting for 27.3% of their operating cash flow during the same period. If the top five listed insurers can achieve the 30% market entry target this year, then the incremental capital entry scale of the top five listed insurers in Q3-Q4 may exceed 200 billion yuan. As the policy actively guides medium- to long-term capital into the market, dividend assets may be expected to increase the allocation of long-term capital in the fourth quarter. Pay attention to resource dividends from changes in supply and demand patterns, such as coal, utilities, etc.
Furthermore, the real estate and domestic demand sectors are making up for gains under policy catalysts. In this round of the bull market, sectors such as real estate and consumption performed relatively poorly, and valuations and institutional allocations were low. On September 28, the National Standing Committee called for greater countercyclical adjustment of macroeconomic policies. Since then, real estate policy support has been further extended to the demand side. On September 29, three departments including the Ministry of Finance introduced interest rate discount policies for residential home purchase loans. As policies to expand domestic demand continue to be strengthened, real estate and domestic consumption related sectors may be expected to recover.