


Spain’s snap election on 29 November puts housing policy, construction plans and rental rules into the spotlight, and the outcome could reshape where capital flows next. Political risk is rising, yet pro housing supply policies remain a live theme that many investors are watching closely. This article walks through three Spanish Construction & Building Materials Benefiting from Pro housing Supply Policies screener stocks that look most exposed to the news and explains what that might mean for your portfolio thinking.
The three Spanish Construction & Building Materials Benefiting from Pro housing Supply Policies stocks covered below are only a sample. The full screen identified 11 more Spanish listed construction, engineering and materials companies with equally compelling narratives that are not discussed in this article. To see the wider set of opportunities, head straight into the Spanish Construction & Building Materials Benefiting from Pro‑Housing Supply Policies screener to identify, filter and analyze potential high conviction ideas across this housing focused segment.
Sacyr (BME:SCYR)
Overview: Sacyr develops and operates infrastructure concessions such as transport links, water systems and civil engineering projects that support urban development.
Operations: The group generates most revenue from Sacyr Engineering and Infrastructure at about €3.1b and Sacyr Concessions at about €2.0b, with Spain contributing roughly €1.9b.
Market Cap: €3.2b
Sacyr matters for this housing focused screen because its concession model and engineering arm sit close to where new urban infrastructure gets built when governments push to expand residential supply.
"The company's active rotation of mature assets and reinvestment into higher-margin or growth opportunities (for example, Colombia divestment, redeployment in the U.S. and Europe) is improving geographic diversification and will reduce risk concentration while supporting future earnings growth and net profit."
What really moves the story for Sacyr now is how one unresolved policy shift could filter straight through to future project margins.
Those policy choices could be the catalyst that flips Sacyr’s risk reward profile, and the full narrative for Sacyr unpacks how shifting margins might reprice the stock.

Inmobiliaria del Sur (BME:ISUR)
Overview: Inmobiliaria del Sur develops, owns and manages residential and commercial real estate across Spain, linking directly to housing supply.
Operations: The group generates about €82 million from Real Estate Promotion, €66 million from Construction and €20 million from Rental Property, all in Spain.
Market Cap: €305 million
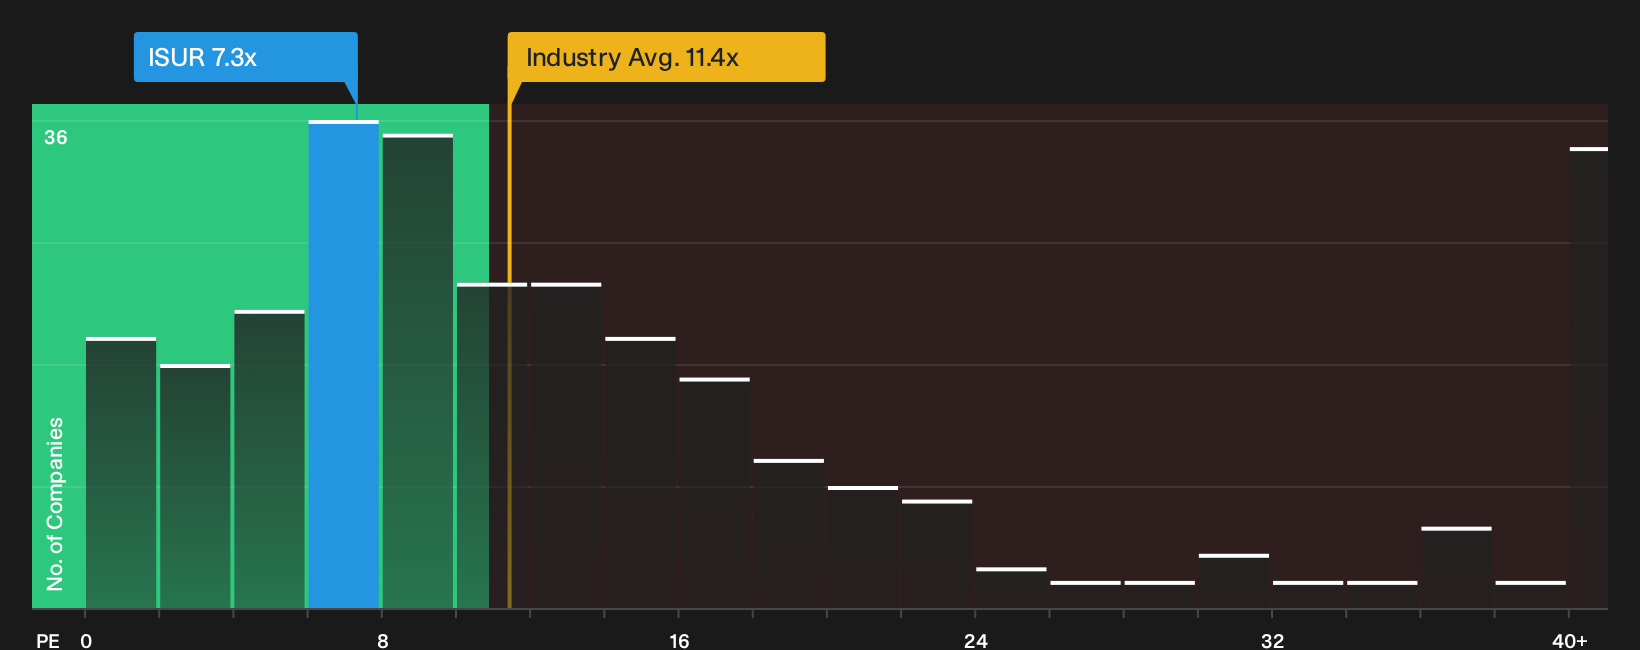
Inmobiliaria del Sur plugs directly into Spain’s housing supply story through real estate development, rental assets and its own construction arm, all within one vertically linked model. The stock trades on a low P/E with profit margins near 19%. The key consideration for investors is how pro housing policies interact with its reliance on externally funded growth if a single key assumption breaks.
If that funding hinge worries you, review the 4 key rewards and 3 important warning signs (1 is major!) to see how Inmobiliaria del Sur’s current setup could amplify either upside or strain.
Obrascón Huarte Lain (BME:OHLA)
Overview: Obrascón Huarte Lain is a Madrid based infrastructure contractor that builds and maintains large civil works and buildings for public and private clients across Spain, North America and Latin America. This ties it naturally into any future push to expand or refurbish housing related infrastructure.
Operations: Obrascón Huarte Lain generates about €3.4b from Construction, €113 million from Industrial and €58 million from Other activities, with Spain and US and Canada key end markets.
Market Cap: €498 million
Obrascón Huarte Lain matters in this housing focused screen because its core civil works business often sits near residential projects, from access roads to urban renewal. A busier building pipeline could quickly feed into its order book and cash generation profile.
"Although the construction division enjoys a robust EUR 7.662 billion short term backlog, which is equal to more than 25 months of sales, any slowdown in infrastructure tendering in North America and Europe could reduce future order intake and constrain top line growth beyond 2026, limiting revenue expansion."
The real swing factor for Obrascón Huarte Lain now is how one shift in future tender activity interacts with its current housing related exposure.
That inflection point is exactly what the full narrative for Obrascón Huarte Lain unpacks, revealing how housing linked contracts, balance sheet repair and tender risk could be quietly reshaping Obrascón Huarte Lain’s trajectory.

Seeking Alternatives Before The Crowd
Fresh ideas move first. Late money can get caught as momentum fades, breakouts stall and prices start dropping. Scan what others miss while it matters and get in early.
- Look for reliable cash generators by scanning a curated list of solid balance sheet and fundamentals (207 results) that helps you focus on sturdier balance sheets early in the process.
- Explore accelerating themes through the hand picked 615 high quality undiscovered gems that highlights under the radar companies while expectations may still be forming.
- Review quality income ideas using a refined 161 dividend fortresses that surfaces higher yielding payers while prices remain a key consideration.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com