


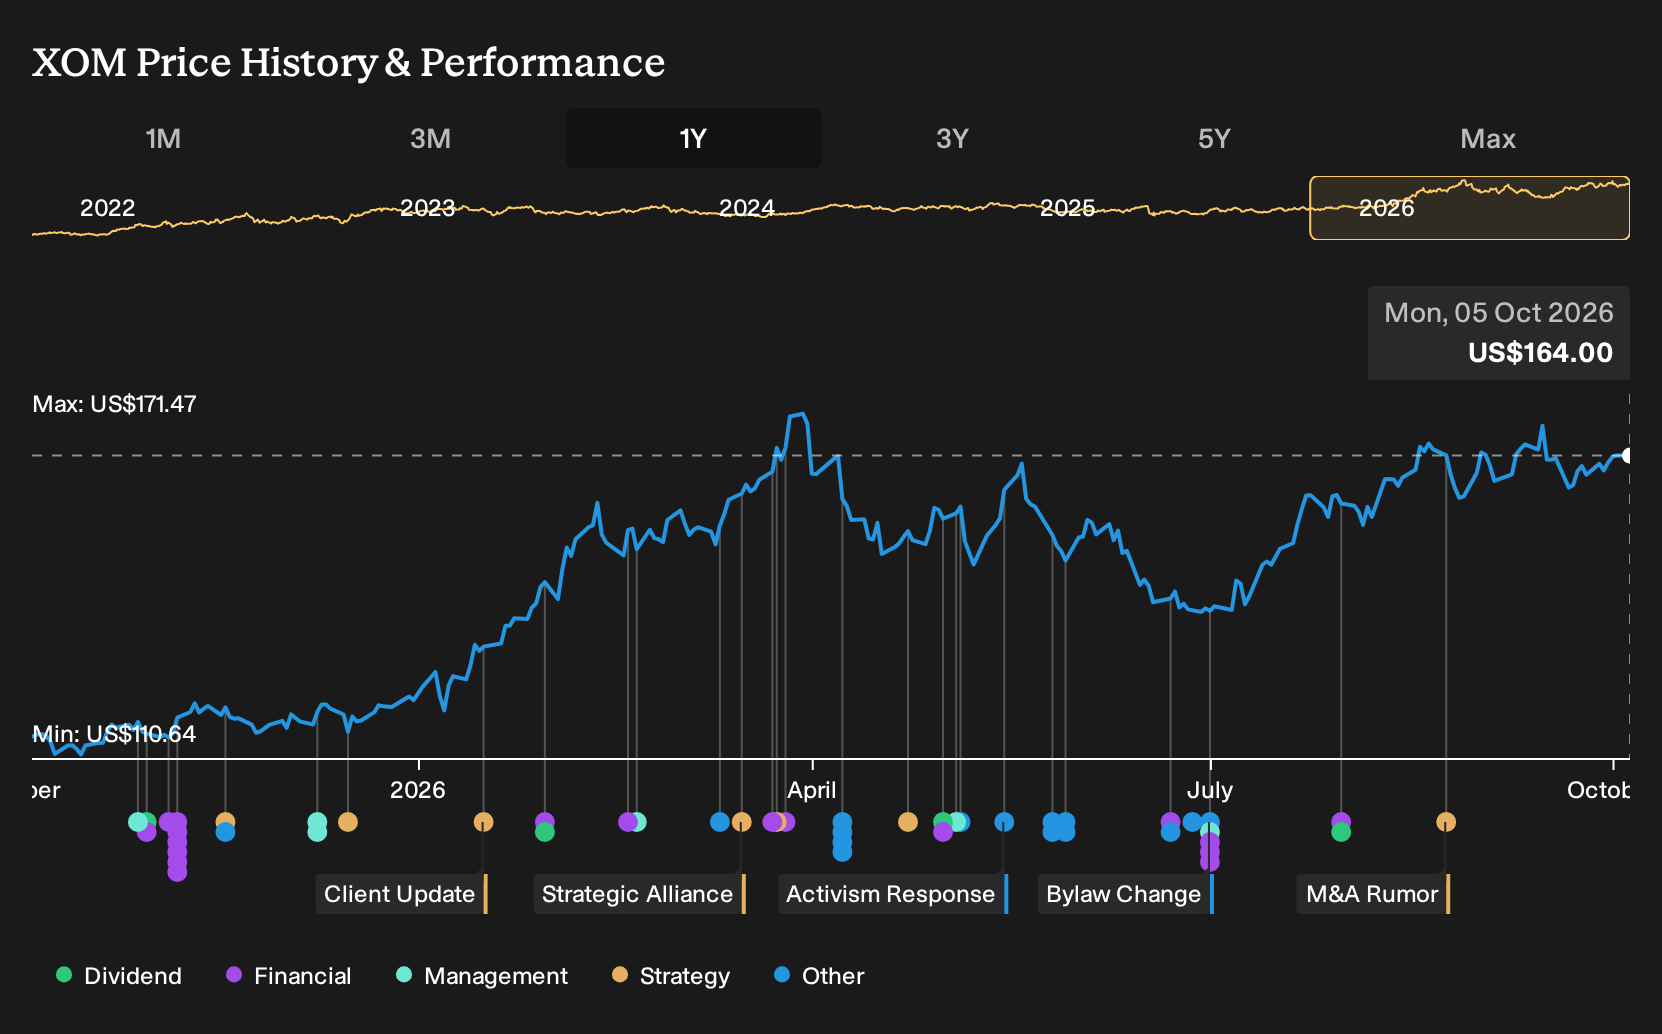
Holding ExxonMobil over the past year would have returned 47.8%, including dividends. If you had put fresh money to work on 5 October 2025, you were choosing between a bullish case that leaned on low cost barrels in Guyana and the Permian and a bearish view that saw Exxon on the wrong side of the energy transition. Which of those competing stories looked more convincing using only what was on the record that day?
ExxonMobil has already moved. See which of 27 high quality undervalued stocks still trade below our estimates.
The Two ExxonMobil Stories Investors Had To Weigh
The shares cost US$113 at the start of the period, which left investors choosing between a confident transformation story for ExxonMobil and a pessimistic energy transition view that pointed in the opposite direction.
On the bullish side, one analysis put a fair value of US$132 per share. That was the price that thesis said the stock should reach if its scenario played out, or 17% above the start price. The estimate was built on revenue growing 6.5% a year and a 9.7% profit margin supported by low cost barrels and a 14.7x future P/E assumption.
The bearish case argued for a fair value of US$78, or 31% below the start price. This view assumed revenue would decline 1.0% a year and profit margins would settle at 7.9% as fossil fuel reliance, regulatory clashes and energy transition risks weighed on the business, even if investors paid a 15.1x future P/E.
What The ExxonMobil Results Actually Tested
The biggest new fact was ExxonMobil’s Q2 2026 report. Revenue moved from US$79,477m in Q2 2025 to US$114,529m and net income excluding extra items from US$7,082m to US$14,525m, with net margin rising from 8.9% to 12.7%. That outcome aligned more closely with the bullish assumption that the business could support high single digit profitability.
The lesson is simple. When a thesis leans on margin strength, track the reported net margin against the original assumption and the revenue trend, not just the share price headline.
What ExxonMobil's Higher Price Is Asking You To Believe
ExxonMobil now trades at US$164, with the selected bullish Narrative placing its Fair Value above that level rather than below it. The argument leans on a shift toward lower cost barrels, stronger refining contributions and technology heavy projects across LNG, carbon capture and advanced materials.
On that view, today’s price still does not fully credit the idea that advantaged assets, new product lines and company wide efficiency gains can support stronger earnings power for years.
"Shift toward lower cost, higher return production as advantaged assets in Guyana, the Permian and LNG move toward roughly 65% of total output by 2030. This can influence revenue resilience and unit earnings across future cycles."
The price and this Narrative do not agree. → Uncover what this Narrative says ExxonMobil is actually worth
Where ExxonMobil’s World Needs Help
ExxonMobil’s projects still rely on one stubborn physical fact. Gas does not move itself.
Every molecule that leaves a field for power plants or export terminals must be squeezed to the right pressure first.
One specialist operator does almost nothing else. It designs, owns and runs compression units that keep gas flowing when reservoir pressure fades.
As data centers and LNG facilities search for dependable fuel, that compression work can start to feel less like a service contract and more like essential infrastructure.
That argument has a Narrative and a number behind it. → See the company one Narrative values 49% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com