


NETSTREIT (NTST) just rewired its debt stack by increasing senior unsecured term loans, adding a new US$400 million delayed draw facility, and using fresh borrowings to retire a US$200 million 2028 term loan.
Recent trading paints a softer picture for NETSTREIT. The share price has retreated about 13% over the past month and roughly 21% over 90 days, with the stock now at US$17.44. Even so, the 3 year total shareholder return is still up about 33%, suggesting long term holders have seen gains while short term momentum has faded as investors reassess risk and the value of this new funding flexibility.
Scan how NETSTREIT’s refinancing approach compares with peers by reviewing a curated 31 resilient stocks with low risk scores built around balance sheet strength and resilient profiles.Recent weakness in NETSTREIT’s share price sits against a backdrop of expanded funding options and longer debt maturities. Is the pullback signaling concern about the business, or simply a reset in sentiment ahead of the next round of valuation work?
Most Popular Narrative: 23% Undervalued
NETSTREIT’s most followed narrative pegs fair value at about $22.62, comfortably above the last close at $17.44. This puts recent refinancing and equity moves into sharper focus for anyone weighing risk against potential upside.
Conservative balance sheet management, ample liquidity, and an improving cost of capital position NETSTREIT to pursue attractive external growth opportunities, enabling the company to accelerate accretive acquisitions that should positively impact AFFO per share and long-term earnings.
See why 5 investors see NETSTREIT as 23% undervalued.
Result: Fair Value of $22.62 (UNDERVALUED)
Still, the NETSTREIT narrative could be knocked off course if e commerce further weakens physical retail demand, or if acquisition driven expansion leads to overpaying for assets.
Find out about the key risks to this NETSTREIT narrative.
Another View On NETSTREIT’s Valuation
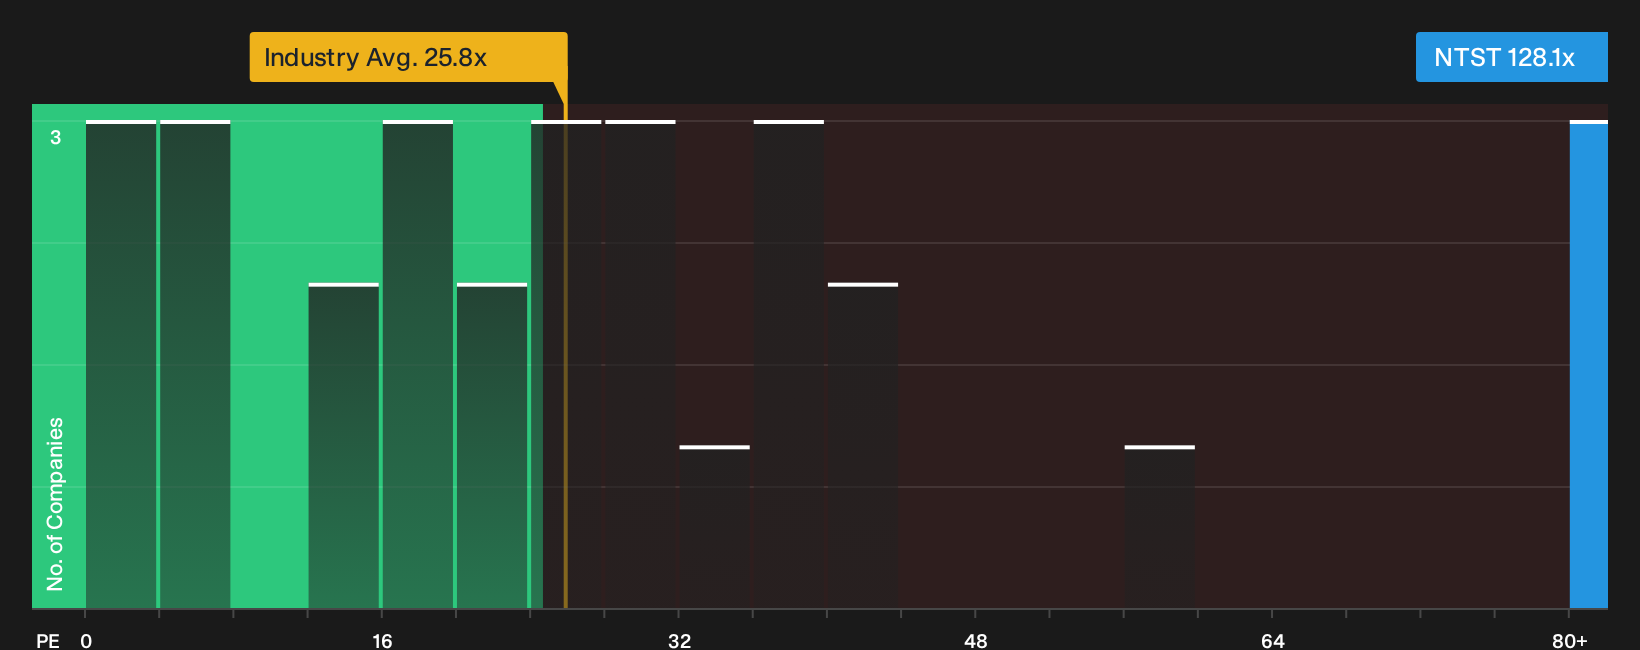
While the prevailing story frames NETSTREIT as undervalued against a fair value of $22.62, the current P/E of 128.1x tells a tougher story. It is far above the US Retail REITs average of 26x and well above the 46.3x fair ratio that the market could gravitate toward over time. That gap points to meaningful valuation risk if sentiment shifts or earnings delivery disappoints.
For a closer look at how this pricing stacks up against peers and that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between NETSTREIT’s refinancing story and its rich P/E multiple is natural. Move quickly from headline takes to the underlying detail and weigh both sides of the argument in the 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond NETSTREIT?
If NETSTREIT has your attention but you want a wider watchlist, use targeted screeners to spot other opportunities before they move away from you.
- Target potential value upside by reviewing companies flagged as high quality and potentially mispriced through the 27 high quality undervalued stocks.
- Anchor your portfolio around income by zeroing in on reliable payers using the 7 dividend fortresses.
- Build resilience into your holdings by focusing on financially robust businesses through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com