


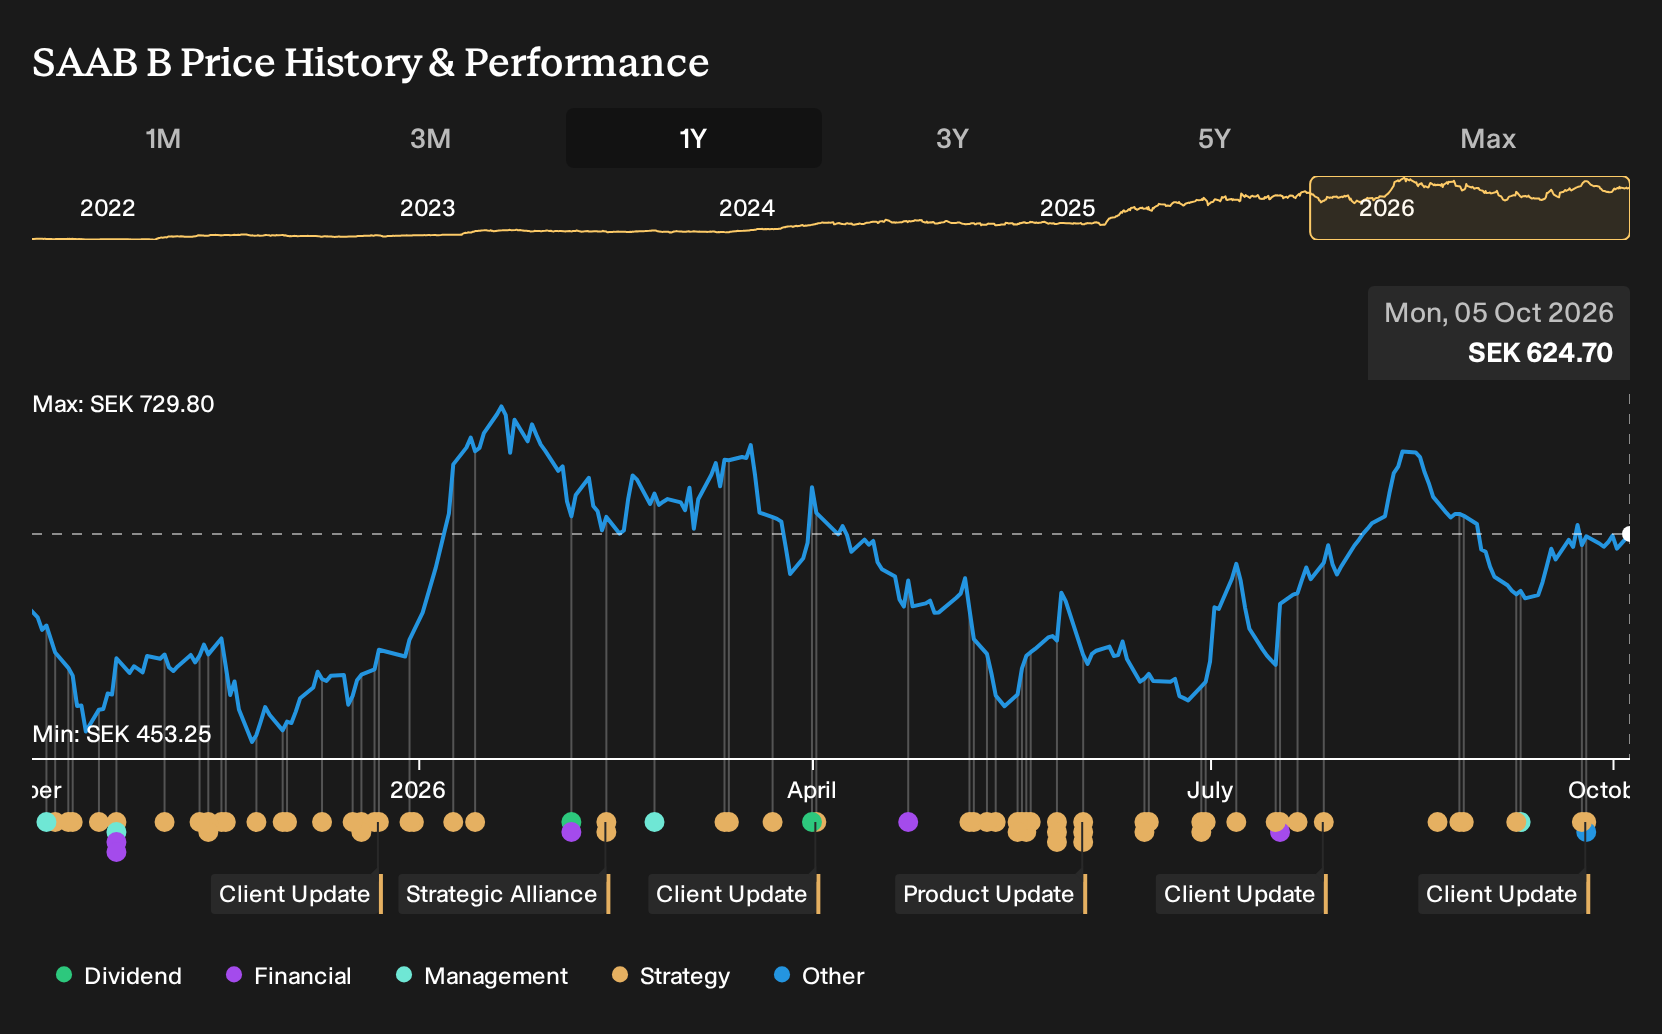
- Saab reported that in September 2026 it signed a non binding term sheet with Canada's Defence Investment Agency for potential acquisition of six GlobalEye AEW&C aircraft for the Royal Canadian Air Force, and separate MoUs with SSC Space, OHB Sweden and Ericsson to widen its role as a space systems integrator.
- The combination of prospective GlobalEye deliveries and new space partnerships points to Saab deepening its systems integration role across air, space and communications. This development could influence how its future backlog, R&D priorities and long term support revenues are shaped.
- We will now assess what this expanded GlobalEye engagement with Canada could mean for Saab's existing investment narrative and risk profile.
Saab Investment Narrative Recap
Owning Saab means believing that demand for complex sensing, command and control, and multi domain systems can sustain high R&D spend and keep factories busy. The GlobalEye talks with Canada and new space MoUs support that broad thesis, but the short term share driver still appears tied to execution on the existing SEK 200b class backlog and delivery schedules.
The biggest near term risk remains the same. Saab is leaning into capacity expansion and digital projects while depending on government budgets and export approvals. The Canadian term sheet is progress, yet it is non binding. If negotiations stall or timelines slip, those upfront costs could weigh more heavily on earnings and cash flow.
The Canadian Defence Investment Agency term sheet sits at the center of today’s catalyst debate. Six GlobalEye aircraft with systems, training and support would deepen exposure to high value surveillance and lifecycle work. For you as a shareholder, the key issue is whether those discussions turn into firm orders on a timetable that aligns with current investment in people and plants.
Failure to convert this framework into a signed contract would not undermine the broader Saab story, but it would leave the cost base and order book more reliant on other tenders. Success would add another allied reference for AEW&C and long term support revenues. Your decision is whether that risk reward trade off around order conversion and program delivery fits your tolerance.
Saab's current analyst story points to SEK 148.2b in revenue and SEK 13.3b in earnings by 2029. This outlook rests on 18.9% yearly top line growth and an earnings increase of about SEK 6.2b from SEK 7.1b today.
Uncover why Saab's fair value is consistent with its current price.
Exploring Other Perspectives
One alternate Saab story you may want to weigh focuses on contract risk. The most pessimistic analysts worried that big defence deals could slip or shrink, so they were only pencilling in about SEK 146.5b of revenue and SEK 12.7b of earnings by 2029. Those views were set before this Canada and space news, so you can now compare several competing narratives yourself.
Explore 5 other Saab fair value estimates, including one that suggests as much as 74% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Saab research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Saab. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Saab's overall financial health at a glance.
Looking for more Saab investment ideas and peers?
If you want to set Saab in context and uncover other opportunities that fit your style, the Simply Wall St Screener can help you quickly filter the market by quality, value and risk so you are not relying on a single story.
- For investors who care most about strong balance sheets and sturdy fundamentals, start with a curated list of solid balance sheet and fundamentals (207 results) that can sit alongside Saab in a more financially resilient watchlist.
- If your focus is on potential mispricing, compare Saab with a pool of 184 high quality undervalued stocks that combine solid business quality with prices that may not fully reflect their fundamentals.
- For income focused portfolios where Saab is just one piece, consider a shortlist of 161 dividend fortresses that aim to pair higher yields with staying power through different parts of the cycle.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com