


HEICO (HEI) is back in focus after being flagged for strong growth potential, with projected EPS expansion above the industry and fresh upgrades to current year earnings estimates supporting that narrative.
Recent trading has been choppy for HEICO, with the share price down 7.35% over the past month and 15.77% over 90 days, even as the latest close sits at US$301.57. That shorter term weakness contrasts with a 3-year total shareholder return of 82.99% and a 5-year total shareholder return of 124.64%. This indicates that long term holders have still seen strong compounding despite the recent loss of momentum as growth expectations and risk perceptions continue to reset around the upgraded earnings picture.
Capitalize on HEICO's growth theme by scanning a curated 19 high quality undiscovered gems that share strong fundamentals yet remain under the radar compared to more widely followed aerospace and defense names.HEICO’s share price has cooled while earnings expectations have heated up, leaving a gap between recent weakness and upbeat forecasts. Has most of the upside already played out, or does the current valuation still leave room ahead?
Most Popular Narrative: 23% Undervalued
HEICO’s most followed narrative pins a fair value of $393.70 against a last close of $301.57, framing the recent pullback as a discount to long term cash flow potential rather than a simple loss of confidence.
The main thing that has to go right is that HEICO continues to convert its enlarged acquisition pipeline and expanded credit capacity into high margin, cash generative deals that stay accretive within a year, while maintaining the higher margin framework now outlined for Flight Support Group and Electronic Technologies Group.
The EthosEnergy acquisition and growing demand for industrial and aero derivative gas turbine repairs linked to power needs from AI and large language models introduce a new adjacency for HEICO that can diversify revenue and support consolidated margins and cash flow.
See why 25 investors see HEICO as 23% undervalued.
Result: Fair Value of $393.70 (UNDERVALUED)
Still, the HEICO story can break if supply chain snags drag out repair timelines or if acquisitions dilute margins instead of lifting earnings power.
Find out about the key risks to this HEICO narrative.
Another View On HEICO’s Valuation
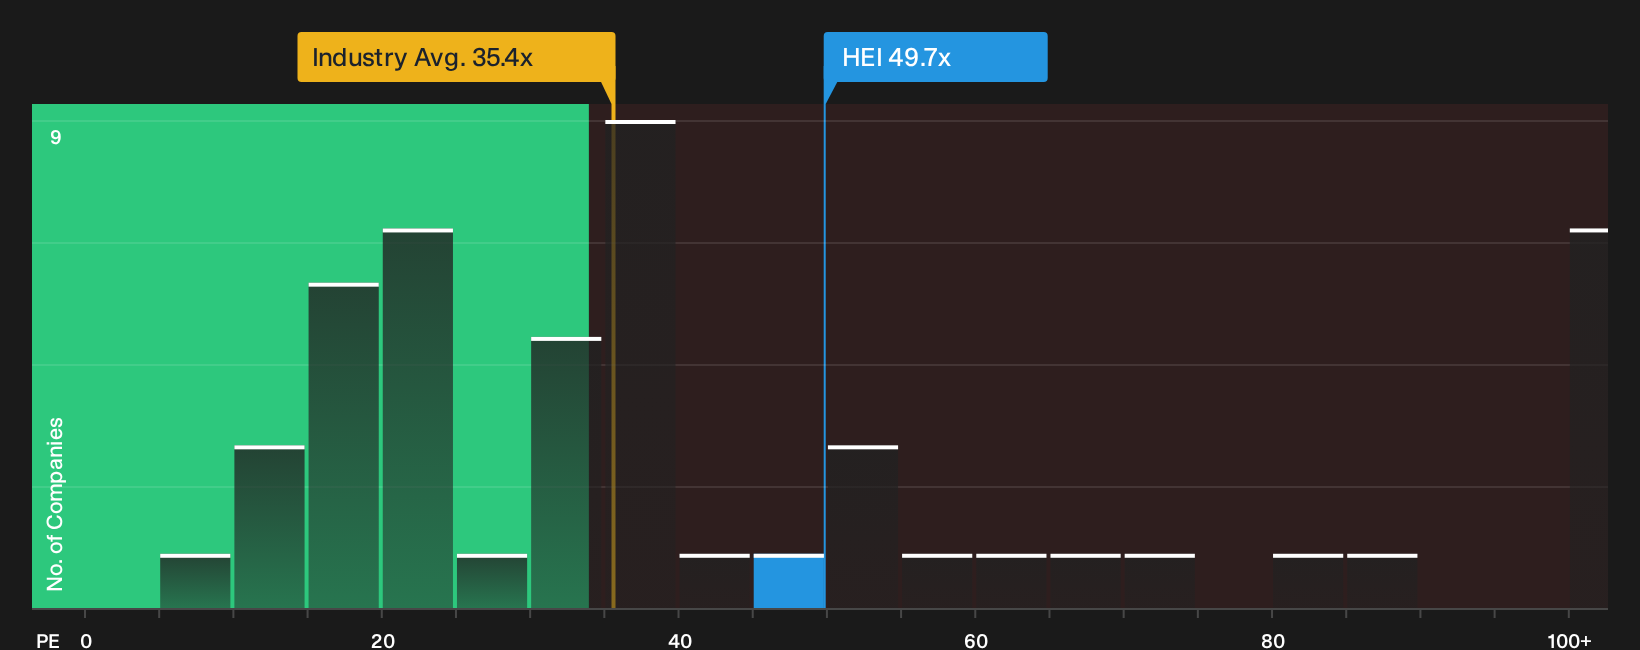
Analysts frame HEICO as 23% undervalued based on long term earnings assumptions, yet the current P/E of 49.7x is far richer than the US Aerospace & Defense average at 35.4x and also above the 27x fair ratio. That gap points to potential multiple risk if sentiment cools.
For a closer look at what the numbers imply for that valuation gap, have a read of our breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on HEICO’s outlook so far. If you want to move quickly and own your view, consider both sides by checking the 4 key rewards and 1 important warning sign.
Ready To Hunt For More Ideas Beyond HEICO?
Do not stop with one opportunity. Build a watchlist that fits your style by scanning focused stock ideas that line up with your return goals and risk comfort.
- Target potential mispricing by scanning companies that combine quality fundamentals with appealing valuations through the 27 high quality undervalued stocks.
- Strengthen income potential by reviewing steady payers with higher yields using the 7 dividend fortresses.
- Protect your downside by concentrating on sturdier businesses with healthier finances via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com