


- Pool Corporation (NasdaqGS:POOL) has appointed Jean-Marc Germain to its Board of Directors.
- Germain brings extensive international leadership experience from prior roles in global manufacturing and advisory-focused organizations.
- The appointment adds further board-level expertise in operations and governance as Pool weighs the long term direction for the business.
- The appointment of Jean-Marc Germain to Pool's board is a governance shift that investors may want to weigh carefully. Take a look at 1 warning sign we have identified for Pool.
This type of boardroom shift affects more than Pool alone, and there are other companies tied to similar governance themes worth exploring through 27 high quality undervalued stocks.
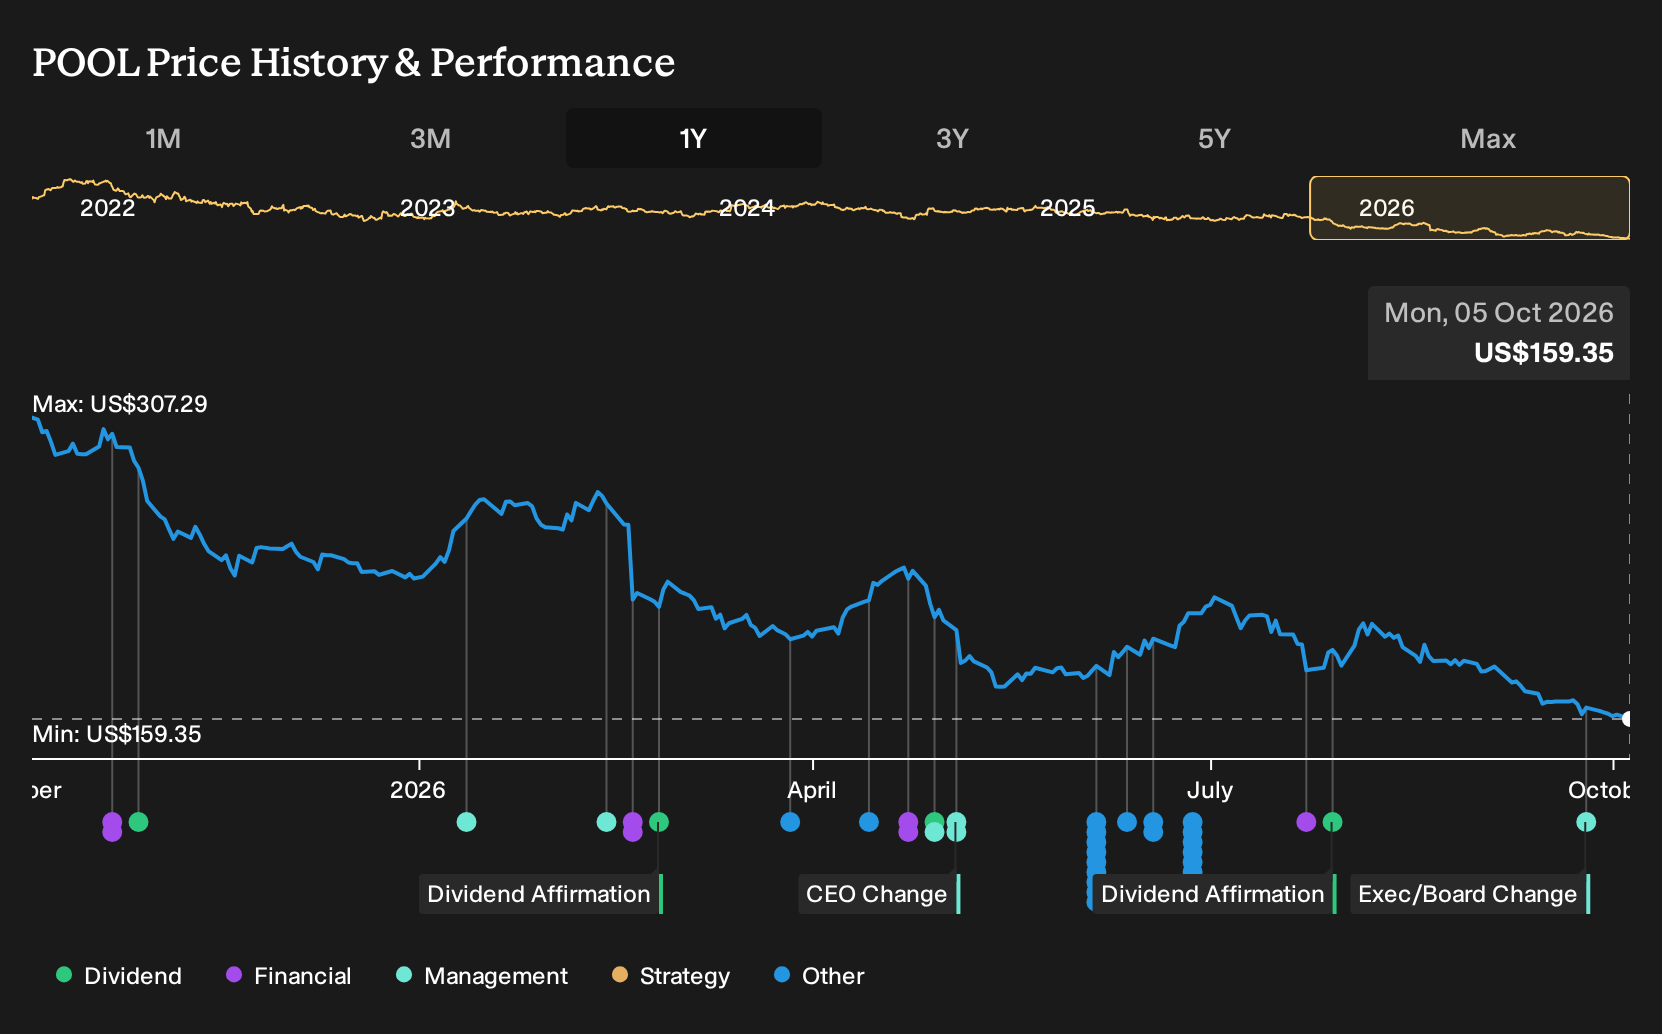
Pool operates as a large US retailer and distributor of swimming pool supplies, leisure products, and outdoor maintenance equipment, so adding international board experience speaks directly to how the business thinks about running a complex, cross-border distribution network.
Why might Pool want someone like Jean-Marc Germain on the board now?
Pool is leaning heavily on a large, maintenance driven business and a complex distribution network. Germain has run global industrial groups like Constellium and Algeco Scotsman, which also relied on logistics heavy operations and multi country governance. That background can help the board interrogate decisions around network efficiency, service levels and capital intensity.
Does this change the Pool Narrative investors have been using?
The existing thesis leans on POOL360 digital adoption, higher margin private label products and measured expansion of the sales center network. Germain’s experience in large scale manufacturing and distribution aligns most directly with that focus on efficiency, mix and disciplined capacity rather than aggressive footprint growth. The Narrative around cash returns and recurring maintenance revenue stays intact but may get a sharper operational lens.
See how these catalysts shape Pool's path to a $217 fair value.
What should investors watch next to gauge the impact of this board change?
The most concrete marker is Pool’s 2027 annual meeting of shareholders, when Germain’s initial term runs to a vote. Investors can watch disclosures and commentary into that meeting for any board level moves on POOL360 penetration targets, sales center openings or leverage and buyback parameters.
The one forecast check on Pool to run before you act
Before you treat this board move as your main signal, look at where analysts expect Pool’s earnings and scale to sit a few years from now, and how that compares to today’s set up. See where analysts expect Pool to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com