


BT’s planned £400m move for TalkTalk has pushed UK telecom regulation back into the spotlight and put a fresh question in front of investors: who benefits when big network deals run into complex competition reviews and public-interest tests? Legal and advisory specialists can find themselves right in the flow of that work. This piece explores three UK listed stocks exposed to this BT and TalkTalk story and why they may deserve a closer look now.
The sample of UK listed legal and advisory stocks in the rest of this article only scratches the surface, and the full screen surfaced 12 more companies with equally compelling regulatory and telecom deal narratives that are not covered below. To identify and analyze those additional opportunities with tighter filters and your own settings, head straight to the UK Telecom Regulatory & Advisory Services screener.
Knights Group Holdings (AIM:KGH)
Overview: Knights Group Holdings is a UK-based legal and professional services group advising corporates, lenders and institutions on transactions, disputes and regulatory issues including competition law.
Operations: The business generates about £208 million of legal and professional services revenue, all from clients across the United Kingdom.
Market Cap: £143 million
Knights Group Holdings fits this telecom regulatory and advisory screen as a broad UK legal platform that can sit close to complex deals without taking direct operator risk. This positions it squarely in the flow of work when transactions like BT and TalkTalk require heavyweight legal support.
"Knights Group Holdings is focused on premium service offerings and expanding their premium client base, which can contribute to revenue growth through enhanced pricing strategies and higher-margin work."
The central consideration is how one unseen pressure on its balance sheet interacts with demand for this higher value advisory work.
That hidden pressure is exactly what the full narrative for Knights Group Holdings unpacks, showing how Knights Group Holdings could still accelerate if advisory demand decouples from that risk.
Gateley (Holdings) (AIM:GTLY)
Overview: Gateley (Holdings) is a diversified legal and consultancy group providing corporate, regulatory, dispute and property-related advice across the UK and internationally.
Operations: Gateley (Holdings) generates about £194 million of revenue, driven mainly by Property at £101 million, Corporate at £40 million, Business Services at £35 million and People at £18 million, with most fees earned in the United Kingdom.
Market Cap: £97 million
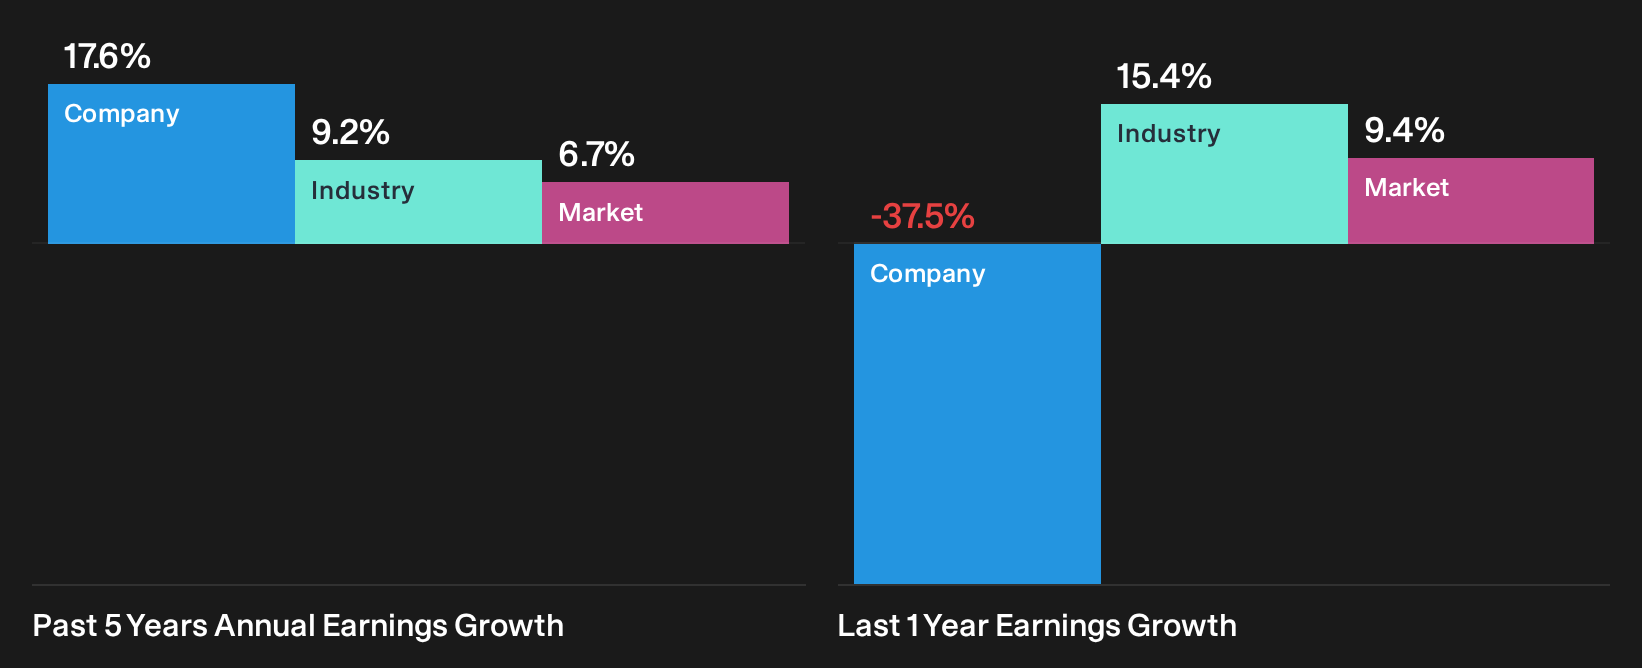
Gateley (Holdings) matters for this telecom regulatory theme because its mix of corporate, disputes and regulatory expertise lines up neatly with the type of advisory work complex BT and TalkTalk style transactions can generate.
"Although the enlarged revolving credit facility and strong M&A pipeline create scope to accelerate growth through acquisitions that leverage Gateley’s shared infrastructure, increased competition from private equity buyers and the risk of overpaying or underperforming deals could depress future returns on capital and earnings per share."
What happens to Gateley (Holdings)’ margins and growth potential if a single assumption about how that acquisition pipeline converts into profitable work breaks down?
If that assumption proves too optimistic or too cautious, the full narrative for Gateley (Holdings) shows where Gateley (Holdings)’ acquisition engine could still surprise investors on the upside.

Capita (LSE:CPI)
Overview: Capita is a large outsourcing group that runs complex public and private sector services, including regulated telecom-related customer and compliance operations.
Operations: Capita Public Service generates about £1.49b of revenue, while Capita Experience contributes roughly £756 million across contact centre and pension solutions.
Market Cap: £254 million
Capita matters for this telecom regulatory screen because its outsourced operations, data and compliance services sit close to the kind of public-interest work that BT and TalkTalk style deals can trigger.
"Capita is seeing robust growth in its public sector pipeline (with a £1 billion+ unweighted pipeline and over 50% TCV growth), supported by increasing public sector outsourcing due to fiscal constraints and a government focus on efficient service delivery, setting the stage for multi-year revenue growth and improved long-term revenue visibility."
What happens to Capita’s margins and contract mix if one key assumption about how quickly clients adopt its AI-led service model breaks.
If that assumption is wrong in either direction, the full narrative for Capita shows whether Capita’s AI push is quietly compressing risk or is primed to accelerate returns.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Opportunities with real breakout potential often gain momentum quietly, then start flying once attention hits. Scan these under-the-radar pockets now and review them before they attract broader attention.
- Target reliable income candidates with the 1 dividend fortresses and review which high-yield payers still trade as if potential future advances have not been fully reflected.
- Look for quietly compounding operators through the list of solid balance sheet and fundamentals (9 results) and focus on businesses where resilient finances may help support growth if sentiment changes.
- Track fast-moving themes by running the 91 AI infrastructure stocks and identify critical picks-and-shovels suppliers while they remain less widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com