


- AGCO has reworked its executive structure and reassigned senior leaders, while its Massey Ferguson brand agreed a supply partnership with International Tractors Limited to broaden a value focused compact tractor range across Europe and the Middle East from 2027.
- The leadership reshuffle links brand management more tightly with distribution, parts and precision ag, which suggests AGCO is trying to align day to day decision making with its higher margin technology and aftermarket ambitions.
- We will now look at how AGCO's leadership restructuring could reshape the existing investment narrative around precision ag and margins.
AGCO Investment Narrative Recap
To own AGCO, you need to believe the precision ag push, retrofit electronics and higher value brands can steadily shift the mix toward better margins even while core equipment demand looks soft. In the near term, the key swing factor is still execution on the PTx roadmap and aftermarket attachment as farmers weigh new technology spending against weaker volumes in key regions.
The biggest near risk remains prolonged sluggish demand layered with higher tariffs that are not fully passed through, which pressures utilization and margins. This leadership reshuffle and strategy update does not change those demand and tariff issues in a material way. It mainly affects how AGCO organizes to pursue its existing plan.
The executive restructuring on 5 October 2026 is the announcement that matters most for this story. AGCO is tying brands, PTx, parts and distribution more tightly under leaders who are now accountable for both financial results and cross-company functions. That directly connects precision ag ambitions to day-to-day decisions at Fendt, Valtra and Massey Ferguson.
For catalysts, this structure could either speed up or slow down the PTx revenue and retrofit targets, the FarmerCore rollout and the cost efficiency program targeting more than US$200 million of savings. The operational test is whether Caspari and peers keep Fendt expansion, aftermarket growth and tariff cost management on track while volumes and regional demand remain under pressure.
AGCO's current analyst script points to revenue of US$12.2b and earnings of US$871.8m by 2029, built on a forecast 5.5% yearly top line growth rate and an earnings move of about US$338m from US$533.4m today to that 2029 consensus figure.
Uncover why AGCO's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
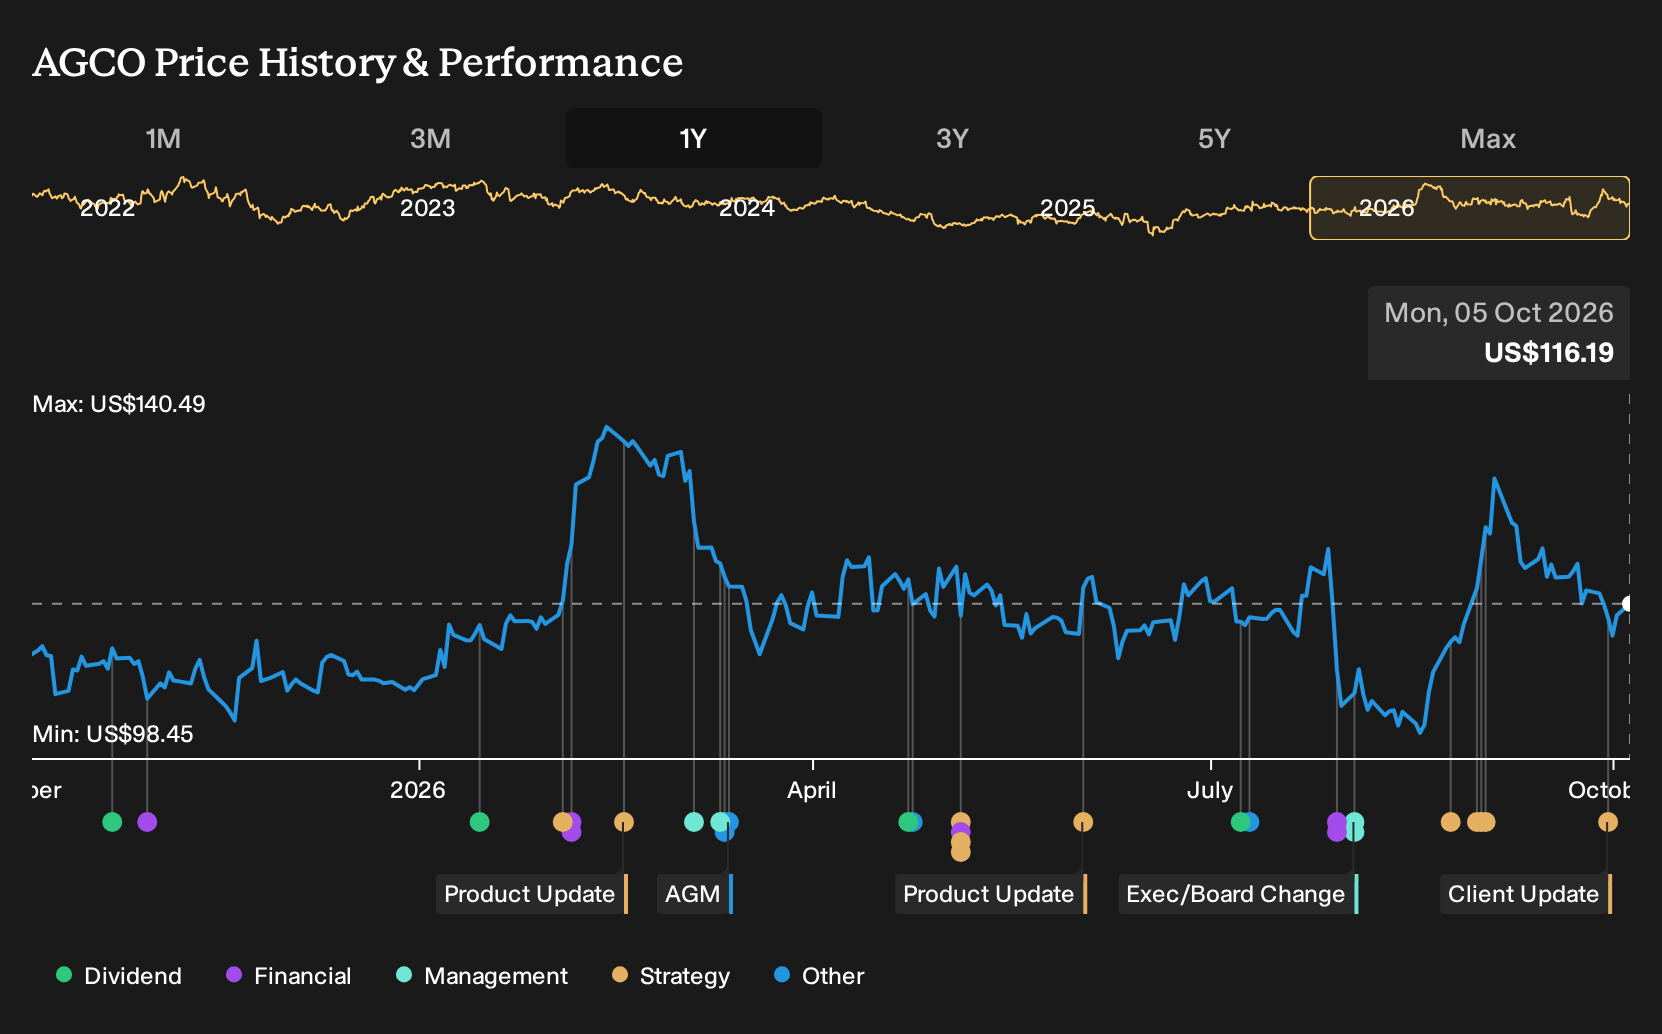
Exploring Other Perspectives
The bearish narrative focuses on concerns that AGCO’s precision ag push may not scale quickly enough to offset softer equipment cycles. Those analysts were pencilling in about US$11.2b of 2029 revenue and US$672.0m of earnings before this leadership shake up. That is well below consensus, so use this news to stress test several different forecasts.
Explore 3 other AGCO fair value estimates, including one that suggests as much as 14% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AGCO research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AGCO. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AGCO's overall financial health at a glance.
Looking For More Ideas Beyond AGCO?
If the AGCO story has you thinking about what else might fit your portfolio, it can help to line it up against other opportunities with different risk and return profiles.
- For investors hunting for high potential at lower share prices, scan through 9 elite penny stocks with strong financials that could sit on the riskier end of your watchlist but offer meaningful upside if the businesses execute well.
- If quality at a sensible entry point matters most to you, focus on 27 high quality undervalued stocks that combine stronger fundamentals with valuations that may leave some room for future price improvement.
- For those who care more about resilience and capital preservation, narrow in on 31 resilient stocks with low risk scores that score better on financial strength and business stability metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com