


EchoStar (ECHO) has drawn fresh attention after a recent share price move, rising 4.2% in the latest session and extending its gain to 9.3% over the past week on elevated trading interest.
The latest swing comes after a mixed stretch, with EchoStar’s share price return down 12.5% year to date, even as the 1 year total shareholder return sits at 30.6% and the 3 year total shareholder return is very large at roughly 7x. This points to momentum that has cooled recently but remains powerful over a longer horizon.
Capitalize on EchoStar's renewed momentum by scanning a curated set of 27 high quality undervalued stocks that also pair strong cash flows with resilient balance sheets.EchoStar now trades well below the average analyst target and sits above one intrinsic estimate, which raises a simple question: Is the recent jump closing a discount or reopening a valuation gap?
Most Popular Narrative: 25% Undervalued
EchoStar's most followed narrative pegs fair value at $131.44 versus the last close at $98.21, so the current move still sits well below that anchor and keeps the focus on what has to go right for that gap to narrow.
EchoStar's investment in a unique wideband LEO direct-to-device satellite constellation, leveraging its global S-band and AWS-4 spectrum rights, positions it to address skyrocketing global demand for ubiquitous connectivity across consumer, enterprise, government, and IoT applications. This is likely to create new, high-margin wholesale revenue streams and accelerate long-term revenue growth.
See why 25 investors see EchoStar as 25% undervalued.
That storyline uses an 11.49% discount rate and assumes EchoStar can move from a net loss of $5.7b to positive earnings over time, with margins eventually settling near 5.8% on revenue of about $13.1b according to the narrative inputs. It also implies the stock would trade on a future P/E of 71.6x, which is materially higher than the current figure cited for the broader US Media group in the same narrative.
For anyone weighing that framework, the key swing factors are clear. Execution on the LEO direct to device build, progress on monetizing spectrum, access to funding for roughly $5b of planned constellation spending, and the pace at which legacy Pay-TV and broadband revenues decline all feed directly into whether that fair value of $131.44 feels achievable or too optimistic relative to the present $98.21 share price.
Result: Fair Value of $131.44 (UNDERVALUED)
Still, the EchoStar story hinges on real pressure points, including declining Pay-TV and broadband revenue and heavy funding needs for the planned US$5b LEO build.
Find out about the key risks to this EchoStar narrative.
Another View on EchoStar’s Valuation
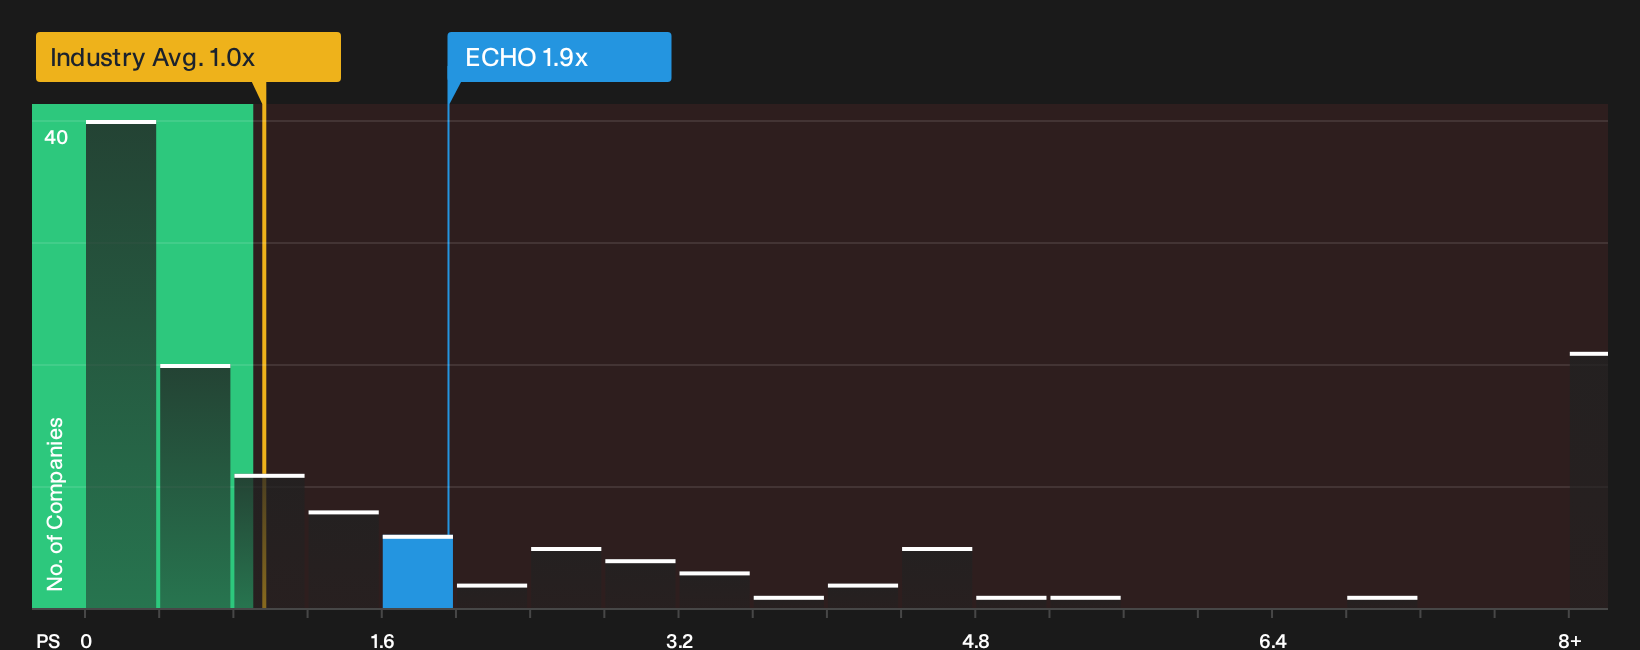
The fair value story for EchoStar looks very different when moving away from the narrative-based price target and toward simple sales multiples. On a P/S of 1.9x versus a peer average of 0.9x and a US Media group average of 1x, the stock screens as expensive and sits above a fair ratio of 1.3x that the market could move toward. That gap points less to a clear bargain and more to valuation risk that depends on how much confidence you place in future execution.
See what the numbers say about this price in our valuation breakdown, then compare EchoStar against other companies using similar checks See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around EchoStar's valuation can be confusing. Move quickly, review the underlying data, and weigh both the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond EchoStar?
If EchoStar has your attention, do not stop there. Broaden your watchlist with fresh ideas so you are not relying on a single storyline.
- Target potential mispricings by scanning a curated pool of companies that look attractively valued using our 27 high quality undervalued stocks.
- Balance return potential and resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can help you stay focused on financial strength when conditions change.
- Get ahead of the crowd by checking a focused set of 19 high quality undiscovered gems that combine quality fundamentals with lower investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com