


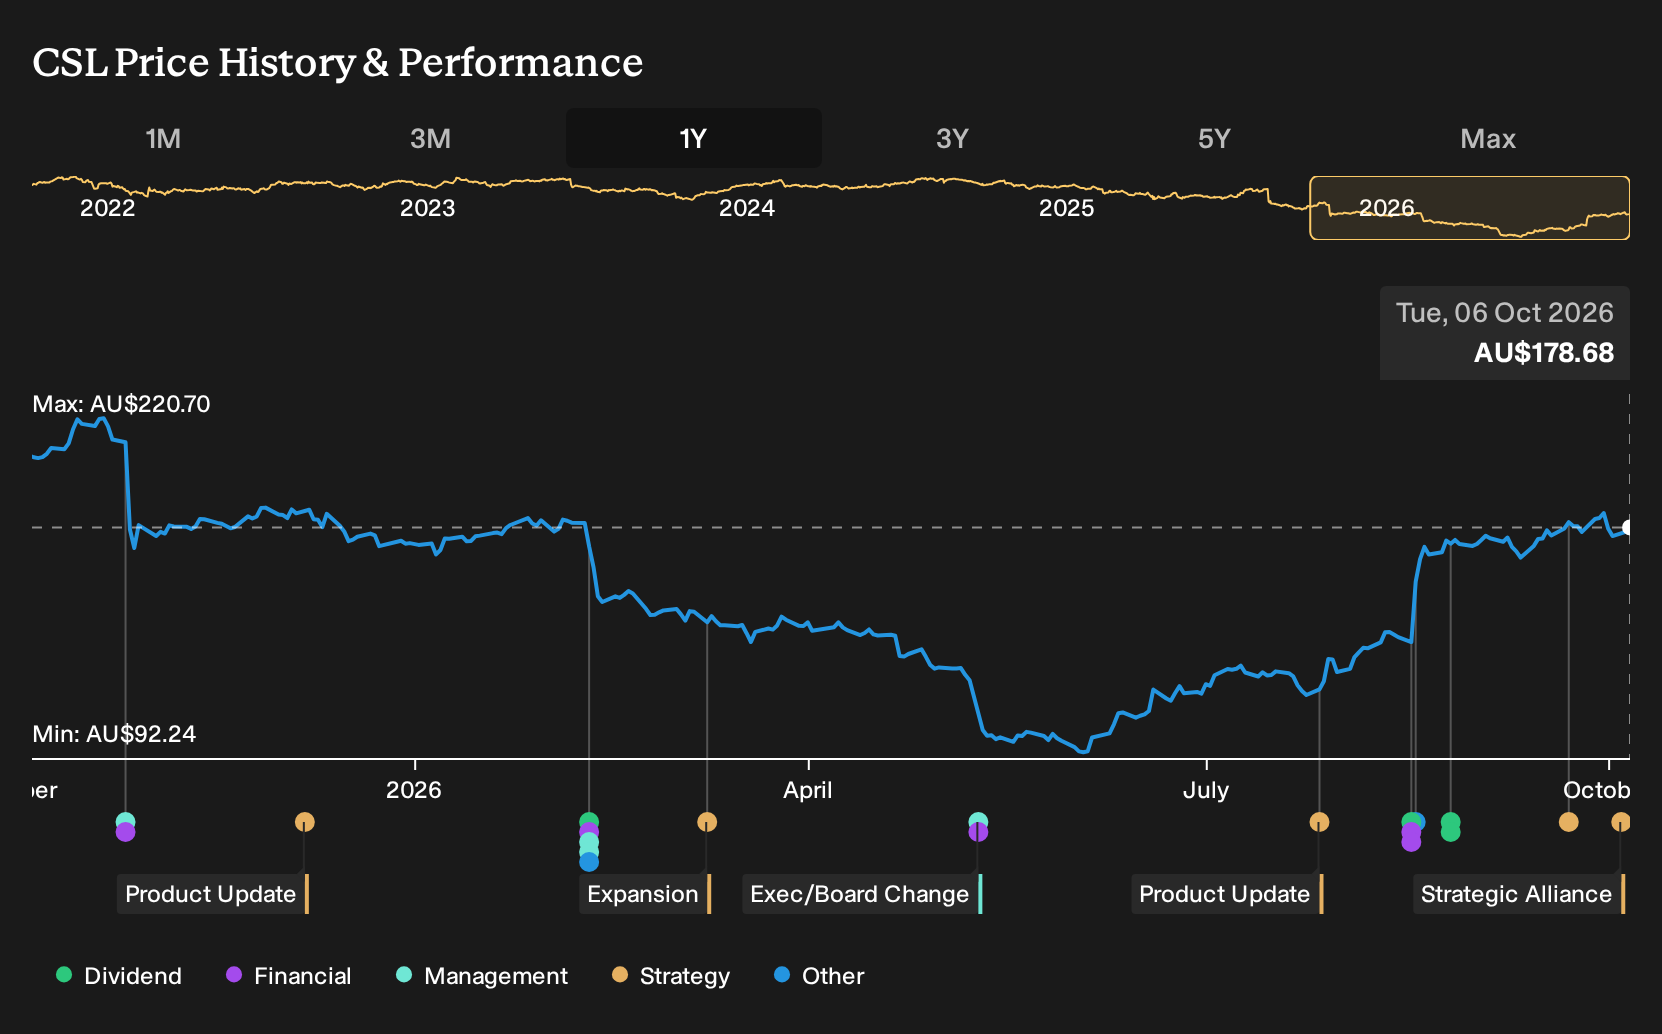
- CSL and Alentis Therapeutics recently agreed an exclusive global collaboration to co-develop and co-promote lixudebart for rare kidney and liver diseases, with CSL funding Phase 2 and Phase 3 programs and Alentis eligible for a US$355 million upfront payment plus up to US$1.2b in milestones and shared profits.
- The structure of the lixudebart deal, with CSL taking on full development funding and a 55% share of global profits, signals a clear commitment to expand its nephrology and rare disease portfolio through externally sourced science.
- Attention now turns to how CSL's investment narrative around pipeline productivity and margin improvement could be reshaped by this capital intensive lixudebart partnership.
Scan how CSL's lixudebart move compares with other rare disease opportunities by zeroing in on 15 high quality undiscovered gems already attracting attention from long-horizon investors.
CSL Investment Narrative Recap
To own CSL, you need to believe in a large, global rare disease and plasma franchise that can convert an extensive pipeline into future cash flow while managing high R&D and restructuring costs. The lixudebart deal fits that story, but it also raises the bar for clinical execution and capital discipline because CSL is taking on full development funding.
The near term focus still centers on whether new therapies and ongoing cost initiatives can move CSL from loss making into sustained profitability while offsetting pricing pressure in plasma and iron therapies. The biggest risk remains slower uptake or setbacks across key launches and late stage programs, and this new agreement adds more pipeline delivery risk rather than removing it.
The collaboration with Alentis on lixudebart is the most relevant recent announcement for you here. It shows CSL leaning further into nephrology and rare liver diseases, in addition to the existing Vifor platform. The structure, with CSL receiving 55% of global profits and funding Phase 2 and Phase 3 programs, concentrates both upside and execution risk on CSL's side of the ledger.
For catalysts, lixudebart now sits alongside products like ANDEMBRY and HEMGENIX in determining whether CSL can shift from forecast earnings growth on paper to realised returns in financial statements. Any delay, weaker than expected trial readout or reimbursement friction on these therapies would weigh on the margin improvement story, especially given CSL's high debt levels and ongoing restructuring commitments.
CSL's current analyst storyline points to revenues of $17.0b and earnings of $3.4b by 2029, built on an assumed 2.6% yearly increase in sales and a swing in earnings of about $6.0b from a loss of $2.6b today to that $3.4b profit level.
Uncover why CSL's fair value indicates a 3% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One big swing factor the most optimistic CSL analysts were watching before this lixudebart deal was margin recovery. Their models pointed to revenue of about $17.8b and earnings near $3.9b by 2029. That is far more upbeat than consensus and could easily be revised again as this kidney and liver partnership is digested.
Explore 7 other CSL fair value estimates, including one that indicates there could be as much as 18% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CSL research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CSL. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CSL's overall financial health at a glance.
Looking For More Ideas Beyond CSL?
Once you have formed a view on CSL, it can help to place that thesis alongside other opportunities that fit different risk and income profiles. The Simply Wall St screener lets you filter by quality, balance sheet strength, dividends and more, so you can build a watchlist that matches how you prefer to invest.
- For investors who want resilience to be front and center, start with a 7 resilient stocks with low risk scores that already clear tougher quality and risk filters than the broader market.
- If you care most about getting paid while you wait, scan a focused group of 3 dividend fortresses that combine income with balance sheet support for those payouts.
- Readers looking for financially sound operators with room to grow can widen the search with a list of solid balance sheet and fundamentals (12 results) that may complement or contrast with a position in CSL.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com