


Vistar Media’s new digital out of home audience segments, powered exclusively by T-Mobile US (TMUS) carrier data, push the telecom deeper into advertising. Investors now have fresh information about how T-Mobile is monetizing its network data.
T-Mobile US has been active on multiple fronts, from carrier data partnerships with Vistar Media to a joint venture with AT&T and Verizon aimed at reducing coverage dead zones, as well as new AI-powered network tools and a higher quarterly dividend.
Despite that stream of announcements, the 30-day share price return is down 9.3% and the year-to-date share price return is down 17.5%, while the 3-year total shareholder return of 21.59% and 5-year total shareholder return of 48.91% indicate that momentum has cooled after a stronger multi-year run.
Spot fresh ideas with similar telecom and data monetization angles by scanning our hand picked list of solid balance sheet and fundamentals (25 results).The recent slide in T-Mobile US, after years of stronger multiyear returns, leaves investors weighing whether this is about the business fundamentals or a swing in sentiment, which is where valuation work starts to matter.
Most Popular Narrative: 32% Undervalued
T-Mobile US closed at $164.64, while the most followed narrative pegs fair value at $243.38. The gap now comes down to whether the long term broadband and cash flow story holds up under scrutiny.
Continued expansion of T-Mobile US 5G broadband and fiber offerings, with higher 2030 broadband targets and early fiber joint venture penetration around 20% in year one, points to further room for service revenue growth as the broadband base scales.
See why 119 investors see T-Mobile US as 32% undervalued.
Result: Fair Value of $243.38 (UNDERVALUED)
Still, the T-Mobile US story can break if higher bills from rate plan changes push churn up, or if heavier device promotions squeeze margins and cash flow.
Find out about the key risks to this T-Mobile US narrative.
Another Angle On T-Mobile US Valuation
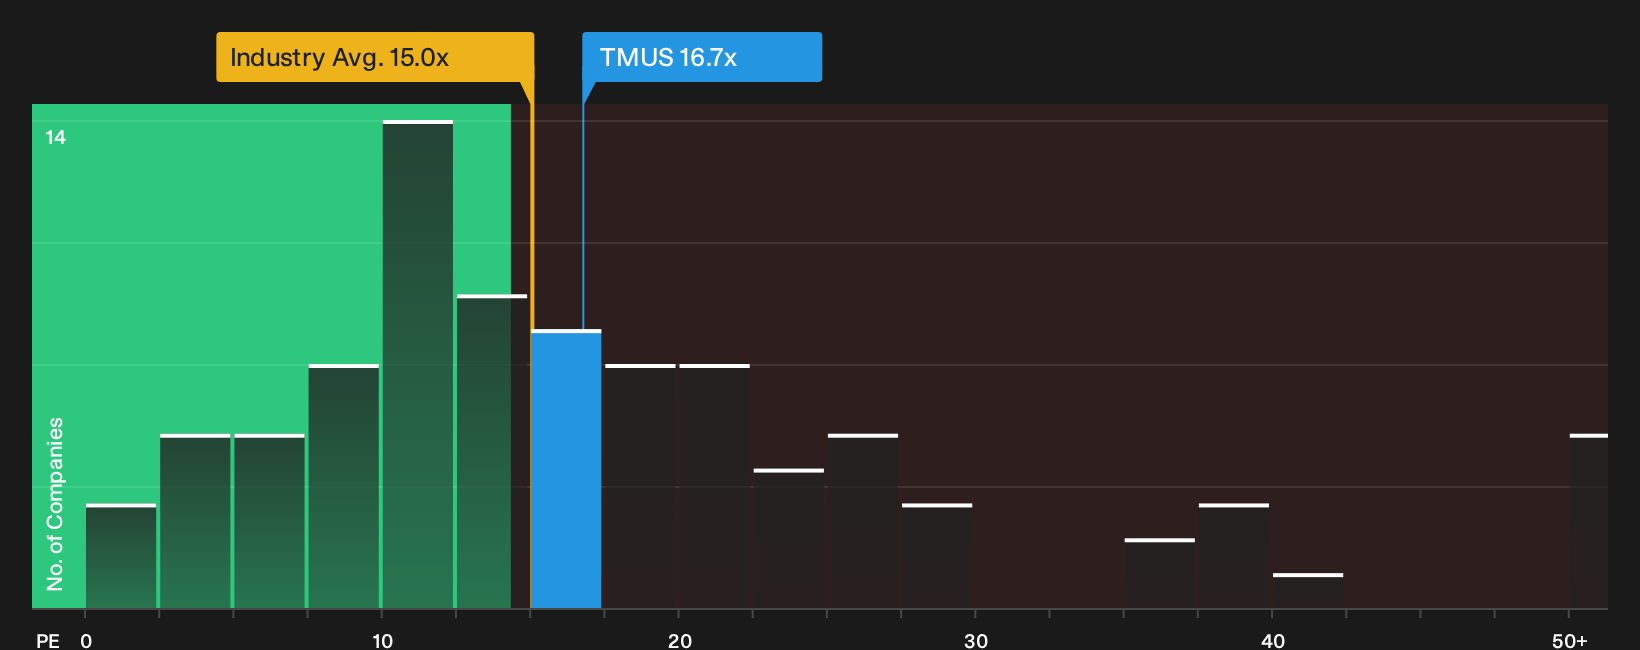
The earlier view leaned on T-Mobile US fair value of $243.38. On simple P/E math, the picture is less clear cut. TMUS trades on 16.7x earnings compared with a 15x industry average, yet the fair ratio sits higher at 20.1x, which hints at valuation risk if the market aligns more closely with peers, or potential opportunity if it moves toward that fair ratio.
This raises a practical question for investors. Does a premium to the sector and a discount to the fair ratio look like a margin of safety, or a sign that expectations already do a lot of heavy lifting for T-Mobile US.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals across T-Mobile US valuation and sentiment only matter if you pressure test them yourself. Move quickly, look at both sides of this setup, then weigh the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond T-Mobile US?
If T-Mobile US has you rethinking your watchlist, this is the moment to widen the lens and hunt for other compelling setups using the Simply Wall St Screener.
Skip the noise and lean on filters that surface quality, price and resilience instead of hype driven stories that rarely hold up under real scrutiny.
- Target quality at a discount by scanning a curated batch of resilient companies that also look attractively priced through the 27 high quality undervalued stocks.
- Lock in potential portfolio stabilisers by reviewing a focused collection of income ideas through the 7 dividend fortresses.
- Dial down risk without giving up discipline by searching for financially robust businesses using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com