


A repurchase plan of up to HK$320 million was announced in July. After intensive repurchases in September, the stock price did not rise but fell. Was Goldway Electronics (01415) mistakenly killed by the market?
The Zhitong Finance App learned that on July 13, Gao Wei Electronics authorized and approved a share repurchase plan of up to HK$320 million. The acquisition began on August 19. As of October 2, it had repurchased 4.61 million shares, with a total repurchase amount of over HK$100 million. Boosted by buybacks, the company's stock price rose 23% in August, but began falling by more than 11% in September. This year, the market value pulled back 18%, and the high point since September 2025 is close to falling short.
However, the company's performance grew strongly. In the first half of 2026, revenue and profit continued to grow in double digits. On the one hand, there was a tug-of-war where more and more purchases fell, and repurchases couldn't stop the decline in valuations. On the other hand, there was a questionnaire on which side of the mid-report revenue and profit increased. Which side did Gao Wei Electronics' valuation balance lean on?
Double growth amidst headwinds, low profit margins but high ROE
Gaowei Electronics is a supplier of precision optical modules. Its customers cover the fields of smartphones, multimedia tablets, intelligent driving and other mobile terminal devices. It is also a core supplier of Apple. At the same time, its performance is highly dependent on Apple. In the first half of this year, the industry as a whole was still adjusting, but Apple's sales bucked the trend.
According to IDC data, global smartphone shipments declined overall, falling 4.1% in the first quarter and 6.7% in the second quarter, while Apple shipments increased by 3.3% and 15.3% respectively, reaching 20% in the global market share, ranking second. Among them, the Chinese market made a core contribution, growing as high as 24.9% in Q2. Benefiting from the increase in Apple's performance, Gaowei Electronics also went against the wind and surrendered double growth. In the first half of the year, it achieved revenue of 1.605 billion US dollars, an increase of 18% over the previous year, and shareholders' net profit of about 90 million US dollars, an increase of 33.3% over the previous year.
In the first half of the year, Gaowei Electronics' largest customer (Apple) contributed 1,593 million US dollars in revenue, up 19.4% year on year, and its share of revenue increased to 99.3%. Among them, the Chinese market contributed the most, contributing 1.48 billion US dollars in revenue, up 20.3% year on year, and its share of revenue increased to 92.2%. Looking at the extended cycle, Gaowei Electronics is highly sensitive to Apple's performance cycle. In 2023-2025, both revenue and profit maintained a high growth trend. The compound revenue growth rate was 94.6%, and the compound growth rate of shareholders' net profit was 105.6%.
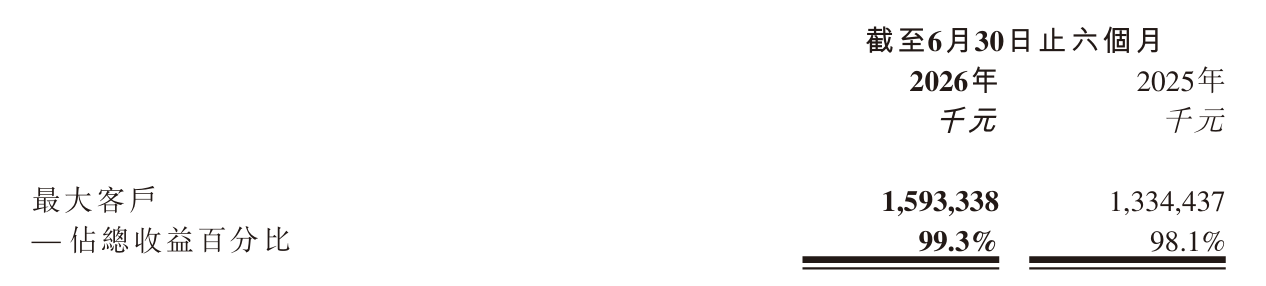
Photo Source: Company Financial Report
Profit growth outperformed revenue, mainly due to the continued release of operating leverage. The foundry attributes of Gaowei Electronics mean that the profit margin will not be too high, but the return on shareholders is not low. The gross profit margin for the first half of the year was 11.22%, which is relatively stable compared to previous years, but the expenses for the period, including sales, administrative and financing expenses, were optimized. The fee ratio for the first half of the year was 4.99%, down 0.9 percentage points from the previous year. The net shareholder interest rate was 5.6%, an increase of 0.7 percentage points, and the annualized ROE reached 22.3%.
Growth is expected, but the bottom is still not over
Apple is the basic platform of Gaowei Electronics, and its high dependence is both a risk and a guarantee. The company is deeply involved in many new Apple categories and is expected to grow. In the first half of the year, Apple sales bucked the trend and made the company's demand strong. Q3 Apple's sales in China continued to grow 0.6%. New Q4 products drove sales to continue to be strong, and sales volume may provide the company with strong orders throughout the year. Furthermore, in the medium to long term, Apple is expected to release new categories such as folding machines, 20th anniversary phones, AI headsets, AI glasses, and home robots in 2026-2027, which also guarantees growth for Gaowei Electronics.
Being highly dependent is always risky. The company actively opens up a second growth curve, lays out microLED-related optical technology, explores innovative application opportunities in optical communication, AR, etc., and forwardly lays out new robotics businesses with its deep accumulation in the field of optical high-precision optical sensing products. Furthermore, the company closely follows the AI development trend and promotes the deep extension of artificial intelligence technology from “product empowerment” to “system empowerment” to achieve a dual-drive pattern of basic market+new growth curve. However, at present, the new growth curve has not taken shape and has not yet driven performance.
However, one of the company's greatest strengths is its clean finances and abundant cash resources, which allows the company to resist cyclical risks and achieve pro-cyclical and new business expansion. As of June 2026, the company had mobile bank loans of US$134 million and non-current bank loans of US$08 billion, totaling US$142 million, accounting for only 9.37% of total assets, while cash equivalents had US$404 million, which is 2.85 times the interest-bearing debt.
It is worth noting that Apple is the biggest variable in Gaowei Electronics' performance growth, but the market capitalization growth trend is inconsistent. In the last three years, Apple's market value has continued to rise, while Gaowei Electronics has declined at a high level, driven by distortions in fundamentals, and entered a technical bear market. After the valuation was drastically withdrawn, the company's PE (TTM) was only 11 times, while the PE value of the Hong Kong stock mobile phone industry chain was 24 times higher. The company was far below the industry level.
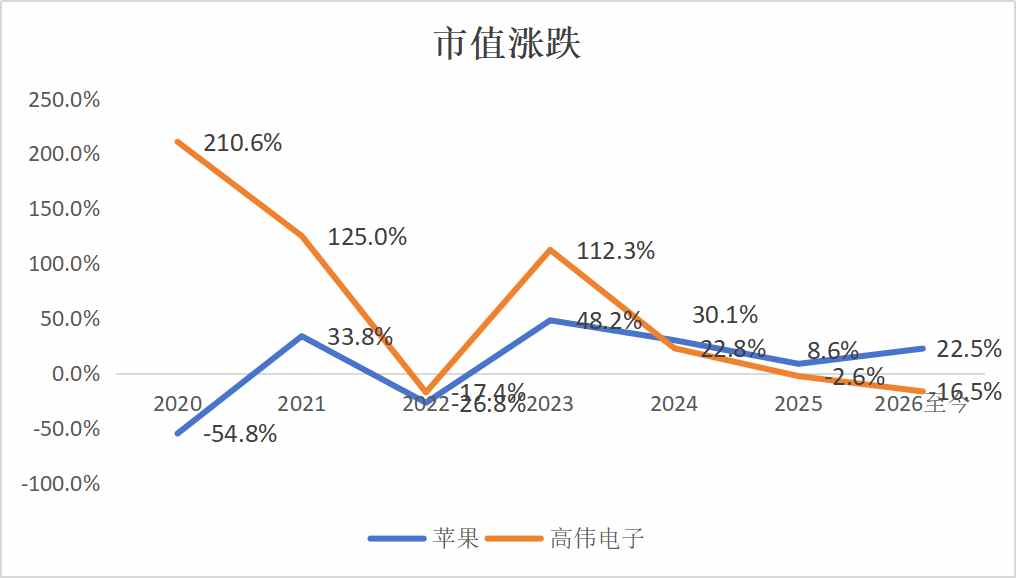
Data source: Related trading software
Why is the market value and performance of Gaowei Electronics at odds? There are three main reasons: first, smartphone shipments continue to decline. Although AI is driving the growth in high-end phone sales, structural adjustments have not effectively prevented the industry from entering a period of decline; second, the new growth curve is unformed, and expectations are not high, causing the market to be consistent with the expectations of the mobile phone industry, and sensitivity to Apple's performance is average; third, even though the market value has declined sharply, under the long-term bullish trend, there are still many profit margins. Coupled with the suppression of fixed accounts, popular capital is not in the mobile phone sector, causing valuations to continue to bottom out.
To boost market confidence, the company issued a “share repurchase plus equity incentive” to buy back its own shares at a total cost of no more than HK$320 million, and granted 129.29 million bonus shares to 181 directors and employees, accounting for 1.49% of the issued shares, of which 4 directors accounted for 0.21%. The company's valuation mainly lacks a driving factor. Repurchase the underlying share price, and equity incentives are highly tied to performance targets. If the new growth curve is effective, the valuation will also usher in an inflection point.
From the perspective of brokerage investment banks, Everbright Securities believes that the AI-driven optical innovation cycle has a clear medium- to long-term growth path, and is optimistic about the company's continued growth under the mobile phone optical upgrade trend and huge space to expand into the new blue ocean market such as AI glasses and robots. J.P. Morgan Chase Research reports that Gao Wei benefited from better orders for Apple products than expected and improved yield efficiency, and the net profit growth in the first half of the year was higher than expected. Currently, the stock price is only equivalent to the price-earnings ratio predicted in 2026, 40% lower than the historical average. It is expected that strong profit growth will support critical evaluation, and the target price increase will be 48 to 48 to support critical evaluation. Hong Kong dollars.
Taken together, Gaowei Electronics' performance has maintained strong growth, but valuations have diverged. The retracted from a high level in the past year. Releasing repurchases and equity incentives this year boosted confidence. Most investment banks are optimistic about raising target prices but have not changed the downward trend. Three major reasons have caused the company's valuation to be mistaken by the market. However, the company is supported by fundamentals and depends on Apple's growth expectations, but the buyback continues, the bottoming out is not over, and the inflection point in valuation is left to be verified in the next financial report.