


KLA Corporation has delivered very strong returns in recent years, which naturally puts the spotlight on whether the current share price lines up with what its earnings can support. With the stock now reflecting years of optimism, the question for investors is how those profits stack up against a more grounded view of value.
- KLA has returned roughly 580% over the past 5 years, so a lot of future earnings strength may already be reflected in the share price.
- Recent company updates point to higher expected revenue and earnings, which can support a case for stronger profit power but also raise the bar for what its income statement needs to deliver.
- Your read on KLA is one view; the desks covering it have another. See what analysts think KLA's shares could be worth.
The issue now is whether KLA's current valuation is justified by its earnings when set against a Fair Ratio benchmark.
If you want a broader starting point while you weigh KLA's earnings against its price, a focused stock screen can help surface other ideas that fit clear criteria such as 27 high quality undervalued stocks.
Does KLA Look Pricey on Earnings?
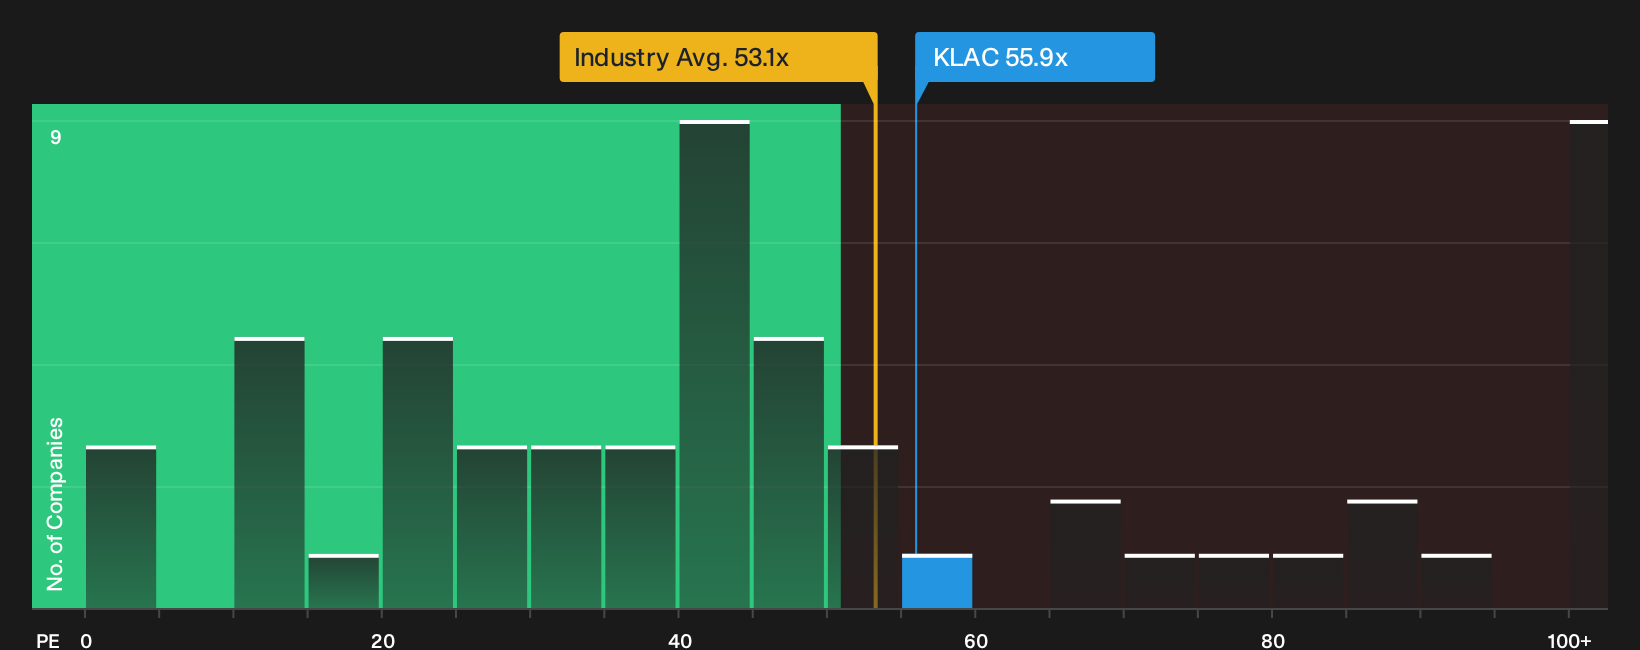
For a mature, highly profitable chip-equipment specialist like KLA, the P/E ratio is a useful shorthand for how much investors pay for each dollar of earnings. KLA currently trades on a P/E of 55.9x, which is slightly above the Semiconductor sector average of 53.1x and broadly in line with the 53.3x peer group level. That puts the stock toward the richer end of the sector, but not in a completely separate tier from comparable businesses.
On a more tailored yardstick that adjusts for KLA's growth profile, margins, size and risk, the Fair Ratio sits below the current P/E. This points to the shares looking overvalued on this framework. Because the company recently raised revenue and earnings guidance for fiscal 2027, the market may be leaning into that stronger outlook and accepting a higher multiple than the Fair Ratio suggests. You would need to decide whether that extra optimism is justified by KLA's earnings power over the long run or whether the current P/E already builds in more good news than feels comfortable. Explore the numbers behind KLA's P/E valuation.
The KLA Narrative: What Would Justify Today's Price?
Narratives for KLA pick up where the valuation puzzle leaves off. They spell out which paths for future growth, profitability and earnings would need to play out for the stock to be worth materially more or less than it is today. These narratives sit on Simply Wall St's Community page as structured viewpoints that treat KLA's fair value as a thesis about the business you can revisit over time, rather than a one off snapshot.
Community views on KLA split between those who see the backlog as underappreciated and those who worry external risks could weigh on the premium multiple.
Bull case: 12% undervalued
"The current valuation implies the share price does not fully reflect KLA’s record revenue and free cash flow, its very high process control market leadership, or the scale of multi year AI and advanced packaging driven growth that management now targets…"
Discover why this Narrative puts KLA at 12% undervalued.
Bear case: 18% overvalued
"Ongoing and intensifying US-China trade tensions, compounded by unpredictable global tariff regimes and new export controls, are increasingly limiting KLA's access to the critical Chinese semiconductor market…"
Explore why this Narrative puts KLA at 18% overvalued.
Before you move on from KLA, one more check deserves a closer look
Valuation only tells part of the KLA story, as Simply Wall St's broader review has also highlighted specific risk checks that could change how you frame the whole thesis. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com