


Scholar Rock Holding (SRRK) has drawn attention after its shares closed at US$43.40. The biopharma specialist is now valued at about US$5.29b and carries a value score of 3.
Recent trading has been choppy for Scholar Rock Holding, with the share price falling 7.3% over the last day, 21.6% over the past month and 22.5% across 90 days. However, the 1-year total shareholder return of 9.9% and a very large 3-year total shareholder return hint that longer term momentum has been strong.
Scan beyond Scholar Rock Holding and see how it stacks up beside 19 high quality undiscovered gems targeting rare disease and specialist biotech opportunities.
Scholar Rock Holding now trades at a steep discount to analyst targets and an implied fair value, even after the recent slide. Is this caution about loss-making rare disease biotech work in progress, or an overreaction to short term volatility?
Most Popular Narrative: 38% Undervalued
Scholar Rock Holding’s most followed narrative points to a fair value of $70.44 against the last close of $43.40. This frames the current price as a sizeable discount built on aggressive growth and margin assumptions that investors need to test for themselves.
Scholar Rock Holding focuses on developing muscle-targeted therapies for rare and severe neuromuscular diseases, led by its apitegromab program for spinal muscular atrophy and a broader anti myostatin pipeline.
Scholar Rock’s strengthening of its commercial and supply infrastructure, including a 50 country operating build out, a second fill finish facility and a large home infusion and specialty pharmacy network, is aimed at supporting broad access and could influence both revenue scale and net margins as fixed launch investments are spread over a larger sales base.
See why 1 investors see Scholar Rock Holding as 38% undervalued.
Result: Fair Value of $70.44 (UNDERVALUED)
Still, the whole Scholar Rock Holding story hinges on smooth ISEMBYLD uptake and timely FDA manufacturing sign off, and any stumble there could quickly challenge this 38% undervalued narrative.
Find out about the key risks to this Scholar Rock Holding narrative.
Another View: Scholar Rock Holding Looks Expensive On P/B
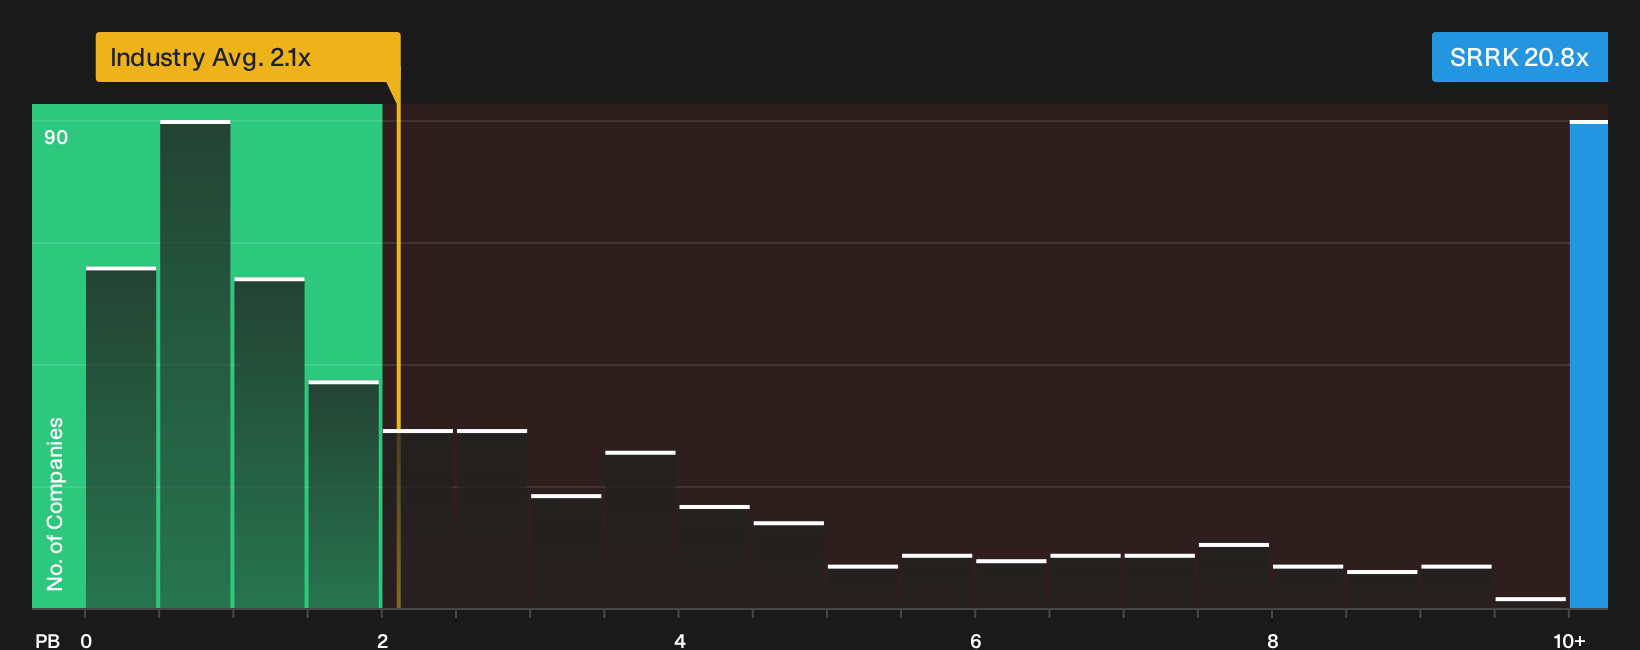
That 38% discount to fair value sits awkwardly beside Scholar Rock Holding’s current P/B of 20.8x. The stock trades well above both US Biotechs at 2.1x and direct peers at 7.2x, which points to rich expectations and less room for error if the launch plan or pipeline timing slips.
For investors trying to reconcile a discounted cash flow upside case with such a stretched book value multiple, the real question is which signal deserves more weight as new data and revenue start to appear.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Scholar Rock Holding can be useful, but they only matter if you test them against the raw numbers and recent filings yourself, then carefully evaluate both the upside potential and downside protection using the 3 key rewards and 3 important warning signs.
Looking for more Scholar Rock Holding investment ideas?
If Scholar Rock Holding is on your radar, do not stop here. Fresh ideas often come from comparing it with other stocks filtered through clear rules.
- Target stronger potential risk and reward trade offs by scanning through 27 high quality undervalued stocks that combine quality fundamentals with prices that still trail underlying metrics.
- Protect your downside first by reviewing 31 resilient stocks with low risk scores that screen for sturdier balance sheets and steadier risk profiles.
- Get ahead of the crowd by checking 9 elite penny stocks with strong financials that pass tougher filters on financial strength instead of just chasing the lowest share price.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com