


Ingredion (INGR) has drawn investor attention after recent share price moves left the stock down about 4% over the past month and roughly 2% over the past 3 months. This pullback frames the current valuation conversation.
Over the past year, Ingredion’s share price return has declined in the double digits, while the 1-year total shareholder return is also down. However, the 3-year and 5-year total shareholder returns remain positive, signaling that recent momentum has cooled compared with the longer-term record.
Scan beyond Ingredion and spot other potential value laggards or quiet compounders in our curated list of 27 high quality undervalued stocks that share solid fundamentals with recent share price pressure.
Ingredion’s recent slide and still positive multi year record leave the stock in an awkward middle ground. Does that mix of pressure and resilience still tilt the risk reward balance toward buyers at today’s price, or not?
Most Popular Narrative: 10% Overvalued
Against a last close of $96.85, the most followed narrative on Ingredion puts fair value at $88.23. This frames the current pullback as only partially closing the perceived gap between price and fundamentals.
The acquisition of Tate & Lyle has the potential to transform Ingredion from a predominantly commodity-oriented starch and sweetener processor into a more global specialty ingredients platform. The primary upside comes from mix shift toward higher-margin functional ingredients, meaningful cross-selling opportunities with global CPG customers, and scale-driven cost synergies.
See why 8 investors see Ingredion as 10% overvalued.
Result: Fair Value of $88.23 (OVERVALUED)
Still, Ingredion’s thesis depends heavily on smooth Tate & Lyle integration and sustained specialty mix progress; any stumble there could compress margins and investor confidence quickly.
Find out about the key risks to this Ingredion narrative.
Another View: Ingredion’s Earnings Multiple Paints A Different Picture
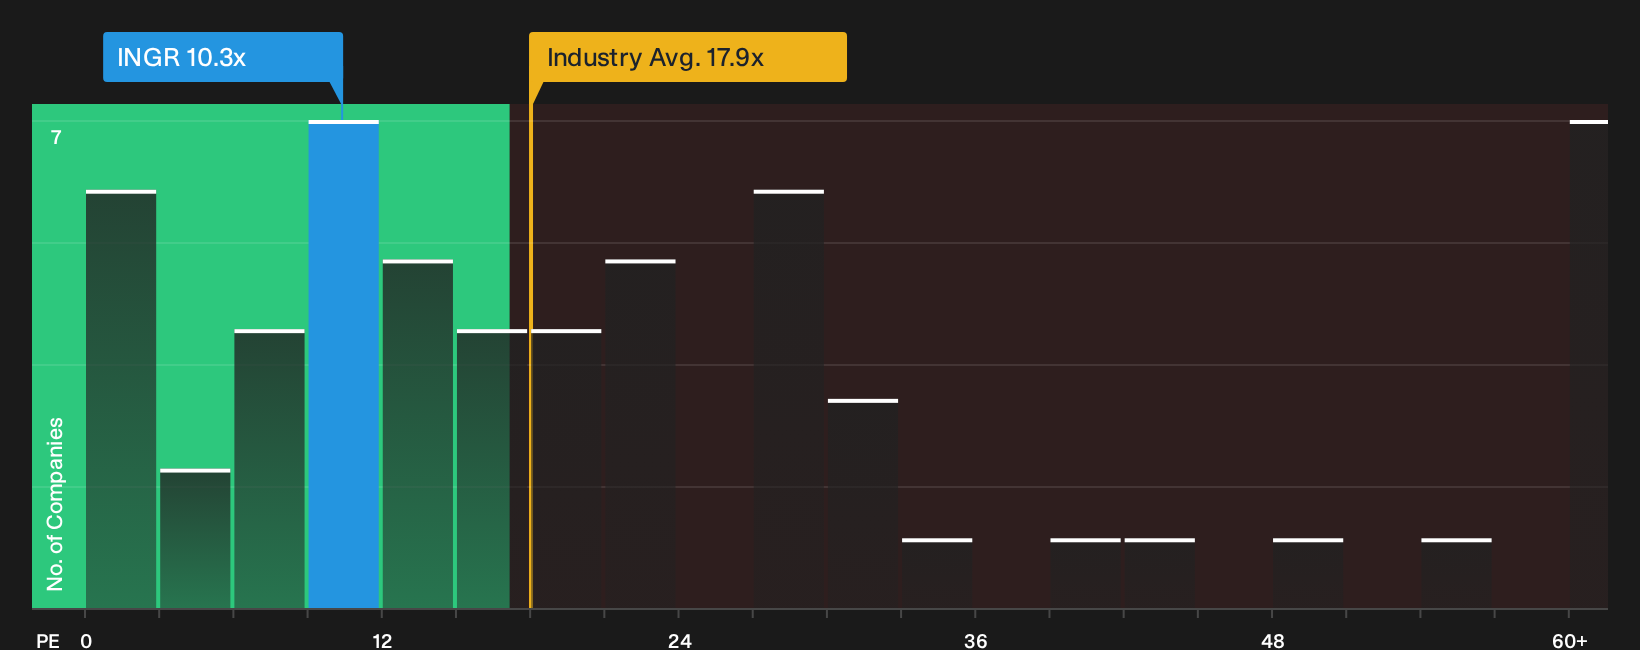
The narrative pegs Ingredion as about 10% overvalued at a fair value of $88.23 versus the current $96.85. The market’s own yardstick tells a different story. INGR trades on a P/E of 10.3x, while the US Food industry averages 17.9x and peers sit near 25.2x.
The fair ratio for Ingredion’s earnings multiple is 16.5x. If sentiment moved closer to that level instead of today’s 10.3x, the re-rating would close a sizable gap that currently prices the stock more like a slow, challenged business than one with growing earnings and high quality profit. Which lens do you trust more when those signals clash?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like these only matter if you weigh the evidence yourself and move before sentiment swings again. To see what investors are optimistic about, review the 5 key rewards.
Looking for more Ingredion-sized investment ideas?
Do not stop your work with Ingredion alone. Broaden your watchlist with a few focused stock pools that could surface opportunities before the crowd catches up.
- Target potential mispricings by scanning a curated pool of businesses with solid fundamentals using our 27 high quality undervalued stocks.
- Prioritize stability and income by reviewing companies built around reliable payouts with the 7 dividend fortresses.
- Focus on resilience first by filtering for companies screened for financial strength in the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com