


Valued at $11.9 billion by market cap, Hasbro, Inc. (HAS) is a powerhouse in the global toy and gaming industry, with an iconic portfolio that includes Magic: The Gathering, Play-Doh, Nerf, Transformers, Dungeons & Dragons, and Peppa Pig. Beyond traditional toys, the Rhode Island-based company also taps into the booming gaming and entertainment markets through its interactive software, tabletop games, puzzles, and licensed franchises.
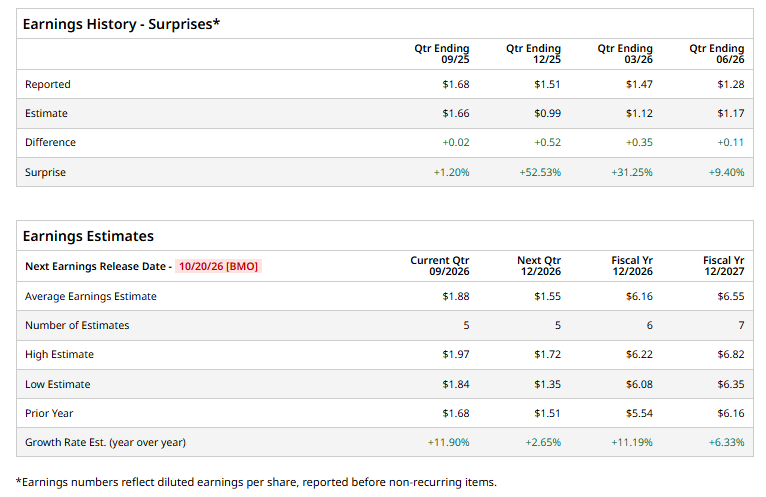
The toy giant is gearing up to release its fiscal third-quarter earnings for 2026 before the market opens on Tuesday, Oct. 20. Ahead of the event, analysts expect HAS to report a profit of $1.88 per share on a diluted basis, up 11.9% from $1.68 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the current year, analysts expect HAS to report EPS of $6.16, up 11.2% from $5.54 in fiscal 2025. Its EPS is expected to rise 6.3% year over year to $6.55 in fiscal 2027.
Hasbro has delivered a strong run over the past year, with HAS shares climbing 21.7% over the past 52 weeks. That performance comfortably outpaced the S&P 500 Index’s ($SPX) 15.8% gains and stood in stark contrast to the 7.2% decline in the State Street Consumer Discretionary Select Sector SPDR ETF’s (XLY) over the same period.
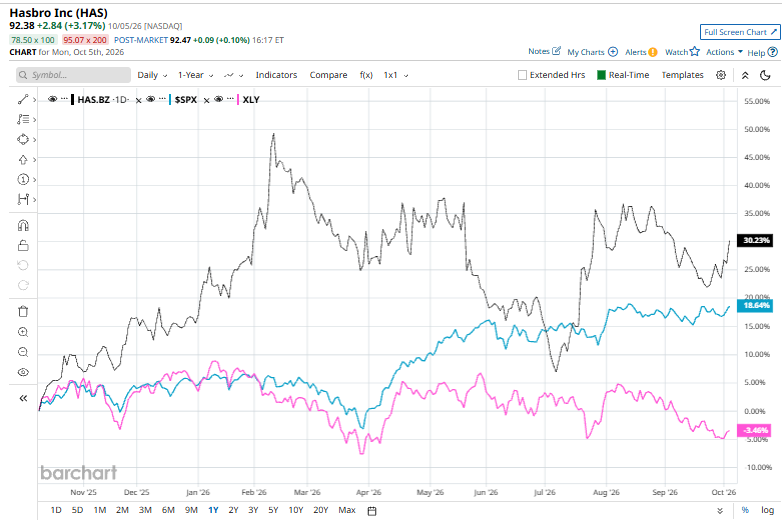
Hasbro has outpaced the broader market over the past year as investors have responded to strong growth in its higher-margin gaming and intellectual property businesses, particularly Wizards of the Coast. Magic: The Gathering has been a major growth engine, while Hasbro’s cost-cutting efforts and favorable business mix have lifted profitability.
Analysts’ consensus opinion on HAS stock is very bullish, with a “Strong Buy” rating overall. Out of 13 analysts covering the stock, 11 advise a “Strong Buy” rating, and two give a “Hold.” HAS’ average analyst price target is $109.69, indicating a notable potential upside of 18.7% from the current levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.