


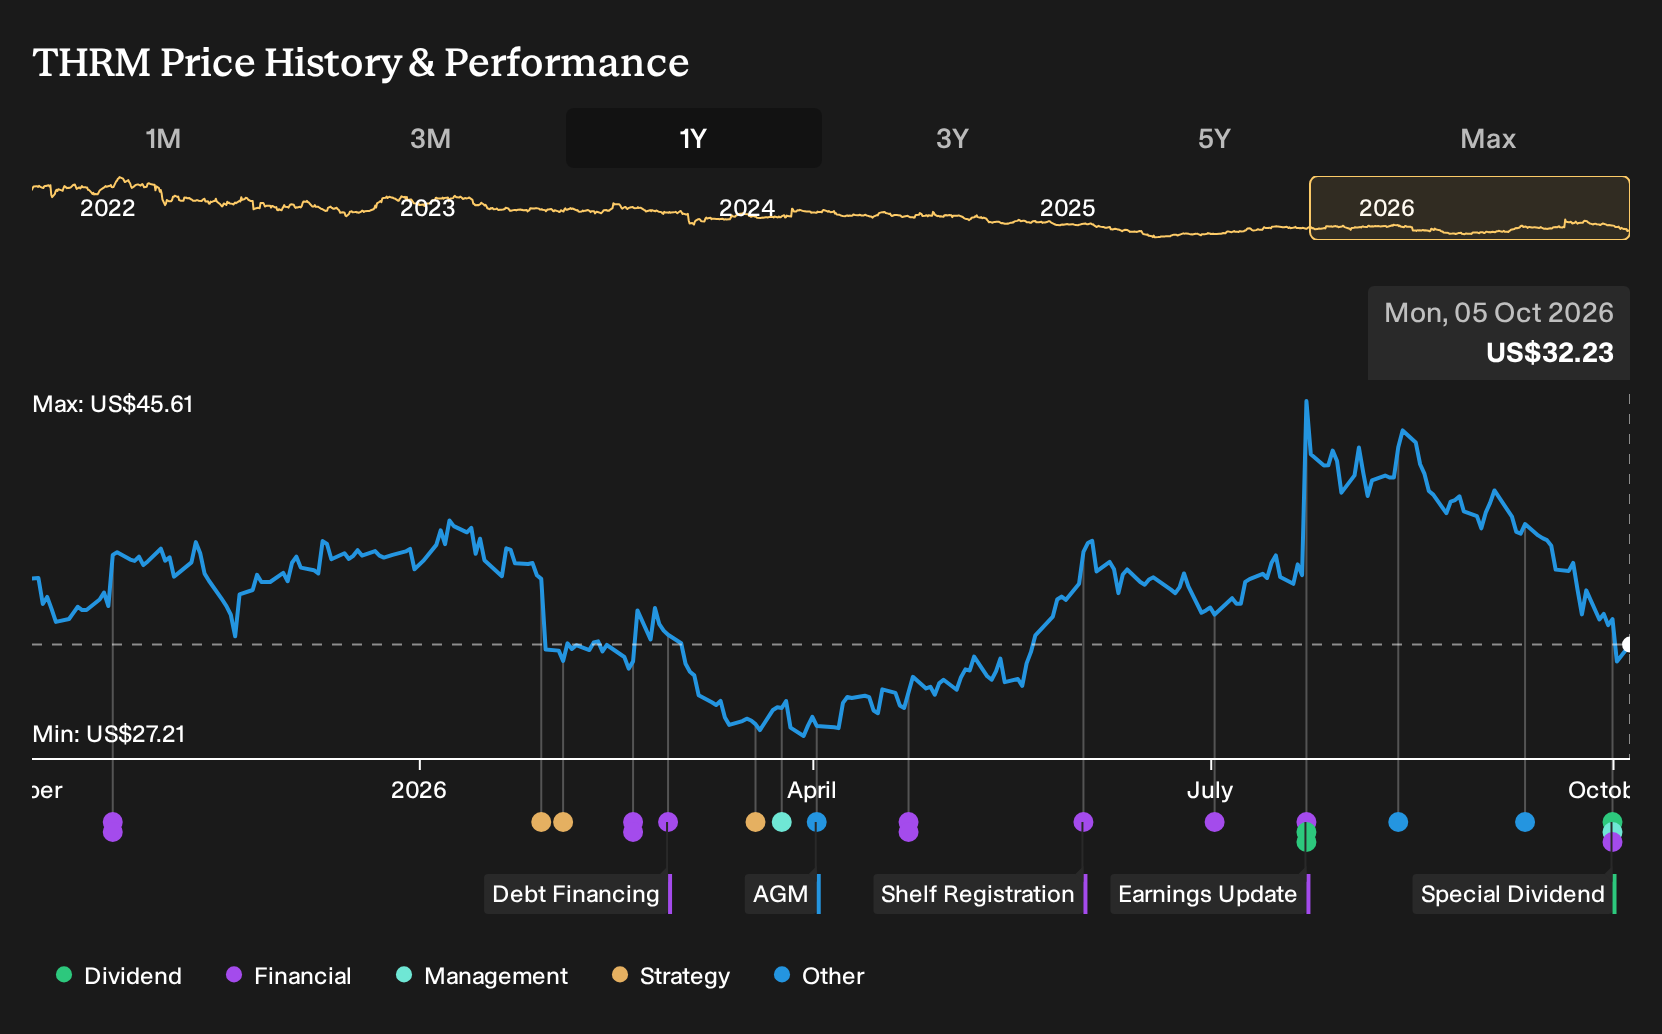
- Gentherm has already declared a special cash dividend of US$2.07 per share, totaling US$63,500,492, payable on October 7, 2026 to shareholders of record on September 28, 2026. The company has also added former Ford CTO Paul Mascarenas to its Board and Technology Committee and named Katrin Schatz interim head of the Modine Performance Technologies division.
- The one time dividend and fresh board and leadership additions highlight Gentherm's capital allocation priorities and operational focus as it integrates Modine Performance Technologies and refines its technology roadmap.
- The impact of this special dividend return of cash to shareholders on Gentherm's consensus investment narrative remains to be seen.
Gentherm Investment Narrative Recap
To hold Gentherm, you need to believe its thermal and comfort technologies can keep winning content on high volume vehicle platforms while the medical and adjacent businesses scale from a small base. In the near term, the key swing factor remains execution on margins, given recent profit pressure and the impact of one off items on reported earnings quality.
The biggest operational risk still sits in concentrated auto customers and weaker exposure in Asia, especially China, where the company already flags underrepresentation. The special dividend and leadership tweaks do not fundamentally change those near term drivers, so your focus probably stays on order flow, pricing, and cost control.
The most relevant update here is Paul Mascarenas joining Gentherm's board and Technology Committee. His long Ford background in engineering and technology, plus current roles at ON Semiconductor and Neo Performance Materials, aligns directly with Gentherm's push to increase content per vehicle through comfort, wellness, and electronics heavy solutions.
For you, the question is whether this strengthens execution on product roadmaps that support the existing catalysts, ranging from comfort features on mainstream platforms to new adjacent markets. Greater board depth does not remove risks around margins, tariffs, or customer concentration, but it may sharpen oversight of the complex engineering and program launch cycle.
Gentherm's current analyst framework points to revenues of US$2.2b and earnings of US$161.7m by 2029, based on an assumed 11.8% yearly revenue growth rate and an increase in earnings of about US$135m from US$26.6m today.
Uncover how Gentherm's fair value indicates a 42% potential upside to its current price before the discount closes.
Exploring Other Perspectives
One alternate view says the bigger swing factor for Gentherm is not Asia or margins, but long term volume risk if ride sharing and tighter automaker cost controls curb demand for premium comfort features. The most cautious analysts were penciling in only 5.4% annual revenue growth to about US$1.8b and US$108.7m in earnings by 2029 before this news. That is a much more restrained story than the consensus, and it may shift again once this special dividend and the Mascarenas appointment are reflected in updated models. Treat this as a reminder that smart people can look at the same numbers and still disagree widely, so it can be useful to compare several narratives before deciding how Gentherm fits your own portfolio plan.
Explore 2 other Gentherm fair value estimates, including one that suggests it could be worth just $34.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Gentherm research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Gentherm. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gentherm's overall financial health at a glance.
Looking for more Gentherm style investment ideas?
If Gentherm's blend of capital returns, balance sheet decisions, and leadership changes has your attention, it can be useful to widen the lens and scan for other businesses showing similar financial resilience or different risk and income profiles.
- For investors who want income to do more of the heavy lifting in total returns, review companies offering stronger yields through the 7 dividend fortresses.
- If capital preservation and steadier business profiles are a priority, start with the 31 resilient stocks with low risk scores to see which stocks pass tighter risk filters.
- When the goal is to back financially sound operators with room to execute, sort through our 19 high quality undiscovered gems and see which quieter stories match your criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com