


Pinterest has had a rough few years in the market, and the gap between what the stock has delivered and what its earnings may support has become harder to ignore. With the share price now around US$20.06, the question is whether that tag still lines up with what the business is actually earning.
- Over the past 5 years the stock has fallen 60.6%, which puts fresh focus on whether Pinterest's current earnings profile can justify even today's lower valuation.
- The business model leans on turning user engagement into advertising revenue, so the way that translates into margins and cash generation can have a direct effect on what investors are willing to pay for its earnings.
- Your read on Pinterest is one view; the desks covering it have another. See what analysts think Pinterest's shares could be worth.
The issue now is whether Pinterest's present share price fairly reflects its earnings power based on what the company is producing today.
If you want to stress-test Pinterest's valuation question against other potential opportunities, compare it with companies in the 27 high quality undervalued stocks
Does Pinterest Look Pricey on Earnings?
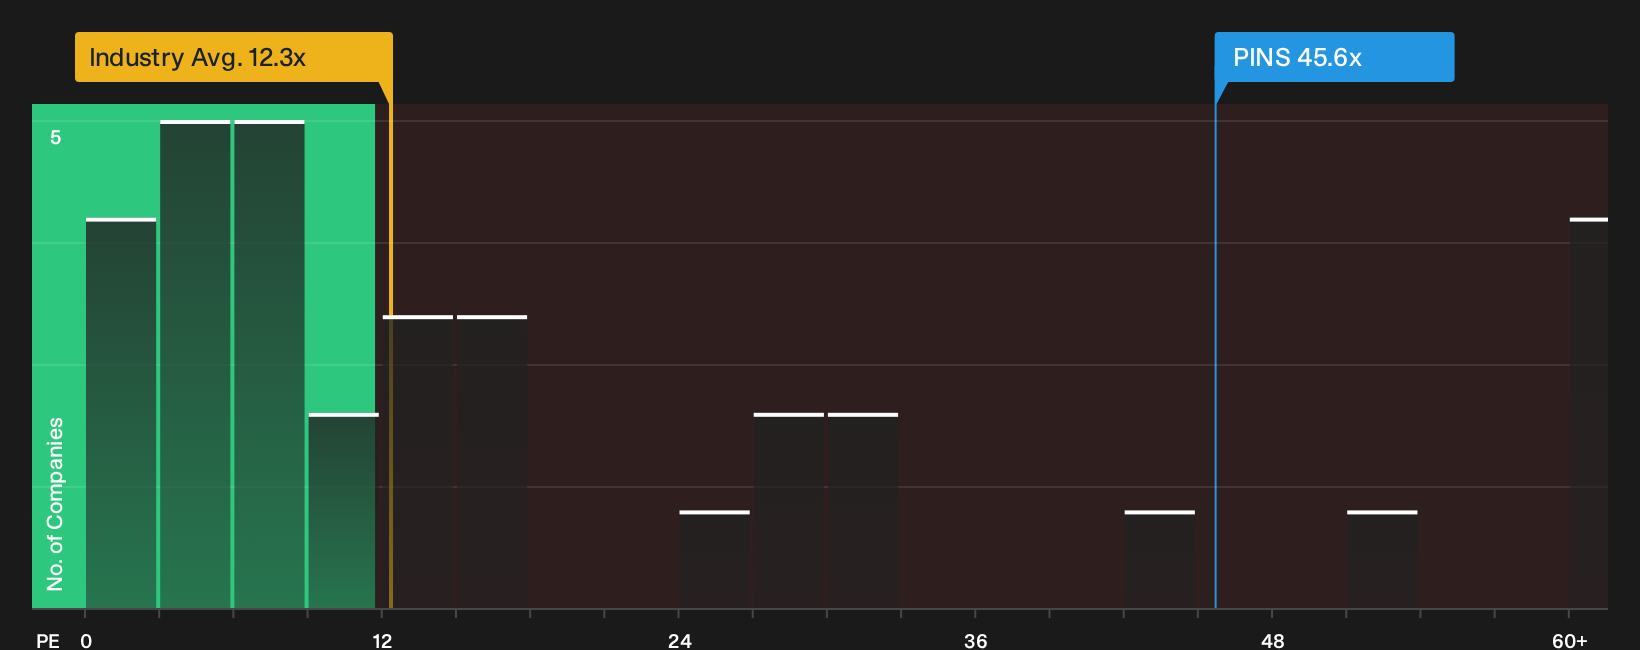
Pinterest is often judged on its P/E ratio because it already produces earnings that can anchor what investors are paying for each dollar of profit. At around 45.6x, the current P/E is well above the broader Interactive Media and Services industry, which trades near 12.3x, and it also sits ahead of the peer group average of about 25.2x.
The Fair Ratio model, which adjusts for Pinterest's own growth profile, margins, scale and risk, points to a lower multiple than where the stock trades now. That gap suggests the market is attaching a richer price tag to the existing earnings stream than this framework would support, so anyone interested in NYSE:PINS needs to be confident that the business quality or future economics justify paying this kind of premium. Explore the numbers behind Pinterest's P/E valuation.
The Pinterest Narrative: What Would Justify Today's Price?
Pinterest Narratives on Simply Wall St pick up where the valuation puzzle leaves off, by spelling out the specific paths for growth, profitability and earnings that would need to occur for the stock to be worth significantly more or less than it is today on the market.
Rather than stopping at a single number from a P/E or fair value model, Narratives set out the future that number is based on so you can track whether Pinterest's real world progress aligns with the scenario behind that figure.
One of the top community narratives on Pinterest: 31% undervalued
"The main thing that has to go right is that Pinterest closes the gap between engagement and monetization, particularly in international and SMB segments..."
Discover why this Narrative puts Pinterest at 31% undervalued.
One more crucial piece of the Pinterest puzzle
Before you decide how Pinterest fits into your watchlist, it helps to know who is steering the ship, how their interests line up with yours, and what incentives actually guide their decisions. See who runs Pinterest and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com