


Architectural products company Apogee (NASDAQ:APOG) announced better-than-expected revenue in calendar Q3 2026 (fiscal Q2 2027), with sales up 9.2% year on year to $391.1 million. The company’s full-year revenue guidance of $1.48 billion at the midpoint came in 3.7% above analysts’ estimates. Its non-GAAP profit of $1.17 per share was 84.3% above analysts’ consensus estimates.
Is now the time to buy Apogee? Find out by accessing our full research report, it’s free.
Apogee (APOG) Q3 CY2026 Highlights:
- Revenue: $391.1 million vs analyst estimates of $351.4 million (9.2% year-on-year growth, 11.3% beat)
- Adjusted EPS: $1.17 vs analyst estimates of $0.64 (84.3% beat)
- Adjusted EBITDA: $49.54 million vs analyst estimates of $31.7 million (12.7% margin, 56.3% beat)
- The company lifted its revenue guidance for the full year to $1.48 billion at the midpoint from $1.46 billion, a 1.7% increase
- Management raised its full-year Adjusted EPS guidance to $3.20 at the midpoint, a 7.6% increase
- Operating Margin: 8.6%, in line with the same quarter last year
- Free Cash Flow Margin: 6.2%, down from 14.6% in the same quarter last year
- Market Capitalization: $744.2 million
"The momentum we established in the first half of the year, combined with our confidence in the business, supports our decision to raise full-year guidance. We also advanced our strategic priorities through the acquisitions of Kalwall and Groglass. Early performance at Kalwall has been encouraging, and we believe the addition of Groglass will further strengthen our portfolio through differentiated capabilities and increased exposure to attractive end markets that support long-term value creation."
Company Overview
Involved in the design of the Apple Store on Fifth Avenue in New York City, Apogee (NASDAQ:APOG) sells architectural products and services such as high-performance glass for commercial buildings.
Revenue Growth
Examining a company’s long-term performance can provide clues about its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Unfortunately, Apogee’s 2.4% annualized revenue growth over the last five years was sluggish. This was below our standards and is a rough starting point for our analysis.
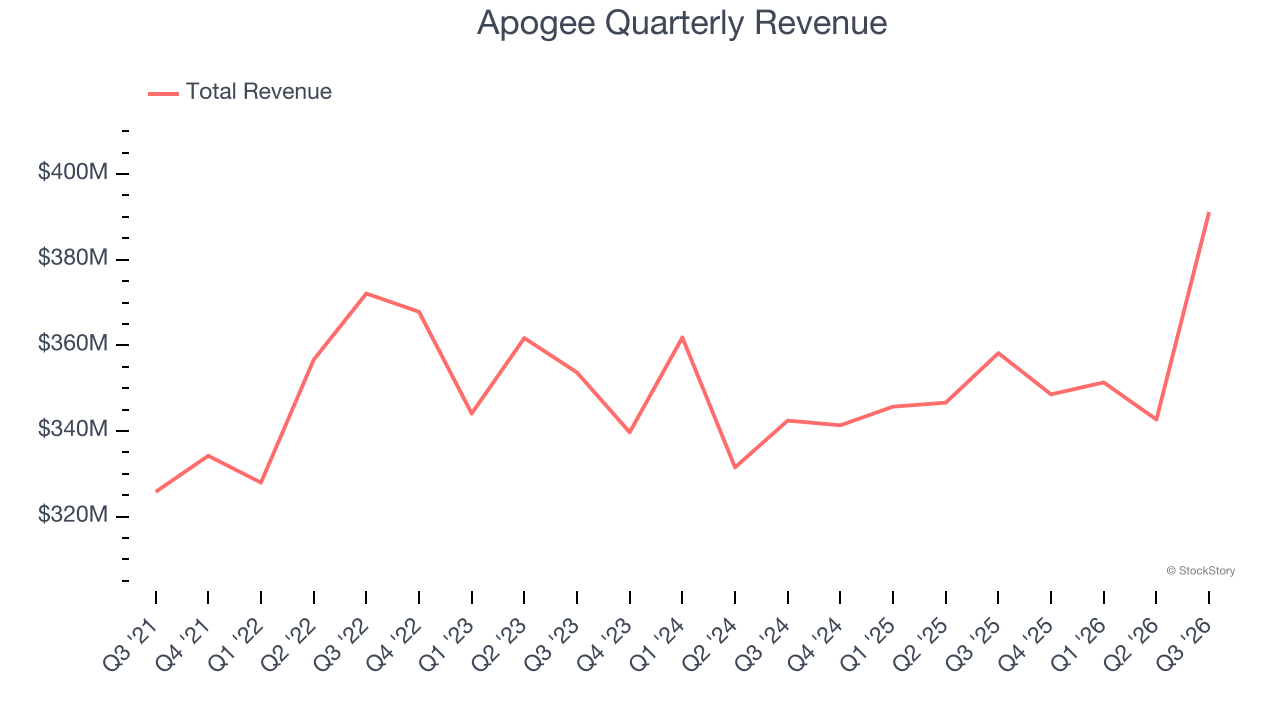
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Apogee’s annualized revenue growth of 2.1% over the last two years aligns with its five-year trend, suggesting its demand was consistently weak. 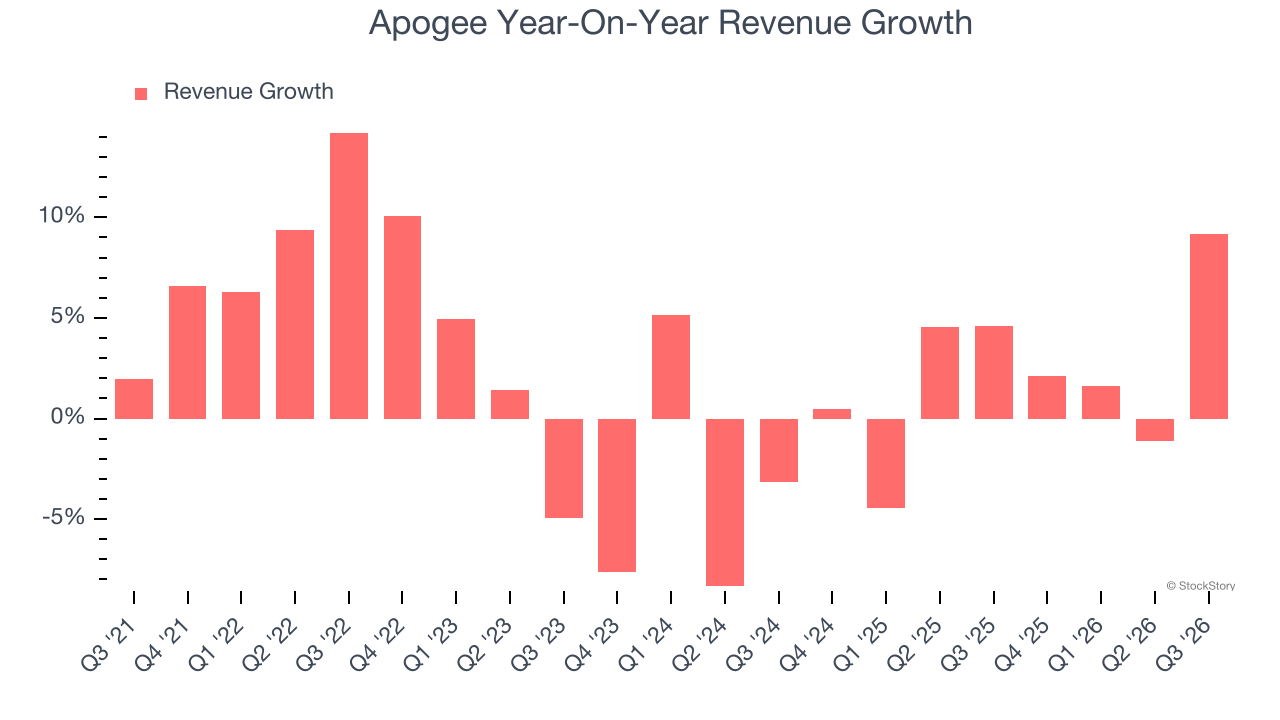
This quarter, Apogee reported year-on-year revenue growth of 9.2%, and its $391.1 million of revenue exceeded Wall Street’s estimates by 11.3%.
Looking ahead, sell-side analysts expect revenue to grow 4.8% over the next 12 months. While this projection indicates its newer products and services will catalyze better top-line performance, it is still below the sector average.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Operating Margin
Apogee has done a decent job managing its cost base over the last five years. The company has produced an average operating margin of 9.4%, higher than the broader industrials sector.
Looking at the trend in its profitability, Apogee’s operating margin decreased by 1.3 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
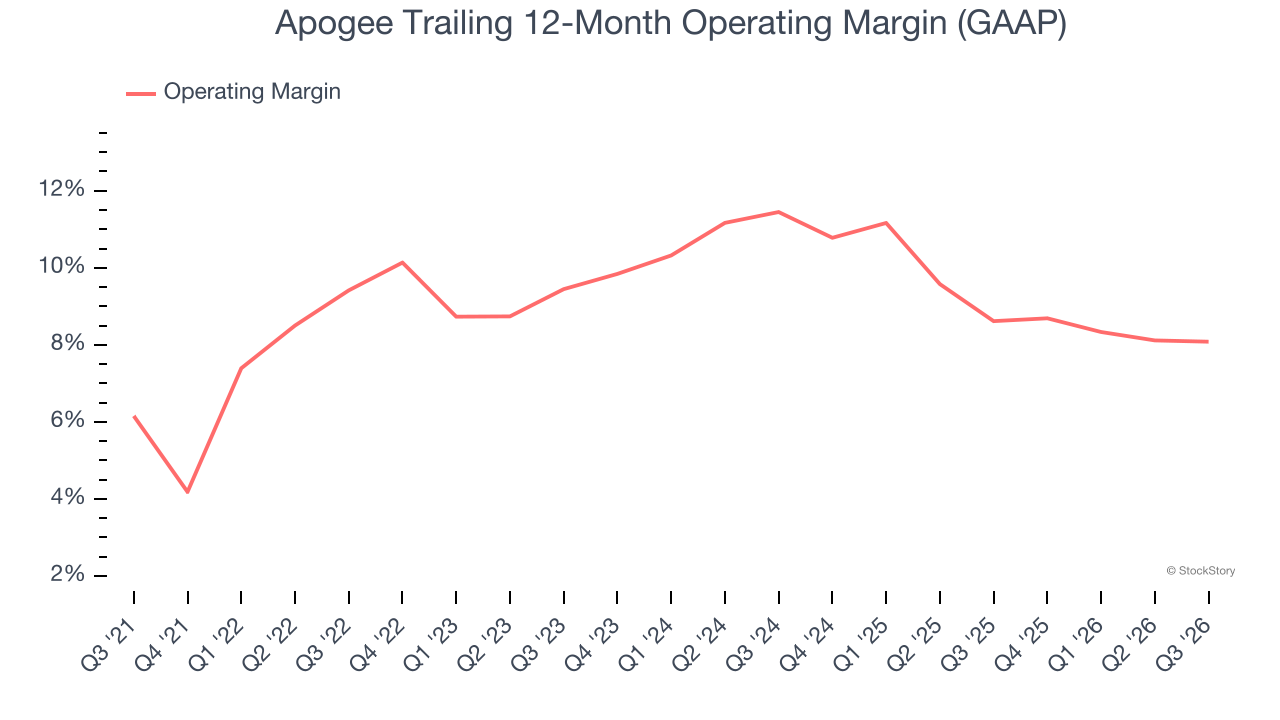
This quarter, Apogee generated an operating margin profit margin of 8.6%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings Per Share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
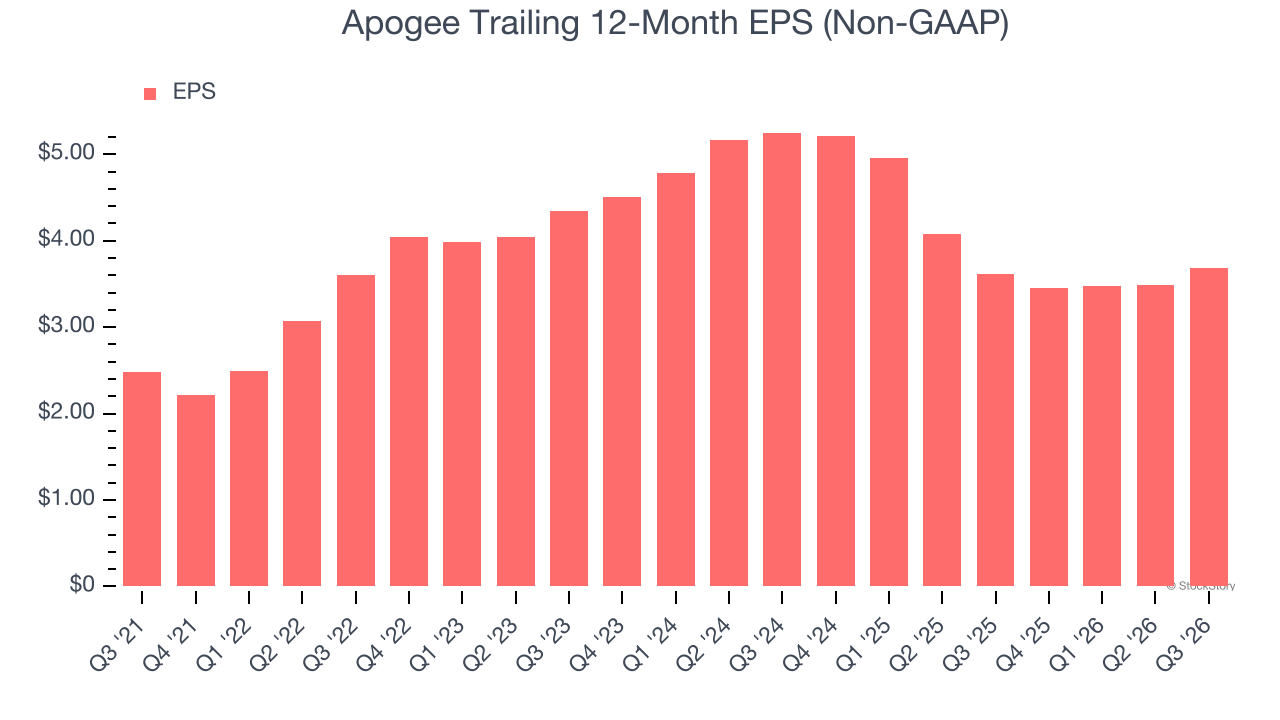
Apogee’s EPS grew at 8.2% compounded annual growth rate over the last five years, higher than its 2.4% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
Diving into Apogee’s quality of earnings can give us a better understanding of its performance. A five-year view shows that Apogee has repurchased its stock, shrinking its share count by 16.9%. This tells us its EPS outperformed its revenue not because of increased operational efficiency but financial engineering, as buybacks boost per share earnings. 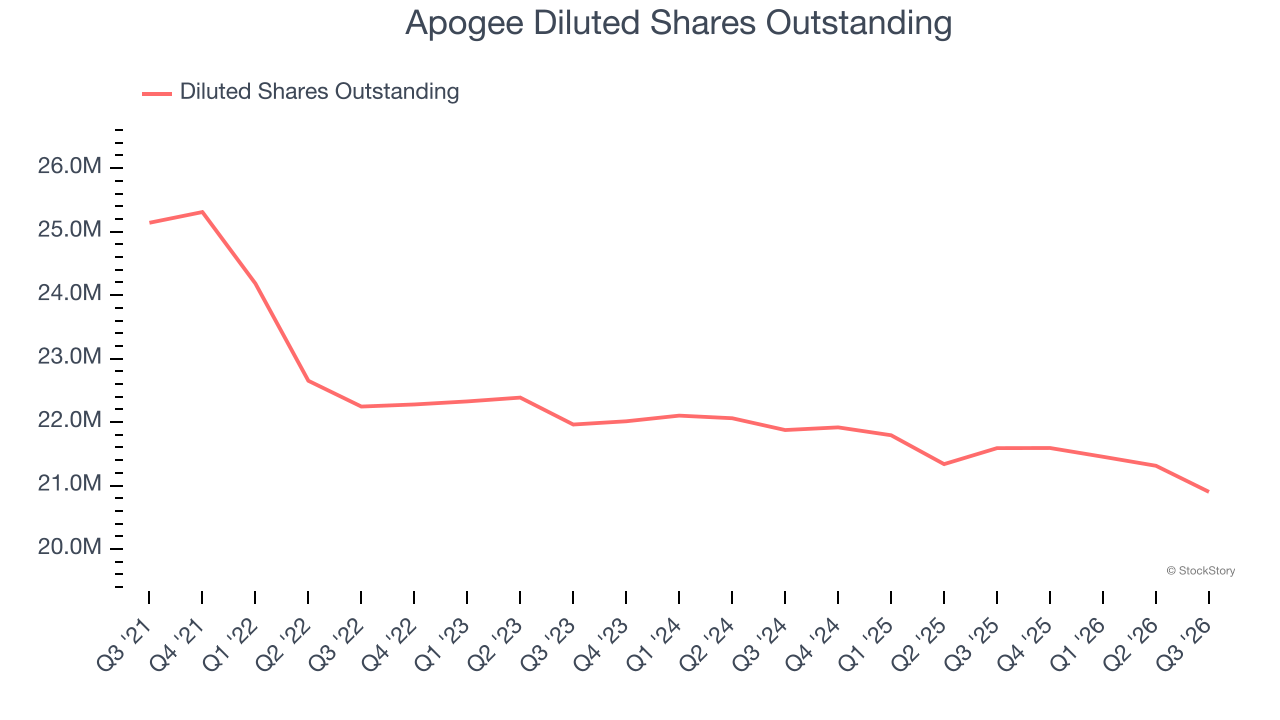
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Apogee, its two-year annual EPS declines of 16.3% mark a reversal from its five-year trend. We hope Apogee can return to earnings growth in the future.
In Q3, Apogee reported adjusted EPS of $1.17, up from $0.98 in the same quarter last year. This print easily cleared analysts’ estimates, and shareholders should be content with the results. Over the next 12 months, Wall Street expects Apogee’s full-year EPS to shrink by 8.3% from $3.68 to $3.38.
Key Takeaways from Apogee’s Q3 Results
It was good to see Apogee beat analysts’ EPS expectations this quarter. We were also excited its EBITDA outperformed Wall Street’s estimates by a wide margin. Zooming out, we think this quarter featured some important positives. The stock traded up 19.7% to $42.68 immediately after reporting.
Apogee had an encouraging quarter, but one earnings result doesn’t necessarily make the stock a buy. Let’s see if this is a good investment. When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).