


Westinghouse Air Brake Technologies (WAB) has come into focus after fresh performance data highlighted a 37.21% year to date return and a 46.55% gain over the past year.
Recent trading shows Westinghouse Air Brake Technologies holding its ground after a strong run, with a 30 day share price return of 3.18% and a 90 day share price return of 12.60% contributing to a 34.95% year to date share price gain and a 235.99% total shareholder return over five years. This performance may reflect momentum that the market is tying to either perceived growth potential or a shift in how investors view the company’s risk profile.
Scan for other rail and industrial momentum stories on Simply Wall St by comparing Westinghouse Air Brake Technologies with a curated set of 39 power grid technology and infrastructure stocks
For Westinghouse Air Brake Technologies, that surge could either mirror steady progress in locomotives and rail systems or reflect changing sentiment around the stock. The valuation work now needs to separate story from substance.
Most Popular Narrative: 11% Undervalued
The most followed narrative on Westinghouse Air Brake Technologies estimates fair value at $329.58 using an 8.73% discount rate, compared with a last close of $291.86. On that basis, the market price sits below this framework of future cash flows and margins.
Rapid growth in Digital Intelligence offerings, with sales up around 76% in Q1 2026 and around 89% in Q2 2026 helped by Inspection Technologies and Frauscher, is increasing the mix of software and data driven services that tend to carry higher gross margins and can lift overall earnings quality.
See why 22 investors see Westinghouse Air Brake Technologies as 11% undervalued.
Result: Fair Value of $329.58 (UNDERVALUED)
Still, the narrative around Westinghouse Air Brake Technologies could be challenged if tariffs keep squeezing margins, or if insider selling signals less conviction at current valuations.
Find out about the key risks to this Westinghouse Air Brake Technologies narrative.
Another View: Westinghouse Air Brake Technologies Through the P/E Lens
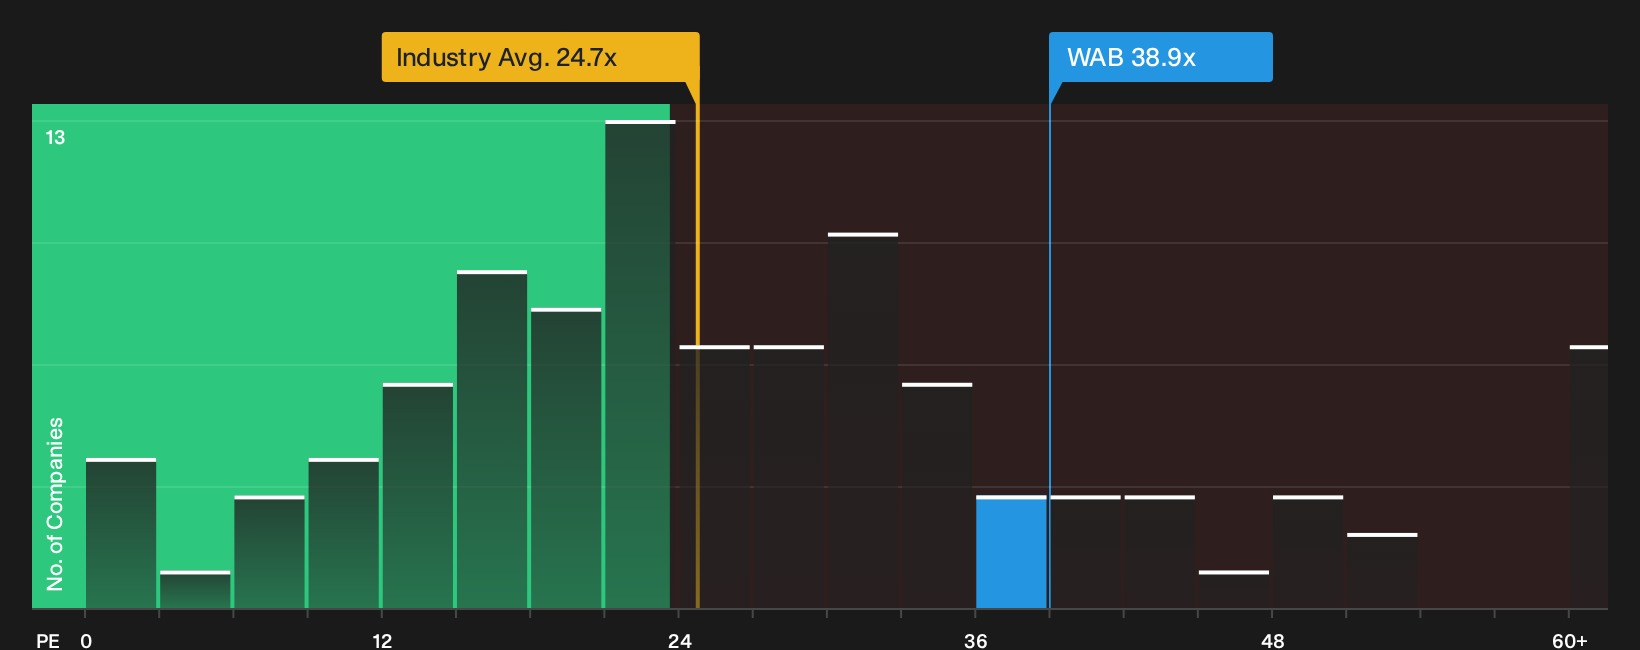
On the flip side of that fair value narrative, Westinghouse Air Brake Technologies looks expensive on a simple earnings yardstick. The P/E sits at 38.9x, above the fair ratio of 31.1x, the US Machinery industry on 24.5x, and peer averages around 20.6x. That gap points to real valuation risk if expectations cool, so which signal do you trust more: the story or the sticker price?
For a closer look at what this pricing gap could mean in practice, including how it compares across peers and scenarios, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Westinghouse Air Brake Technologies so far. Consider acting while sentiment remains divided and pressure test the potential upside and downside using 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Westinghouse Air Brake Technologies?
Use these tools while momentum in Westinghouse Air Brake Technologies has your attention, and do not miss other opportunities that might fit your approach.
- Target potential mispricing by scanning a curated set of 27 high quality undervalued stocks that combine quality fundamentals with attractive valuations.
- Build a steadier income stream by reviewing 7 dividend fortresses that focus on higher yields with an emphasis on durability.
- Prioritise resilience by checking a 31 resilient stocks with low risk scores that screens for companies with stronger balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com