


ICU Medical (ICUI) is in focus after two FDA Class II voluntary recalls, covering Plum administration sets and CADD Yellow Medication Cassette Reservoirs, raised fresh questions about product safety, quality control and business risk.
Against this backdrop, ICU Medical’s 1-day share price return of 1.27% and 90-day share price gain of 6.26% sit alongside a stronger 16.51% year to date share price return and a 36.66% 1-year total shareholder return. This hints that momentum has cooled recently after a stronger run as investors reassess product risk and operational execution.
Spot opportunities beyond ICU Medical by scanning a hand picked group of resilient healthcare names in the 31 resilient stocks with low risk scores, which prioritize product reliability and balance sheet strength.Bulls point to ICU Medical’s solid recent shareholder returns and analyst upside potential, while bears focus on recall risk and thin net income. Which story does the valuation actually support next?
Most Popular Narrative: 16% Undervalued
Against the last close at $161.40, the most followed narrative pegs ICU Medical’s fair value at $191.50. This implies a material valuation gap that is linked to execution around pumps, margins, and cash generation.
Manufacturing network consolidations, portfolio optimization, and realization of integration synergies from the Smiths Medical acquisition are driving visible improvements in gross margin. Further benefits are expected once remaining plant transitions complete over the next year, and sustained gross margin expansion supports higher profitability.
See why 2 investors see ICU Medical as 16% undervalued.
Result: Fair Value of $191.50 (UNDERVALUED)
Still, the narrative around ICU Medical can shift quickly if tariff pressures bite harder into margins or if ongoing FDA scrutiny around recalls increases operational costs.
Find out about the key risks to this ICU Medical narrative.
Another View On ICU Medical’s Valuation
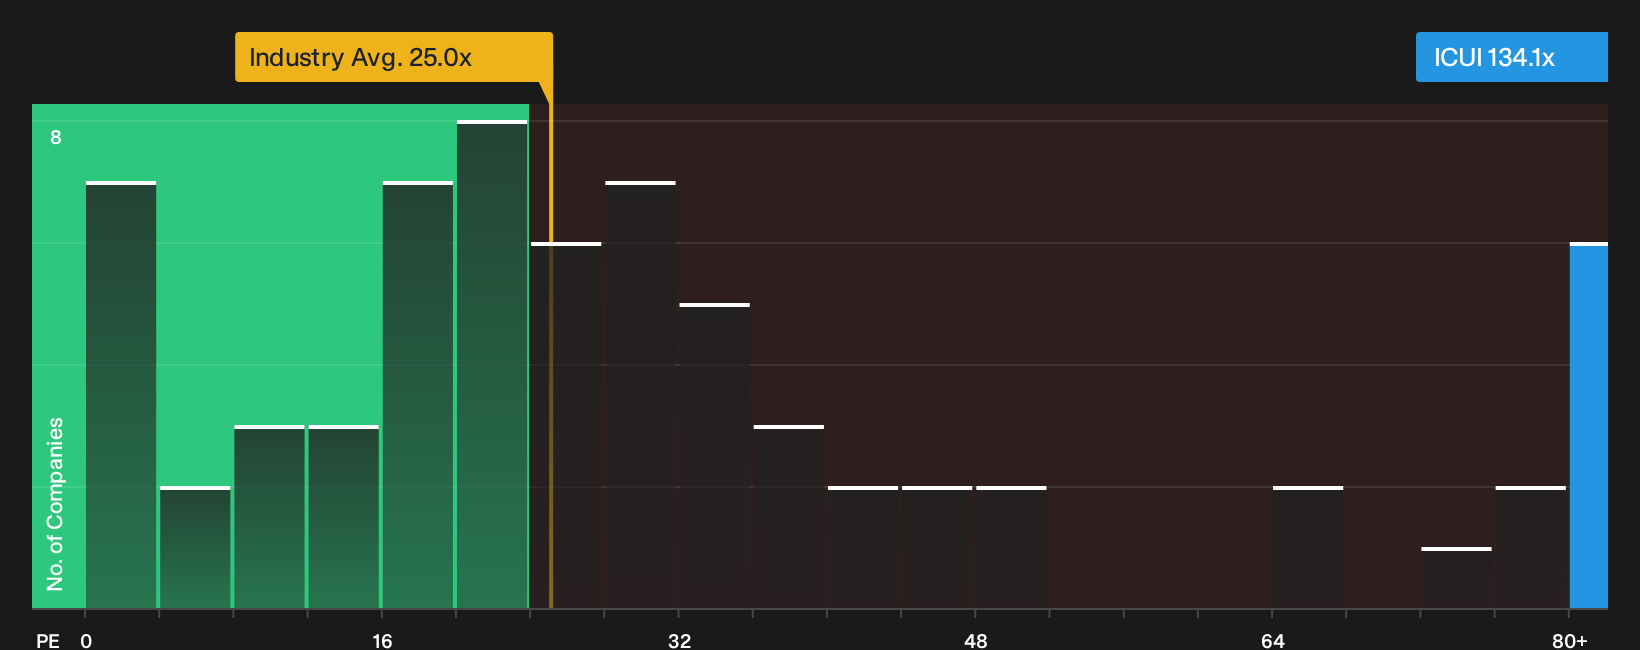
There is a catch. On simple P/E math, ICU Medical trades at about 134x, while similar Medical Equipment peers sit near 24.6x and the fair ratio is flagged at 32.3x. That is a wide gap. Does the discount to fair value outweigh the rich earnings multiple in your playbook?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on ICU Medical’s risk and reward profile make this a judgment call that only you can make. Consider acting promptly, test the numbers against your own expectations, and then weigh the 3 key rewards and 3 important warning signs.
Ready for more ideas beyond ICU Medical?
If ICU Medical has you thinking harder about risk, reward and timing, widen your opportunity set now so you are not relying on a single story.
- Target resilient compounding potential by checking companies that screen as 27 high quality undervalued stocks with solid fundamentals backing the thesis.
- Strengthen portfolio durability by focusing on businesses that pass the list of solid balance sheet and fundamentals (25 results) for financial flexibility and lower funding stress.
- Get ahead of the crowd by scouting 19 high quality undiscovered gems before the wider market pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com