


WESCO International (WCC) is back in focus after partnering with LEDVANCE on a turnkey LED lighting upgrade for Toyota Brossard’s Quebec Regional Office, targeting energy savings and lower maintenance needs.
Recent trading has been strong for WESCO International, with a 7-day share price return of 3.41% and a 30-day gain of 7.29%. The 90-day move of 22.75% and year-to-date share price return of 49.57% suggest momentum has been building despite a 1-day dip of 1.22% to US$377.09.
Scan beyond WESCO International and this Toyota Brossard project by reviewing a curated 39 power grid technology and infrastructure stocks that are also tied into critical energy and infrastructure upgrades.
After a near 50% year to date climb and a business tied into large energy and infrastructure projects, does WESCO International still offer enough upside to compensate for the risks at today’s price, once valuation is unpacked?
Most Popular Narrative: 5% Undervalued
The most followed valuation narrative for WESCO International points to a fair value close to $397.09, compared with the last close at $377.09. This puts recent price strength in context rather than calling it stretched.
Broad based infrastructure and nonresidential construction spending across utilities, broadband, industrial and OEM customers is feeding into record backlogs in all three business units. This can translate into sustained revenue and support earnings consistency as projects convert.
See why 1 investors see WESCO International as 5% undervalued.
Result: Fair Value of $397.09 (UNDERVALUED)
Still, the bullish WESCO International story can unravel if AI data center build outs slow, or if large grid projects are delayed or repriced by key customers.
Find out about the key risks to this WESCO International narrative.
Another View On WESCO International’s Valuation
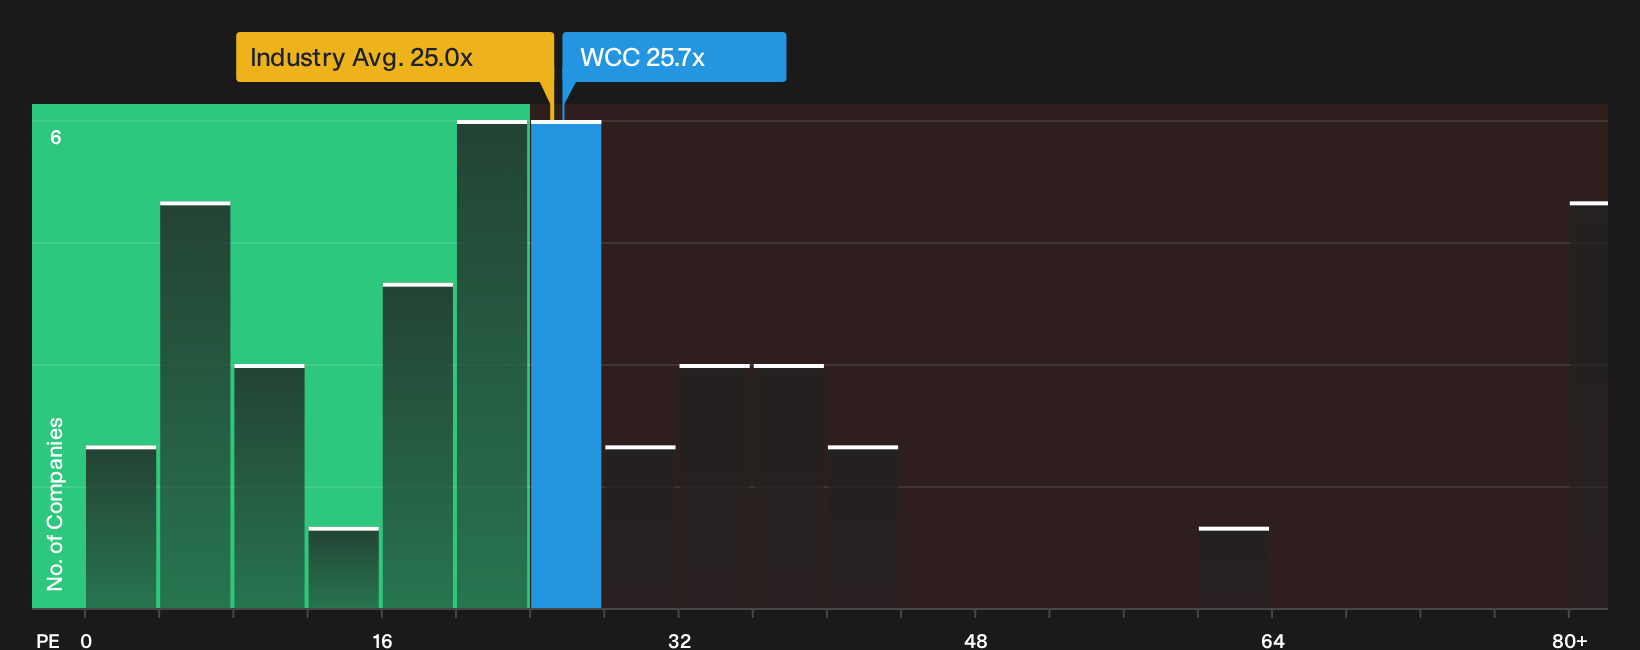
The SWS fair ratio tells a different story. WESCO International trades on a P/E of 25.7x, slightly above the US Trade Distributors industry at 25.1x and well above peer averages at 21.3x, while the fair ratio points to 28x. That gap hints at less margin of safety than the DCF suggests, so which signal do you trust more at US$377.09?
See what the numbers say about this price in our valuation breakdown, then decide how much P/E risk you are comfortable carrying at this stage of the move. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and caution around WESCO International feels familiar, treat it as your cue to review the numbers yourself and move quickly to a clear stance. Anchor that view in both the upside and the downside by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond WESCO International?
Do not stop your research at WESCO International when a wider watchlist could reveal opportunities that fit your risk tolerance and income goals even better.
- Target potential mispricing by scanning a curated pool of quality companies using the 27 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by filtering for resilient balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Lock in reliable income streams by reviewing a focused universe of high-yield payers via the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com