


The Federal Reserve just lifted interest rates again and signaled borrowing costs may stay higher for longer. Cash in the bank now feels more rewarding, yet that also puts pressure on plenty of companies that rely heavily on cheap debt. Reliable income payers that already offer yields above 3% with room to keep paying and growing those dividends can appear more attractive in this environment. This article highlights three such dividend-heavyweights from the screener.
The stocks covered below are just a small sample. The full Dividend Powerhouses screen surfaced 171 more companies with yields above 3% and income stories that are not discussed here. To hunt for your own income ideas, head straight into the Dividend Powerhouses (3%+ Yield) screener to identify, filter, and analyze the dividend payers that best match your conviction.
Southside Bancshares (SBSI)
Southside Bancshares is a Texas based bank holding company that leans on a traditional mix of deposits, loans, and fee services to underpin its dividend. It slots neatly into a screen that looks for well covered, stable payouts rather than more speculative income stories.
Southside Bancshares generates about US$245 million in banking revenue and has a market value near US$916 million, with its interest earning loan book and deposit base doing the heavy lifting that funds the dividend investors focus on.
"Exposure to ongoing population and job growth across Texas continues to drive strong new loan production and commercial deposit growth, positioning the bank to benefit from higher loan balances and fee income, which should support future revenue and earnings expansion."
What happens if one quiet source of earnings pressure keeps tugging on those payout and growth assumptions at the same time?
That quiet squeeze on assumptions is where the story gets interesting, and the full narrative for Southside Bancshares explains how Southside Bancshares could aim to convert Texas growth into relatively stable income.

First Interstate BancSystem (FIBK)
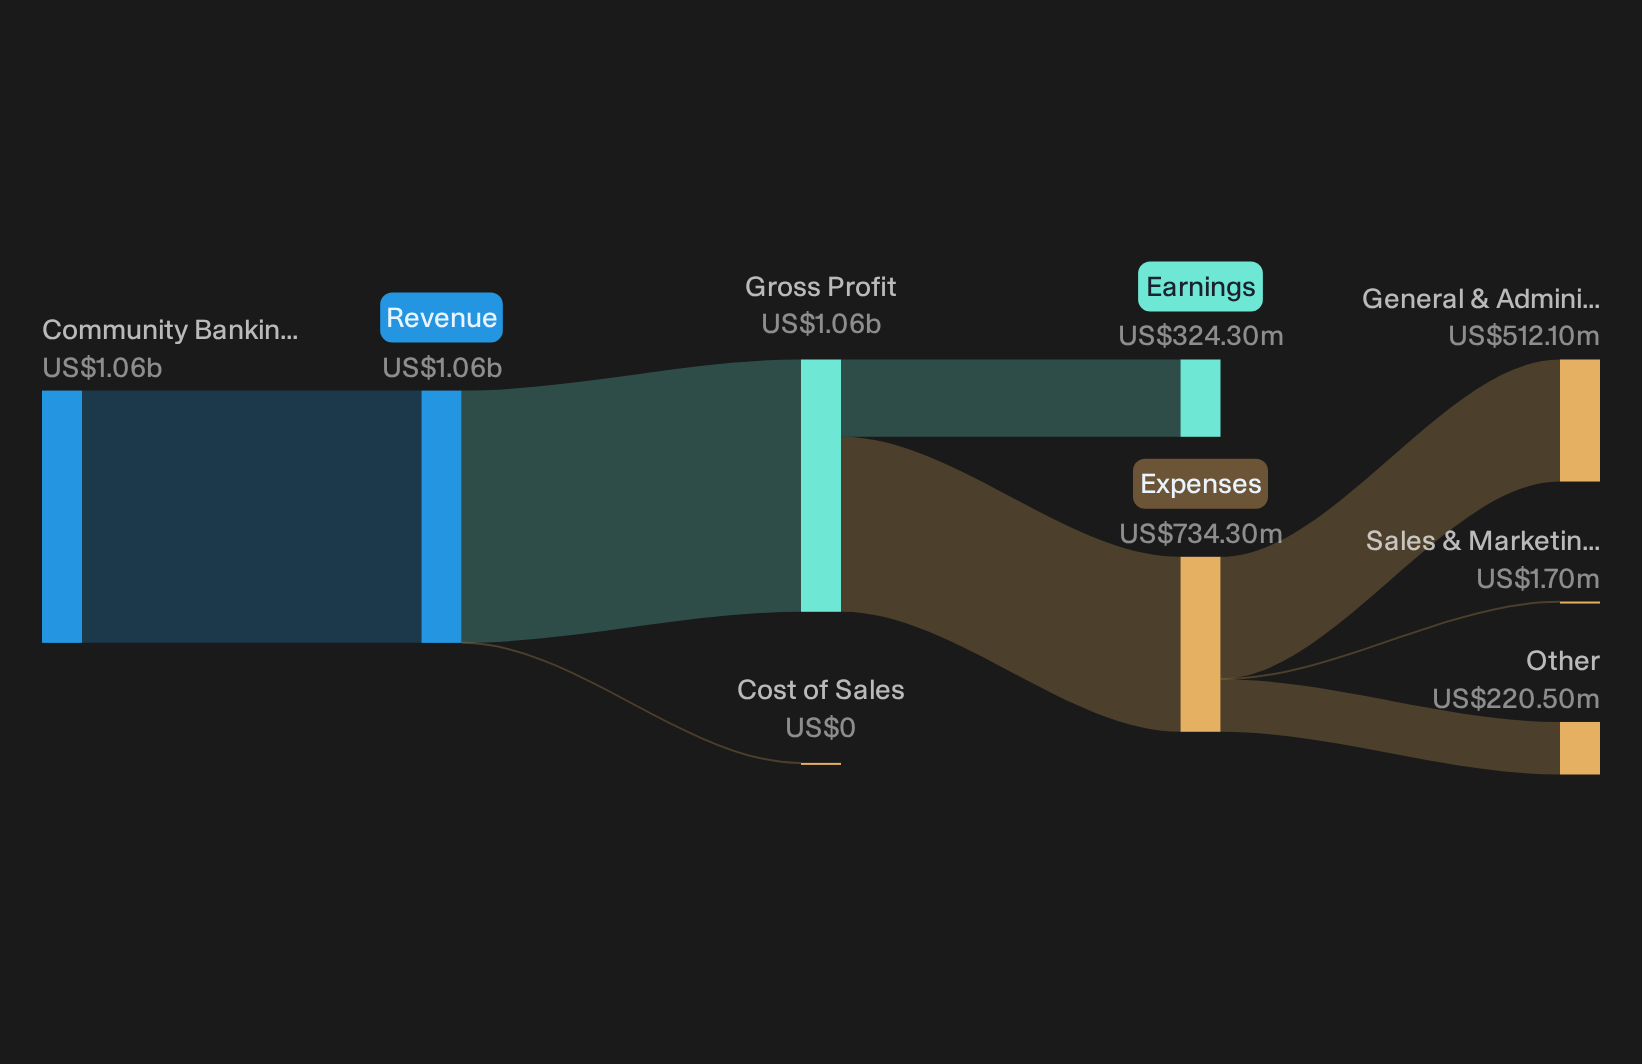
First Interstate BancSystem leans on its community banking engine, using deposits and loans to generate income that supports a steady dividend profile. The bank produced about US$1.1b from community banking in the United States and carries a market value near US$3.4b.
First Interstate BancSystem appeals to income hunters because its everyday banking work, from taking deposits to writing loans, feeds directly into the kind of recurring cash flows that can underpin a higher yielding, well covered dividend.
"Ongoing repricing of about $2.6b of fixed and adjustable rate loans at an average 4.5% yield and $2b of securities at a 2.7% yield through 2027, together with recent progress in lowering deposit and total funding costs, is expected to keep supporting net interest margin for First Interstate BancSystem and therefore its earnings power."
What investors will really care about is how one quiet shift in the balance sheet shapes the next leg of margins and dividend headroom.
That quiet shift starts to look more important once you read the full narrative for First Interstate BancSystem, which explains in detail how First Interstate BancSystem’s repricing engine could influence dividend resilience.
Peoples Bancorp (PEBO)
Peoples Bancorp runs a traditional community banking engine built on deposits and loans that feeds the kind of recurring income this Dividend Powerhouses screen looks for, with its broader insurance and wealth services adding extra fee-based steadiness behind those regular cash payouts.
Peoples Bancorp generates about US$435 million from community banking in the United States and has a market cap near US$1.3b, putting it in the mid sized regional bank bracket.
Investors watching Peoples Bancorp for reliable income will focus first on how its lending and deposit franchise keeps driving steady net interest and fee earnings that support a well covered dividend, then on what could positively surprise that cash flow story over time.
"Robust loan growth across diversified categories, alongside population and business migration to secondary and tertiary markets where the bank operates, suggests Peoples Bancorp is well positioned to benefit from increased loan demand and local economic strength, which is likely to support future revenue and earnings expansion."
The real swing factor for income focused holders is how one emerging pressure on profitability ultimately settles against that supportive growth backdrop.
That emerging profitability pressure is only part of the picture, and the full narrative for Peoples Bancorp shows how Peoples Bancorp’s earnings engine could keep accelerating beyond headline loan growth.

Curious About Alternative Paths To Income?
The strongest opportunities rarely stay quiet for long. Fresh ideas build momentum, laggards keep dropping, and under the radar for now rarely lasts. Scan what is moving first and get in early.
- Target resilient cash generators by running the 31 resilient stocks with low risk scores and focus on companies where robust balance sheets meet measured growth before the crowd starts chasing safety.
- Hunt for real earnings power with the 36 profitable AI stocks that aren't just burning cash and zero in on AI businesses where revenue is flying while cash burn has already been tamed.
- Track infrastructure momentum using the 39 power grid technology and infrastructure stocks and spot potential winners building the backbone for tomorrow's energy systems while it still feels early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com