


- Hokkaido Electric Power Company raised its consolidated earnings guidance for the year ending March 2027, now projecting net sales of ¥1,025b, operating income of ¥61b and profit attributable to owners of parent of ¥33b.
- The revised outlook highlights how fuel cost adjustment charges, sales to other utilities during a period of high fuel prices and updated wheeling tariffs are shaping Hokkaido Electric Power Company’s earnings mix.
- The focus now is on how this higher earnings guidance, driven by tariff and fuel pass through mechanics, could influence the investment narrative.
Compare Hokkaido Electric Power Company's revised guidance with other regulated utilities by running your filters across our hand picked 39 power grid technology and infrastructure stocks
What Is Hokkaido Electric Power Company's Investment Narrative?
To own Hokkaido Electric Power Company, you need to be comfortable with a straightforward regulated utility story where earnings are anchored in tariffs, fuel cost pass through and fairly heavy infrastructure spending. The raised guidance ties near term profit more tightly to fuel cost adjustment charges, sales to other power companies and revised wheeling fees. That is supportive for the current year, although it still sits against a backdrop of thinner recent profit margins and debt that is not well covered by operating cash flow.
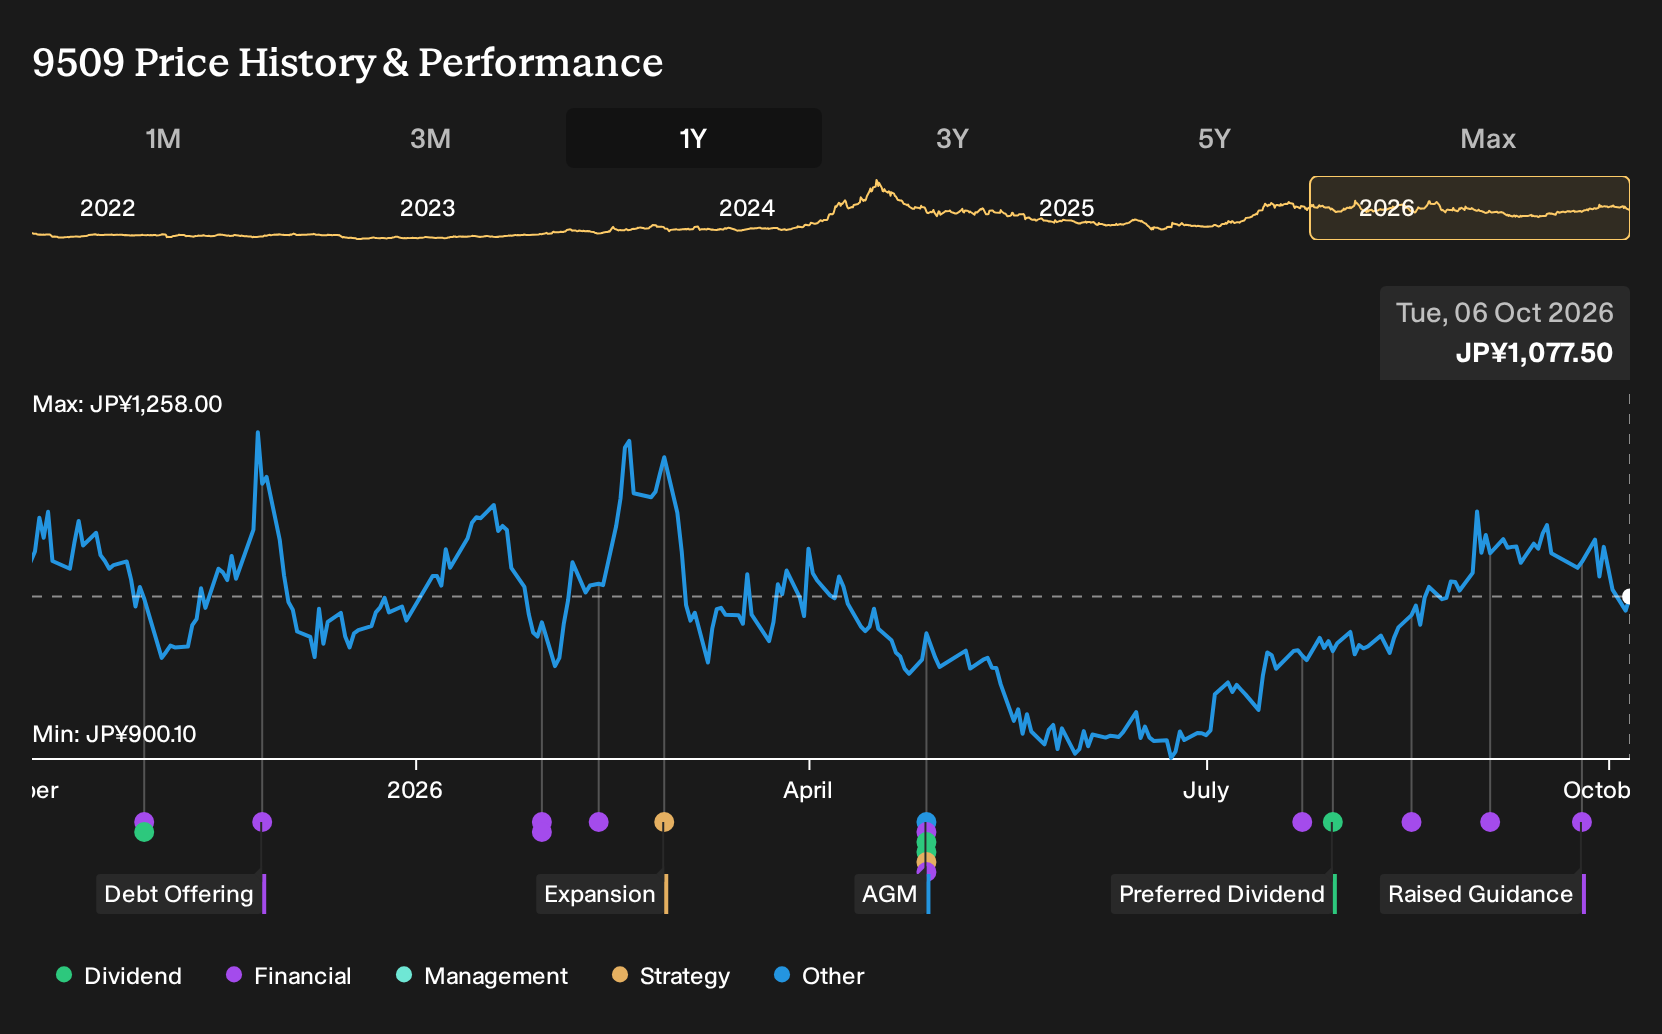
In the short term, the key swing factors are execution on electricity sales volumes, how fuel costs feed through the tariff formula and the capital needed to maintain and upgrade the grid. The stock has had a mixed run, with the share price up over 3 years but down over the past year, so this guidance reset may matter more for sentiment than for radically changing the business trajectory. Dividend coverage and the need to fund a capital intensive network remain the practical constraints on how far the investment case can stretch.
Even so, there is one structural pressure on Hokkaido Electric Power Company that rarely shows up in a simple guidance upgrade and ...
There's only one way to know the right time to buy, sell or hold Hokkaido Electric Power Company. Head to Simply Wall St's company report for the latest analysis of Hokkaido Electric Power Company's Fair Value.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Hokkaido Electric Power Company research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Hokkaido Electric Power Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hokkaido Electric Power Company's overall financial health at a glance.
Looking For More Ideas Beyond Hokkaido Electric Power Company?
If you want to broaden your watchlist beyond Hokkaido Electric Power Company, the Simply Wall St Screener lets you quickly zero in on other businesses that fit the kind of balance sheet strength, value profile or income potential you care about most.
- For investors who want to focus on financially resilient businesses with room to reinvest, filter for companies on our 75 high quality undiscovered gems to see which stories the market may not be paying full attention to yet.
- If capital preservation and steadier risk profiles matter most to you, narrow your search to companies from the 22 resilient stocks with low risk scores to spot stocks that align with a more defensive approach.
- For readers who care about funding strength as much as earnings power, scan through our list of solid balance sheet and fundamentals (23 results) to find businesses with balance sheets designed to support long term plans.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com