


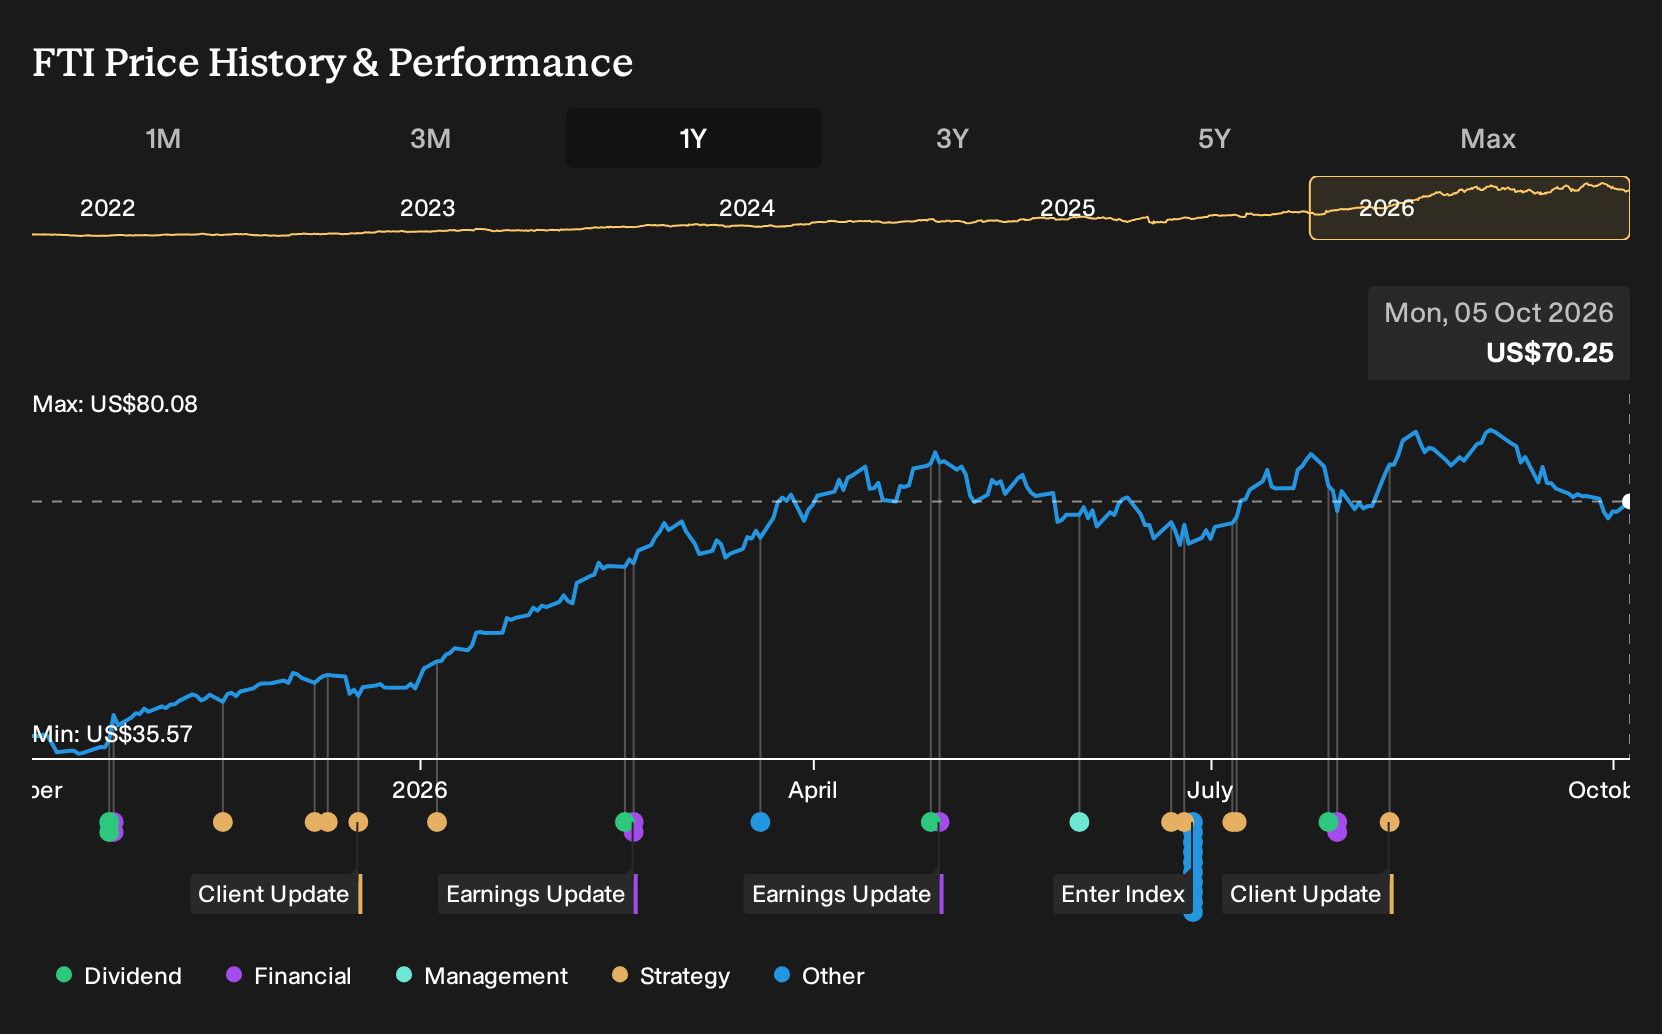
If TechnipFMC sat on your watchlist instead of in your portfolio, the result probably caught your eye. Investors who held TechnipFMC over the past year are up 85.4%, including dividends. That kind of move invites a harder question. Back on 5 October 2025, what in the public record about subsea order momentum and the push into integrated iEPCI projects could have helped you judge whether this revenue and margin story was worth backing early?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The move put TechnipFMC in the middle of this trade. Scan 19 nuclear energy infrastructure stocks for other companies exposed to it.
The Two TechnipFMC Stories Investors Had To Weigh
The shares cost US$38.04 at the start of the period, and TechnipFMC sat between two very different but reasonable stories about its future.
The bullish Narrative argued for Fair Value of US$41.14. It leaned on subsea order momentum, a 5.8% annual revenue growth assumption, and profit margins rising to 10.6% helped by integrated iEPCI work and long duration Subsea services.
The bearish view put Fair Value at US$30. It focused on commodity price volatility, tariff risk, and the possibility that long term offshore projects and subsea backlog might face delays that squeezed margins and slowed earnings progress.
What The Results Changed In The TechnipFMC Argument
TechnipFMC secured several large subsea contracts in Angola, Côte d’Ivoire and Norway, and reported Q2 2026 revenue of US$2.76b versus US$2.53b in Q2 2025. Net income rose from US$269.5m to US$362.7m, and net margin moved from 10.6% to 13.1%. Guidance for 2026 revenue below earlier expectations and insider selling pushed back against the most optimistic case. Overall, the evidence cut both ways.
The hinge assumption here was that integrated subsea orders would feed into higher profitability. When you study another offshore contractor, track whether order wins show up in rising net margin a year or two later rather than just a bigger backlog number.
What TechnipFMC’s Price Already Assumes
TechnipFMC now trades at US$70.25, and the selected Narrative’s Fair Value sits below that market price. The gap reflects concern that a strong share run already bakes in very high execution on subsea projects.
Anyone paying today’s price is effectively assuming subsea orders build backlog and support healthy margins. The question is how the highlighted surface weakness and flat backlog risk that assumption if project awards or pricing soften.
"Although TechnipFMC reports a growing subsea project opportunity list, the recent flattening of overall and subsea backlog suggests new awards may only replace executed work rather than build true growth, which could limit future revenue and earnings if the expected backlog expansion does not materialise."
One Narrative disagrees with today's price. → See where this Narrative says TechnipFMC should trade
Another Way To Play Offshore Work
TechnipFMC lives where offshore projects are designed, installed and serviced. Your watchlist does not need to stop there.
Those same long dated fields still need crude and gas brought to shore, then processed into fuels and chemicals for end markets.
One large energy group concentrates on lower cost reservoirs, large liquefied gas projects and high volume refining and chemical complexes.
It is also investing in carbon capture, lower emission fuels and battery materials that could matter as policies tighten.
If offshore momentum holds up, that broader mix could shape how value eventually flows along the chain.
One Narrative has already put a figure on it. → Uncover the company trading 18% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com