


- Abbott Laboratories recently received FDA approval for upgraded capabilities on its CardioMEMS HF System and began U.S. commercialization of SimpleScreen CRC, an FDA approved blood based colorectal cancer screening test for average risk adults 45 and older.
- These launches extend Abbott Laboratories' reach in heart failure monitoring and early cancer detection by adding app based heart failure tools and a blood draw screening option that could influence long term demand patterns across its medical device and diagnostics portfolio.
- We will look at how Abbott Laboratories' investment narrative is shaped by digital CardioMEMS features that deepen remote heart failure management.
Abbott Laboratories Investment Narrative Recap
To own Abbott Laboratories, you need to believe its broad health portfolio can keep converting product launches into steadier earnings while legal and manufacturing costs in Nutrition stay manageable. The near term swing factor is execution in Devices and Diagnostics as analysts look for margin uplift from 11.6% toward their longer term assumptions.
The recent CardioMEMS upgrades and SimpleScreen CRC launch support the existing growth story but do not fundamentally change the biggest risk, which remains legal and regulatory exposure plus a high debt load that can pressure profitability. Those headlines mainly reinforce the view that pipelines in heart failure and cancer testing need to translate into consistent volume and mix benefits.
The CardioMEMS HF System update, with the CardioGuide HF App and Dynamic Treatment Plan, looks most relevant for your near term thesis. It speaks directly to whether Abbott Laboratories can turn its device pipeline in areas like heart failure and electrophysiology into higher usage of existing platforms rather than relying only on brand new hardware.
Operationally, that app centric model leans into remote monitoring, recurring data driven engagement and potentially stickier relationships with clinicians. That is where a lot of device growth expectations already sit. Execution risk is clear. Clinicians and health systems need to adopt the new workflow at scale, and reimbursement and data integration have to support that shift for CardioMEMS to contribute meaningfully to the catalysts analysts are already focused on.
What The Current Abbott Laboratories Forecasts Assume
Abbott Laboratories' current story on Wall Street leans heavily on steady expansion rather than heroic outcomes. Analysts are building their models around 8.8% yearly top line growth over the next three years, paired with profit margins rising from 11.6% today to 16.0% by 2029. That frame matters for anyone tying the CardioMEMS and SimpleScreen CRC launches back to the bigger financial picture.
On earnings, the consensus view points to US$5.4b today moving to US$9.6b by 2029. That is an increase of roughly US$4.2b in profit that has to materialise across Devices, Diagnostics, Nutrition and Established Pharmaceuticals. The spread between the most optimistic and most cautious forecasts is wide, from US$6.5b to US$11.5b, which shows that analysts do not fully agree on how much Abbott Laboratories can translate its pipeline into bottom line progress.
Valuation assumptions sit on top of those operating forecasts. To line up with the current analyst targets, investors would need to accept a P/E of 26.8x on the 2029 earnings estimate, compared with about 32.9x today and against an industry reference point of 24.8x for GB Medical Equipment companies. That suggests the stock would still trade at a premium to peers even after some multiple compression. In this framework, the gap is linked to confidence in devices like CardioMEMS, Libre and the cancer testing portfolio turning into durable cash flows.
Those same models also assume a small reduction in share count, with the number of shares outstanding expected to decline by 0.49% a year over the next three years. That kind of pacing typically reflects modest buyback activity rather than aggressive capital return. This would align with a group that is still spending heavily on manufacturing capacity, including Libre, and on resolving past legal issues in Nutrition.
Abbott Laboratories' narrative projects US$60.0b revenue and US$9.6b earnings by 2029. This rests on 8.8% yearly revenue growth and an earnings increase of about US$4.2b from US$5.4b today.
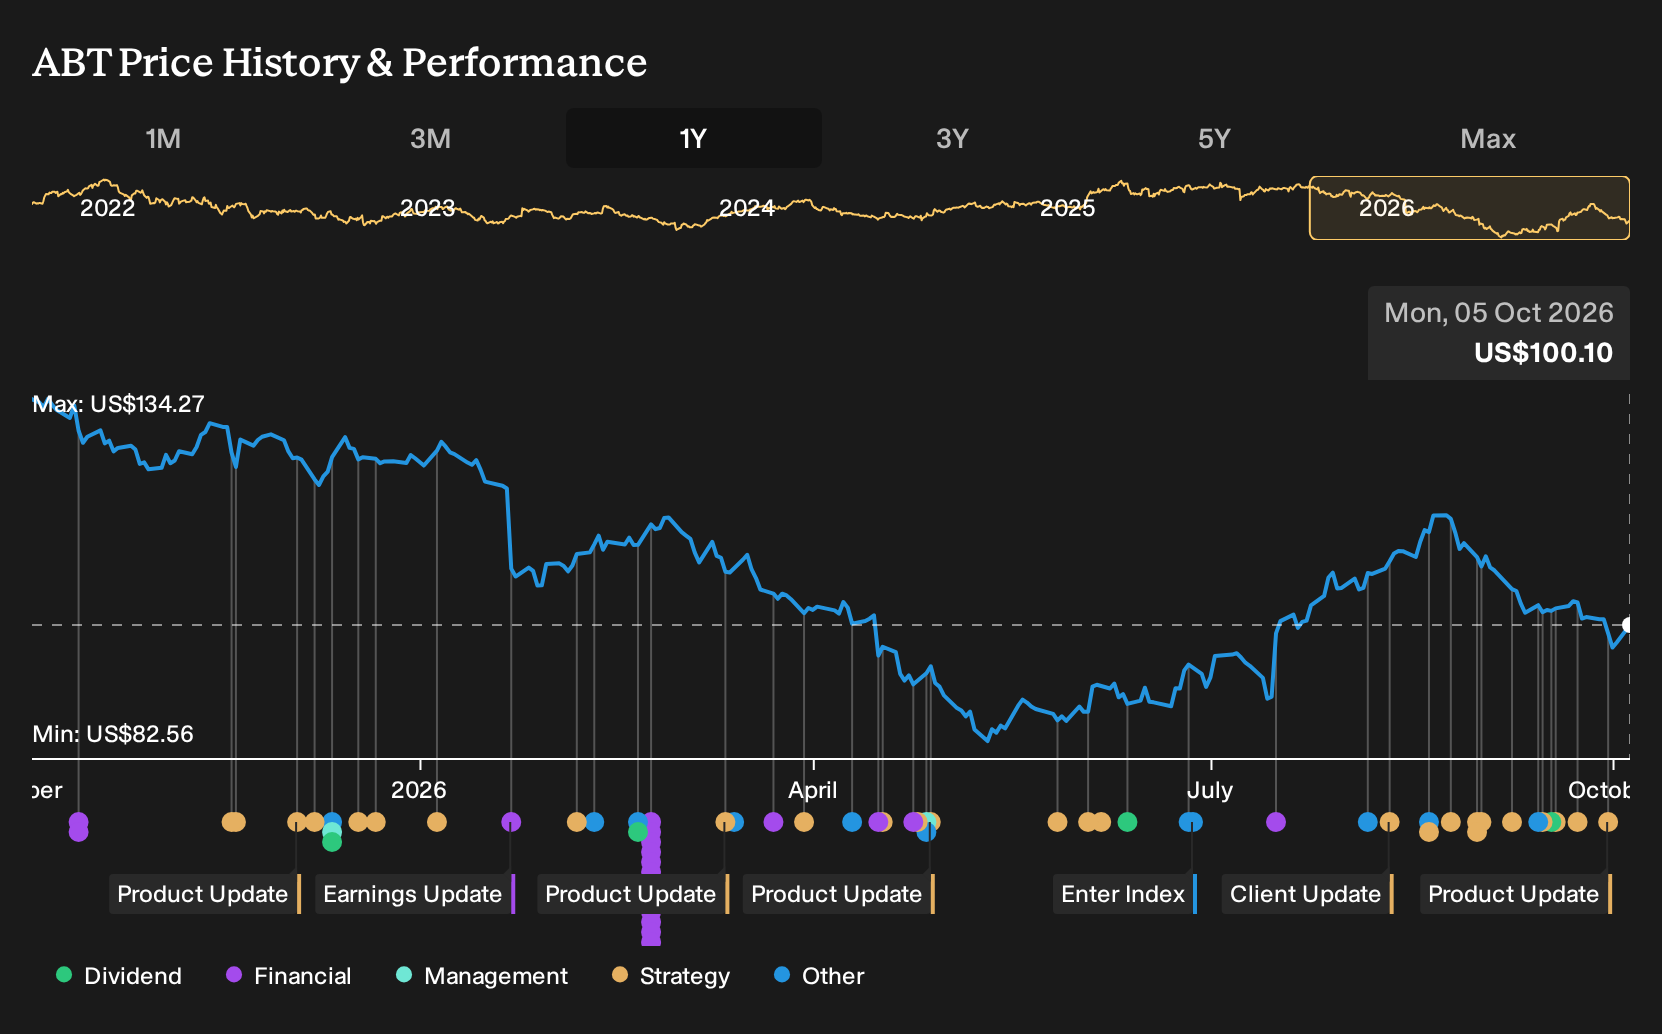
Uncover how Abbott Laboratories' fair value indicates a 20% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Six fair value estimates from the Simply Wall St Community cluster between US$80.67 and US$120.74, so some private investors see Abbott Laboratories as heavily discounted while others price in richer expectations. Set those views against risks around ongoing legal costs and margin pressure. Use that spread to test several alternative viewpoints before deciding how today’s digital health launches might shape your own stance.
Explore 5 other Abbott Laboratories fair value estimates, including one that suggests there may be as much as 21% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Abbott Laboratories research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Abbott Laboratories. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Abbott Laboratories' overall financial health at a glance.
Looking For More Investment Ideas Beyond Abbott Laboratories?
If the Abbott Laboratories story has sharpened your view on healthcare, you can use that same lens to scan a wider field of opportunities with the Simply Wall St Screener.
- For investors hunting for quality at a discount, filter the market for companies that screen as 27 high quality undervalued stocks and compare their fundamentals side by side.
- If capital preservation matters most to you, narrow your search to businesses that score well on resilience using a 31 resilient stocks with low risk scores that focuses on steadier balance sheets and risk profiles.
- When you want strong foundations without paying up for hype, sort through a list of solid balance sheet and fundamentals (25 results) and focus on enterprises with healthier finances and more robust cash generation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com