


- Casella Waste Systems received approval from the New York State Department of Environmental Conservation to expand the Hakes C&D Landfill in Campbell, New York, adding about 43.3 acres of disposal area and an estimated 5.8 million cubic yards of capacity, plus a larger soil borrow area and space for upgraded leachate and gas systems.
- The expanded footprint and planned infrastructure at Hakes give Casella Waste Systems more room to support its vertically integrated waste model. This can help align disposal availability, route density, and regulatory compliance in a region where construction and demolition activity is an important volume driver.
- We will examine how Casella Waste Systems' investment narrative intersects with the newly permitted additional Hakes landfill capacity and infrastructure relocation.
Scan other waste and infrastructure operators with capacity stories similar to Casella Waste Systems by checking our hand picked list of list of solid balance sheet and fundamentals (25 results).
Casella Waste Systems Investment Narrative Recap
To remain a shareholder in Casella Waste Systems, you need to believe the vertically integrated model can convert more of its landfill access, recycling contracts, and tuck in deals into durable earnings, not just revenue. The Hakes expansion fits that story by adding disposal room and infrastructure options, although the near term earnings picture still looks tight with slim 0.3% net margins.
The immediate swing factor is whether cost controls, automation, and Mid Atlantic integration work can relieve margin pressure and support interest coverage that external research already flags as a concern. The key risk right now is that operating costs, one off items, and acquisition expenses keep compressing profitability, which would leave the rich P/S multiple harder for investors to justify.
The Hakes permit directly intersects with an earlier narrative catalyst around growing landfill volumes and higher internalization as Casella Waste Systems builds out disposal in the Northeast and Mid Atlantic. More permitted capacity at a construction and demolition landfill aligns with that thesis because it can give the business more room to route collected waste into its own assets instead of third party sites.
That same narrative also highlights infrastructure projects, automation, and renewable natural gas partnerships as important levers for EBITDA margin recovery and new income streams. Hakes now becomes another physical anchor in that broader build out, since the permit includes room to relocate leachate and gas systems, although the execution burden rises as management also contends with integration risks, interest coverage, and recent earnings volatility.
Casella Waste Systems' current narrative ties to analyst expectations that revenues could reach US$2.5b and earnings US$92.3m by 2029. This implies 9.2% yearly revenue growth and a very large increase in earnings from US$5.7m today to that 2029 consensus level.
Discover why Casella Waste Systems' fair value points to a 33% potential upside to its current price, which could narrow quickly.
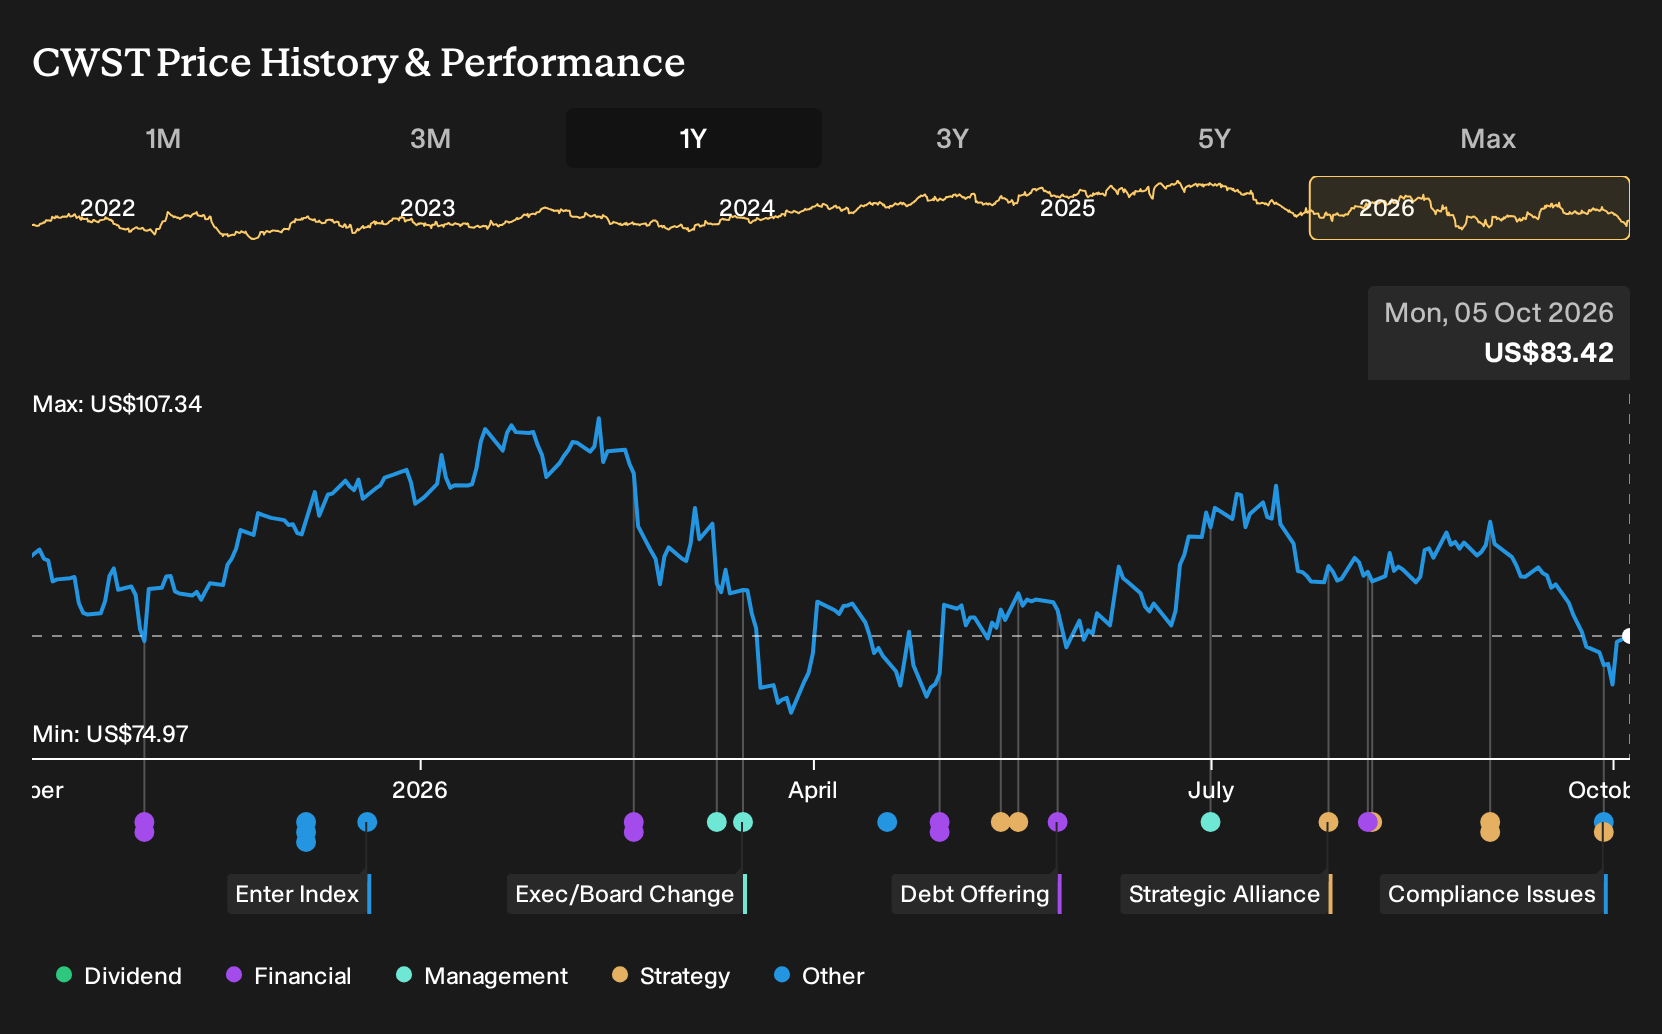
Exploring Other Perspectives
The Simply Wall St Community currently offers two fair value views on Casella Waste Systems, ranging from US$111 to about US$157.75 per share. Those figures predate the Hakes permit, so you should weigh them against fresh risks around integration and margins, along with potential volume and infrastructure catalysts, then compare several viewpoints before deciding how this story fits your portfolio.
Explore another Casella Waste Systems fair value estimate, including one that suggests it could be worth just $111.00!
Reach Your Own Conclusion
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Casella Waste Systems research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Casella Waste Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Casella Waste Systems' overall financial health at a glance.
Looking for more investment ideas beyond Casella Waste Systems?
If the Casella Waste Systems story has sharpened your thinking about capacity, balance sheets, and execution risk, use that same lens to scan a wider field of potential opportunities with the Simply Wall St Screener.
- For investors who want quality on sale, review companies that combine fundamentals with valuation support using our 27 high quality undervalued stocks.
- If capital preservation and smoother drawdowns matter most to you, focus on businesses that score well on stability and financial resilience with the 31 resilient stocks with low risk scores.
- To widen your watchlist with underfollowed ideas, filter for lesser known businesses with strong underlying metrics by checking the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com