


- In late September 2026, DISA Global Solutions launched a Built on Workday pre employment screening app, created with Everforth TopBloc, that embeds background checks and drug testing directly into Workday Recruiting to streamline hiring and support compliance.
- Everforth also reported an expanded Microsoft partnership that unifies its commercial and federal go to market and concentrates more than 1,500 Microsoft certifications around AI, cloud and security work. This collaboration could reshape how the business wins and delivers large modernization projects.
- We will now look at how Everforth's deeper Microsoft collaboration could reshape its investment narrative around AI led consulting execution.
Everforth Investment Narrative Recap
Everforth appeals to investors who buy into an IT services group leaning hard into AI, cloud and cybersecurity consulting, backed by ecosystem partners rather than pure staffing. The short term hinge remains whether healthier commercial trends, the Quinnox contribution and cost programs translate into cleaner earnings after past one off items and still thin 2.1% margins.
The primary operational risk is execution against a busy backlog while carrying debt that is not well covered by operating cash flow. If award timing, contract ramp and federal billings do not line up cleanly, free cash flow could stay tight and keep pressure on both reinvestment capacity and balance sheet flexibility.
The expanded Microsoft collaboration is the clearest tie in to Everforth’s AI focused narrative. A unified commercial and federal go to market model, backed by more than 1,500 Microsoft certifications and all three partner designations across AI, cloud and security, directly supports the consulting heavy mix that analysts already focus on.
For catalysts, this alliance matters because it feeds higher complexity modernization work in cloud, data and cybersecurity that can be co sold, repeatable and margin accretive if delivered well. Execution missteps, staffing constraints or delays on these large programs would quickly show up in utilization, earnings quality and sentiment around Everforth’s long term AI story.
Everforth Earnings And Valuation Expectations
Everforth's consensus story is built around modest growth rather than a moonshot. Analysts are working off an assumption that revenue expands by 2.4% a year over the next three years, while earnings today sit at US$83.0 million and are projected to reach US$143.4 million by 2029. That implies an earnings increase of about US$60 million, with the 2029 forecasts anchored to a revenue line of US$4.3b and tied to a P/E multiple of 9.9x on those projected profits.
Uncover why Everforth's fair value indicates a 24% potential downside to its current price, which leaves little room for error.
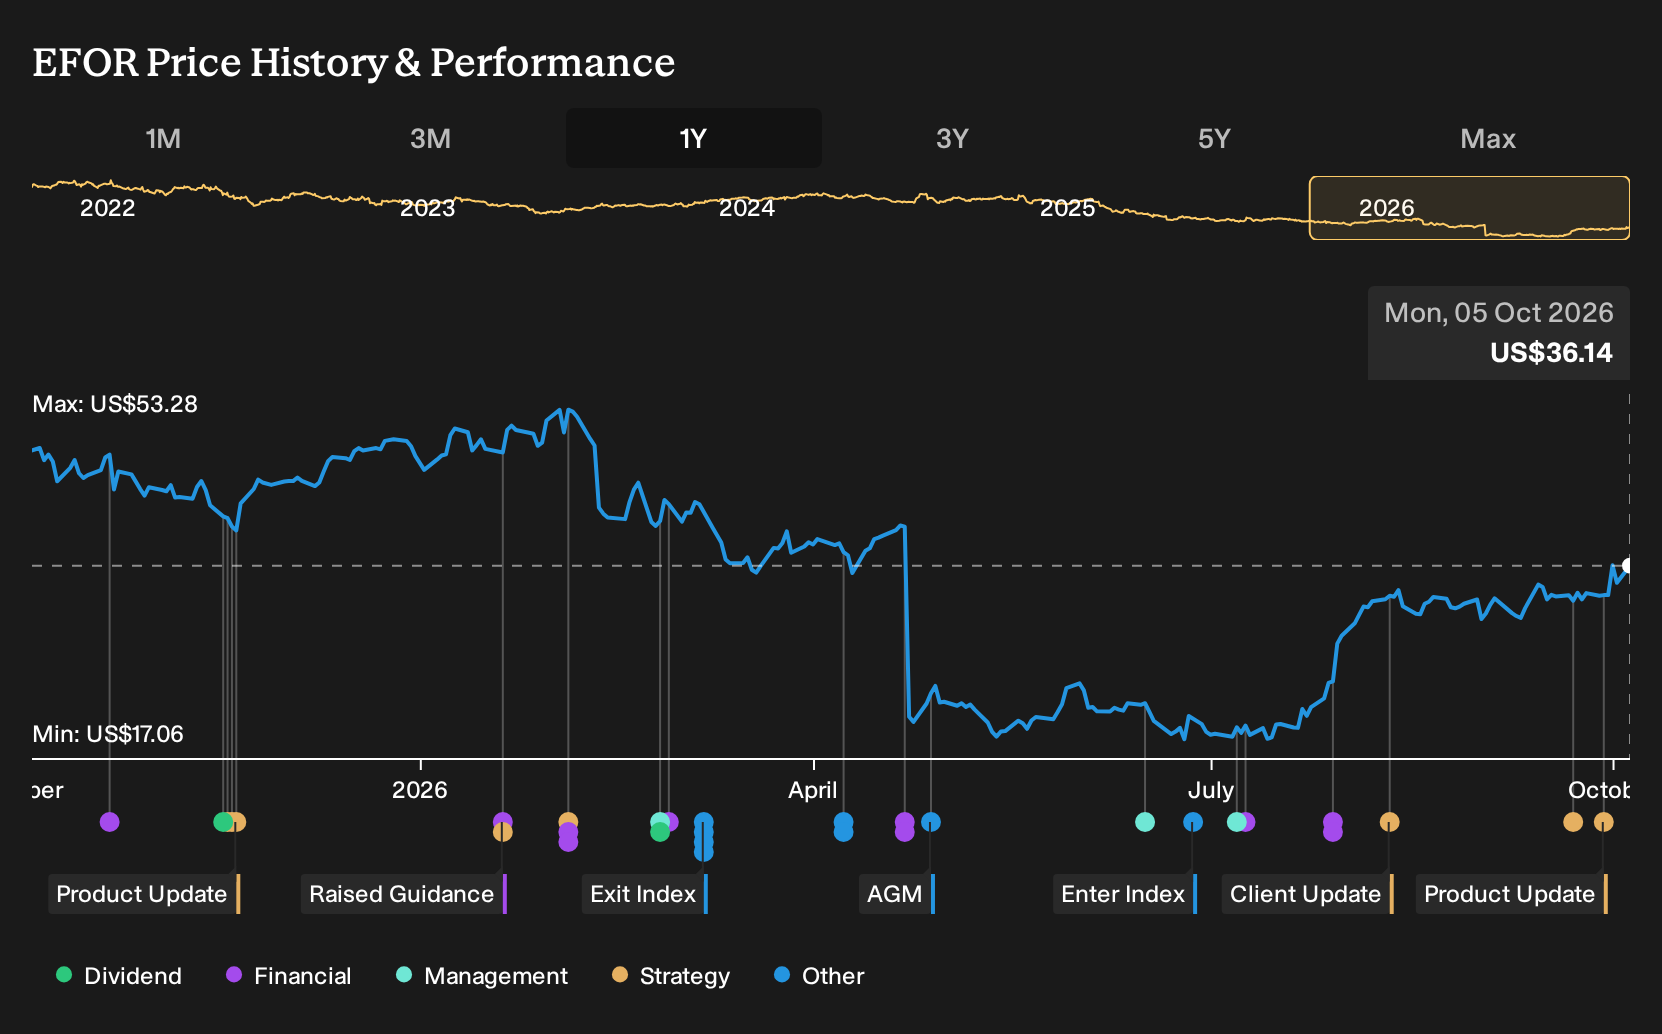
Exploring Other Perspectives
For Everforth, the bullish twist is all about earnings power. The most optimistic analysts were penciling in US$4.4b of revenue and US$218.9 million of earnings by 2029 before this Workday screening app news. You can see how that more upbeat view might shift; treat this as a cue to compare several competing narratives yourself.
Explore another Everforth fair value estimate, including one that suggests as much as 77% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Everforth research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Everforth. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Everforth's overall financial health at a glance.
Looking For More Investment Ideas Beyond Everforth?
Once you have a view on Everforth, it can be useful to widen the lens and compare it with other companies that have different risk, income and valuation profiles using the Simply Wall St Screener.
- If capital preservation sits high on your checklist, you could start with a set of companies that score well on balance sheet strength through our list of solid balance sheet and fundamentals (25 results).
- Investors who focus on income can aim to keep cash flow coming in by reviewing a curated group of higher-yield payers in the 7 dividend fortresses.
- Those looking for under followed opportunities can broaden their watchlist by scanning a 19 high quality undiscovered gems that pairs solid fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com