


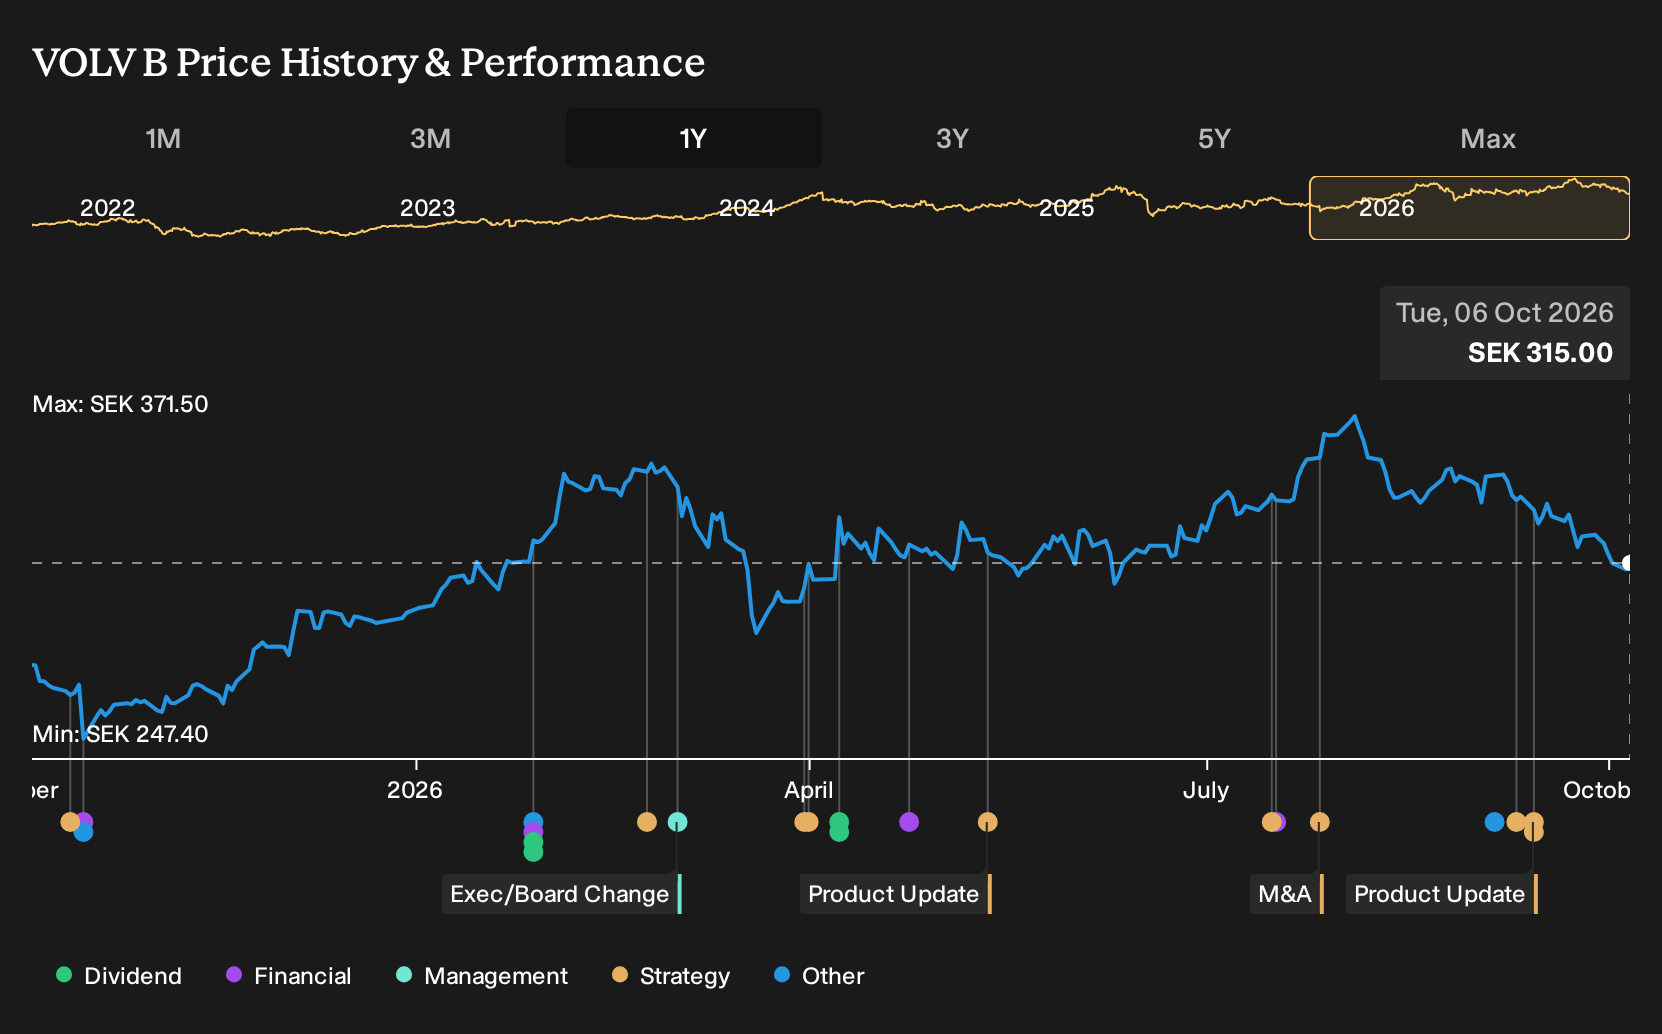
If AB Volvo was on your watchlist instead of in your portfolio, the result may feel like a missed shot. For AB Volvo shareholders, the return over the past year was 21.6%, including dividends. That outcome raises a simple question. What information could have helped you judge, back on 6 October 2025, whether the push into electric trucks and software-heavy, service-led transport would meaningfully change how this business earns its money?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind AB Volvo. Zero in on 185 high quality undervalued stocks for companies trading below our estimates.
The Argument AB Volvo Investors Were Really Weighing
The shares cost SEK276 at the start of the period, and you had to decide whether AB Volvo was quietly reshaping its profit engine or walking into a margin squeeze.
The bullish narrative put fair value at SEK300. It leaned on faster electrification and digitalisation, with projects like the Coretura software platform expected to support higher-margin services and more stable earnings.
The bearish view pointed to a fair value of SEK240. It focused on rising regulation and tariffs, and the risk that slower zero-emission adoption and one-off impairments would drag on net margins.
What The Results Changed For The AB Volvo Case
The clearest test of the AB Volvo story came from the Q2 2026 report. Revenue moved from SEK122,896m to SEK126,273m, while net income excluding extra items went from SEK7,412m to SEK10,371m and net margin rose from 6.0% to 8.2%. That mix of higher sales and a thicker margin supported the optimistic argument that the earnings engine could strengthen.
The takeaway is simple. When a thesis leans on better business quality, focus on whether net margin and service-heavy income move together. For any other industrial, check if the margin trend and segment mix actually line up with the promised shift toward higher-return activities before trusting the story.
What AB Volvo's One Year Run Now Asks Of You
AB Volvo shares trade at SEK315 after a 21.6% gain over the past year. The selected Narrative’s Fair Value sits below the current price, which means its author sees today’s quote as baking in more optimism than their own model supports.
The Narrative leans on tight order books, services and electrification progress while flagging cost pressure, regulation and capital intensity. The live question for anyone paying SEK315 is whether Volvo can keep growing higher margin services fast enough to offset battery, labor and tariff costs tied to running both electric and legacy engine operations.
"Structural cost inflation in batteries, raw materials, and labor remains a persistent threat as Volvo is forced to concurrently maintain costly legacy operations and invest in capital-intensive electrification and automation initiatives, placing ongoing pressure on cost structure and net margin expansion over the coming decade."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Beyond AB Volvo's Trucks
AB Volvo is betting on smarter, more electric transport. You might look one step away. What keeps those connected fleets reliably talking to each other?
Moving freight on software heavy platforms creates a different bottleneck. Data has to move quickly between servers, storage and applications.
Another business focuses on the high speed networking gear and software that handle that traffic for cloud, AI and enterprise systems.
Its tools help customers build flexible, programmable networks rather than rigid, proprietary ones.
As AI workloads spread, that role could quietly gain importance for many operators.
One Narrative has put that dependency into a written case. → See the AI infrastructure company one Narrative values 16% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com