


- Tenet Healthcare has issued US$2b of 6.250% senior notes due 2034, with the proceeds intended to redeem US$1.5b of 5.125% secured notes due 2027 and US$500m of 6.125% notes due 2028, reshaping its long term debt stack.
- This refinancing moves Tenet Healthcare toward longer dated unsecured borrowing while leaving room for additional indebtedness, which affects future flexibility for hospital investments, ambulatory surgery center expansion and ongoing share repurchases.
- We will look at how Tenet Healthcare's longer dated 2034 notes reshape its investment narrative around leverage, cash flow and flexibility.
Compare Tenet Healthcare's balance sheet reset with a curated set of hospital and health providers that also prioritize resilient funding and headroom for growth using our list of solid balance sheet and fundamentals (25 results).
Tenet Healthcare Investment Narrative Recap
To own Tenet Healthcare, you need to be comfortable with a hospital and ambulatory surgery operator that leans on higher acuity procedures, technology driven cost efficiencies and active capital deployment. The thesis hinges on the business converting that case mix and efficiency focus into resilient cash generation while payer mix shifts and Medicaid program exposure stay manageable.
The new 6.250% 2034 notes slightly extend Tenet Healthcare's runway rather than change the immediate story. In the short term, the bigger swing factor remains hospital performance as exchange volumes move into uninsured and bad debt risk rises. The main operational threat is that payer mix and policy driven Medicaid timing could squeeze margins faster than cost actions can offset.
The 2034 issuance ties directly into earlier capital plans that earmarked more than US$300m for USPI M&A in 2026 and US$1.36b already spent on buybacks, with a further US$2b authorized. That playbook leans on steady free cash flow from hospitals and ambulatory centers to service debt and still fund transactions and repurchases.
With the new notes largely used to refinance 2027 and 2028 bonds, Tenet Healthcare maintains financial flexibility for that M&A and buyback agenda while still carrying a high level of debt. For investors, the key question is whether operating trends in higher acuity procedures and technology driven savings remain sufficient to support that leverage and capital return pace.
Tenet Healthcare's current analyst narrative points to revenues of US$24.1b and earnings of US$1.6b by 2029, built on 3.3% yearly revenue growth and a projected earnings decline of US$600m from US$2.2b today.
Uncover why Tenet Healthcare's fair value indicates a 10% potential upside to its current price that could narrow quickly.
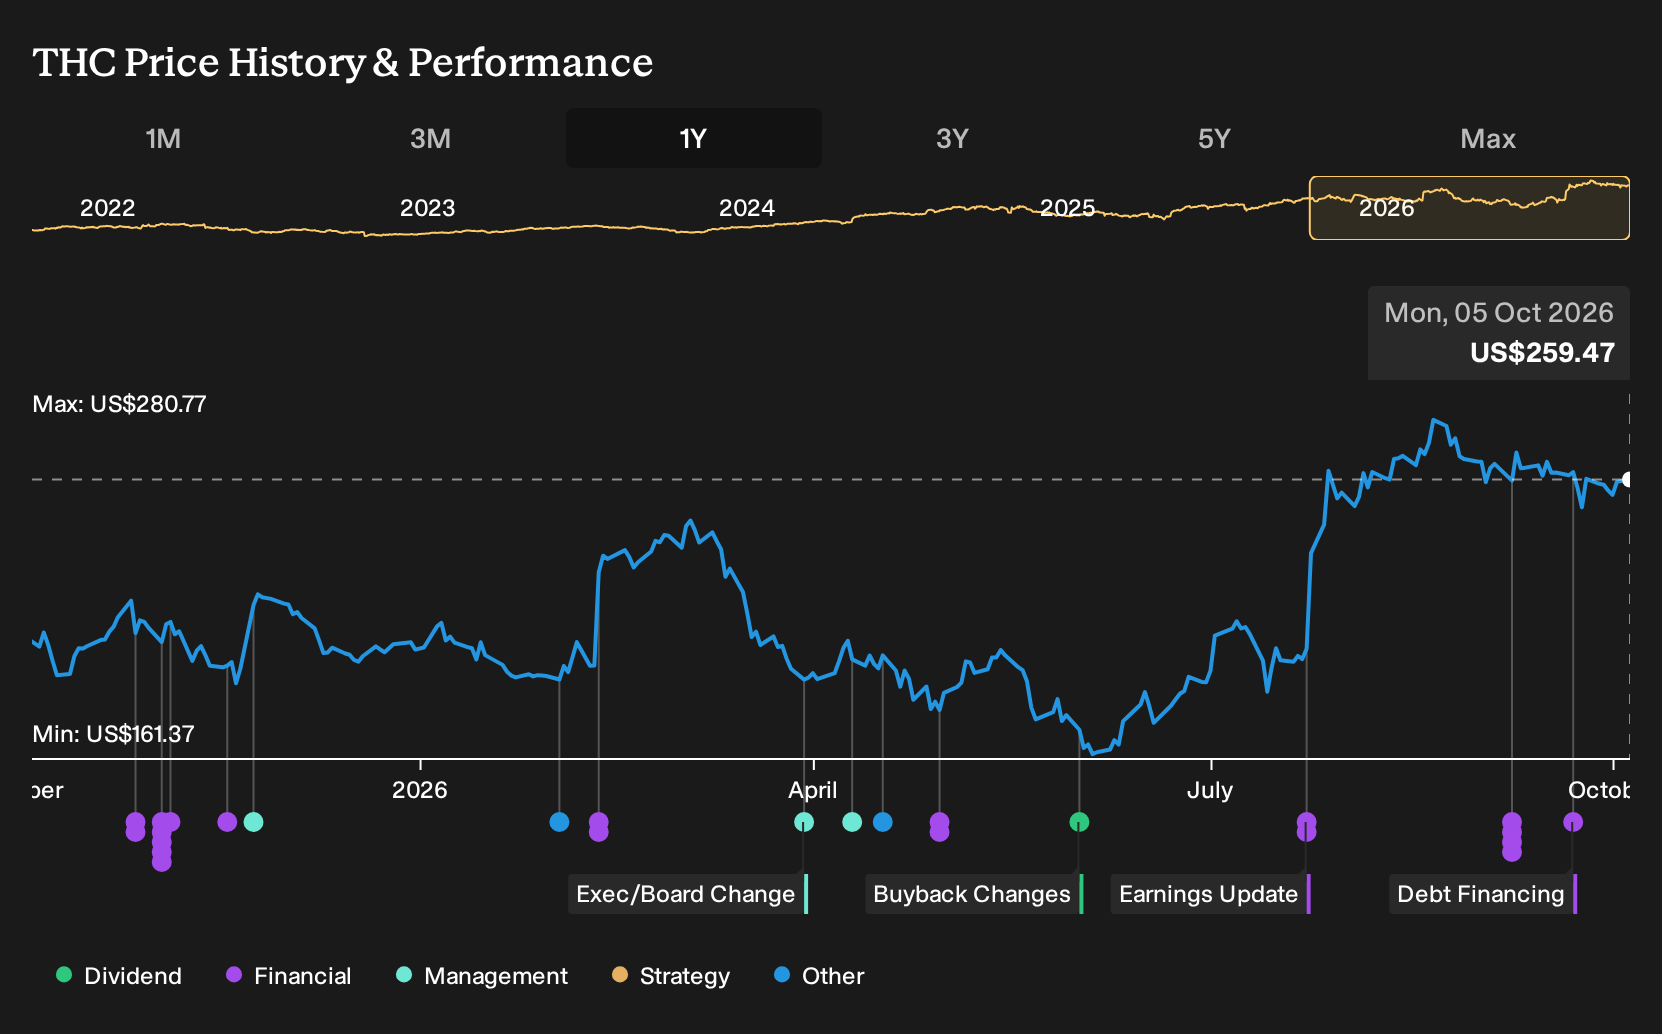
Exploring Other Perspectives
One alternate view focuses on Tenet Healthcare’s capital hunger as the real swing factor. The most optimistic analysts were already penciling in about US$25.0b of revenue and US$1.6b of earnings by 2029, before this new 2034 debt. You can treat those higher forecasts as a stress test on how much extra leverage you think the business can comfortably carry, and then explore how this refinancing might push those narratives in a different direction.
Explore 4 other Tenet Healthcare fair value estimates, including one that suggests up to 581% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tenet Healthcare research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Tenet Healthcare. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tenet Healthcare's overall financial health at a glance.
Looking for more investment ideas beyond Tenet Healthcare?
If you want to apply the same level of scrutiny used on Tenet Healthcare to a broader watchlist, the Simply Wall St Screener can help you quickly surface stocks that fit different risk and return profiles.
- For investors who want potential upside without ignoring quality, use the screener to hunt for companies in the 19 high quality undiscovered gems that might not be crowded yet.
- If capital preservation and a smoother ride matter most to you, narrow your universe to businesses in the 31 resilient stocks with low risk scores and see which ones fit your comfort level.
- Income focused investors can zero in on cash return potential by scanning for 7 dividend fortresses that match your yield and stability preferences.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com