


Denim-maker Levi Strauss & Co. (LEVI) will report its third-quarter earnings for fiscal 2026 tomorrow, Oct. 7, after the market closes. Ahead of that, analysts expect its profit to climb 5.9% year-over-year (YoY) to $0.36 per diluted share. The company has also topped estimates in each of the trailing four quarters.
CEO Michelle Gass believes the company’s core consumers are proving to be resilient, despite the impact of higher gas prices. In the second-quarter results, two-thirds of the quarter’s sales growth came from units, not just higher prices. The company would like to continue the winning streak in the third quarter as well.
Let's take a look at Levi Strauss ahead of its results.
About Levi Strauss Stock
Levi Strauss & Co. is a global apparel company headquartered in San Francisco, California. Founded in the mid-nineteenth century, it designs, markets, and sells jeans, casual apparel, and related accessories for men, women, and children under brands including Levi’s, Beyond Yoga, and Levi Strauss Signature. The company has a market capitalization of $7.8 billion.
Its operations span product design, sourcing from independent contract manufacturers, distribution, wholesale partnerships, e-commerce, and company-operated retail stores. The company sells its products across a broad international footprint through physical stores, department stores, shop-in-shops, and online channels. Levi Strauss is among the world’s largest brand-name apparel companies and a leading player in jeanswear.
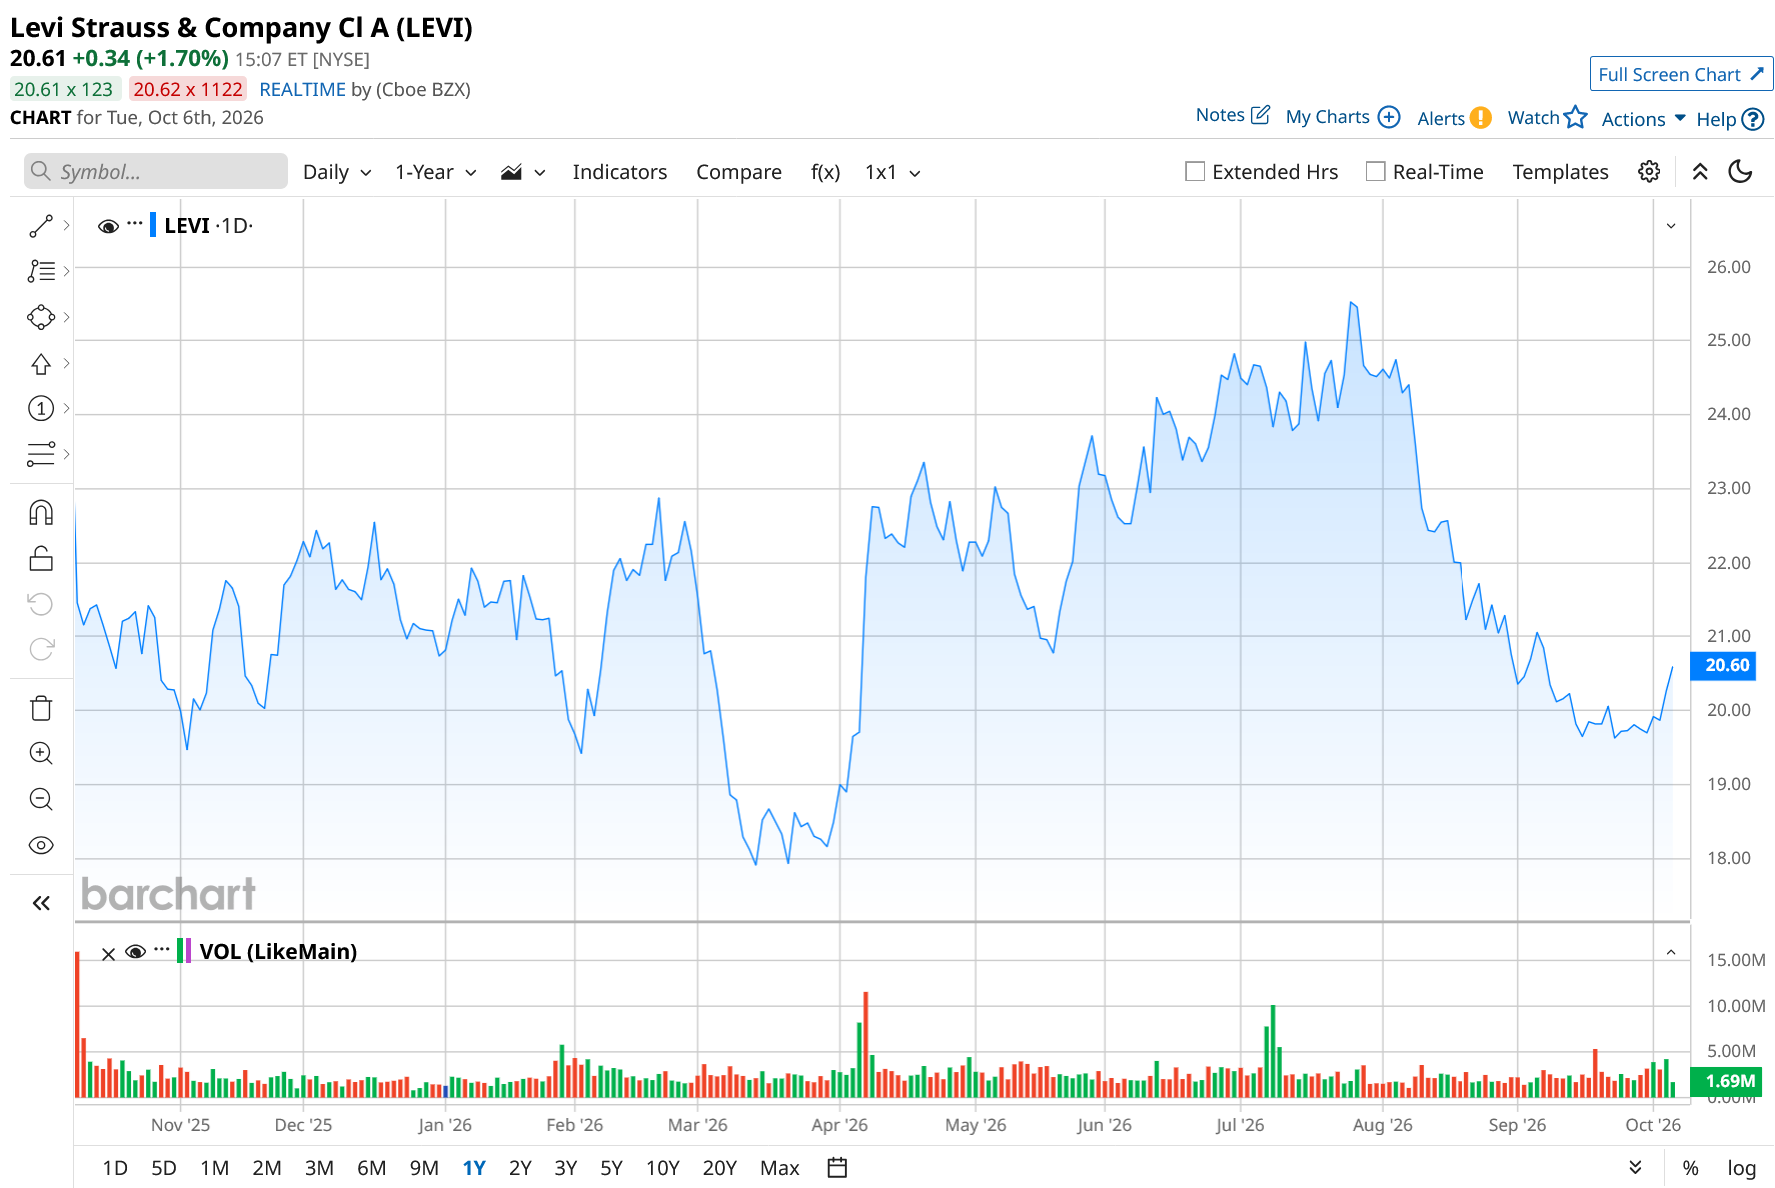
Levi’s stock is down 15% over the past 52 weeks mainly because investors have become more cautious about its forward earnings power, even though recent operating results have been solid. Over the past three months, the stock has dropped 17% amid persistent tariff, currency, and consumer-spending concerns. It reached a 52-week high of $25.70 on July 28, but is down 20% from that level.
Periodic selloffs have kept Levi’s valuation in check. On a forward-adjusted basis, its price-to-earnings (P/E) ratio of 13.17x is lower than the industry average of 14.51x.
Topped Q2 Estimates, Raised Full-Year Outlook as Premium Denim Demand Held
Levi’s is transitioning into a DTC-first denim lifestyle company with a larger addressable market, leading to faster growth and higher profitability. The company’s total revenue for the second quarter of fiscal 2026 (quarter ended May 31) increased 8% YoY, or 5.7% organically, to $1.56 billion (higher than the $1.52 billion LSEG consensus analyst estimate).
Asia remains a growth center, with 11.9% YoY organic revenue growth. However, due to a shift in shipments from Q1 FY2025 to Q2 FY2025 for a distribution center transition, organic revenue in Europe dropped marginally YoY. In the Americas, growth remained solid, increasing 6.8% organically.
The DTC segment is also driving growth, with revenue up 10.8% YoY to $793.60 million, or 8.4% organically. Total Levi’s brands net revenue increased 7.8% from the prior-year period to $1.52 billion.
Levi’s topline growth also drove profitability gains through gross margin expansion and SG&A leverage. Its adjusted EBIT margin grew from 8.3% to 9%, while adjusted EPS climbed 27.3% YoY to $0.28 (higher than the $0.24 LSEG estimate).
Based on these results, Levi Strauss raised its fiscal 2026 guidance. Levi raised its annual net revenue growth guidance from 5.5%-6.5% to 7%-7.5%, while it raised its organic revenue growth forecast from 4.5%-5.5% to 5.5%-6%. The company raised its adjusted EPS guidance from $1.42-$1.48 to $1.46-$1.52, despite assuming U.S. tariffs on imports from China remain at 30% and the rest of the world at 20%. Levi also raised its dividend rate by 14% to $0.16 per share.
Wall Street analysts are optimistic about Levi’s future earnings. For fiscal 2026, EPS is projected to surge 14.9% annually to $1.54, followed by an 11% growth to $1.71 in fiscal 2027.
What Do Analysts Think About LEVI Stock?
Analysts at BTIG Research reiterated their stance on LEVI stock with a “Buy” rating and a $27 price target. On the other hand, Citigroup analysts maintained a “Neutral” rating and cut the price target from $25 to $22.
This month, Jefferies analysts maintained a “Buy” rating on Levi but lowered the price target from $27 to $25. The firm’s analysts expect solid third-quarter results, with full-year profit guidance moving modestly higher, supported by the company’s impressive gross profit margin, but the revenue outlook is largely expected to be reiterated amid stubborn inflation. However, near-term sentiment could remain a bit volatile.
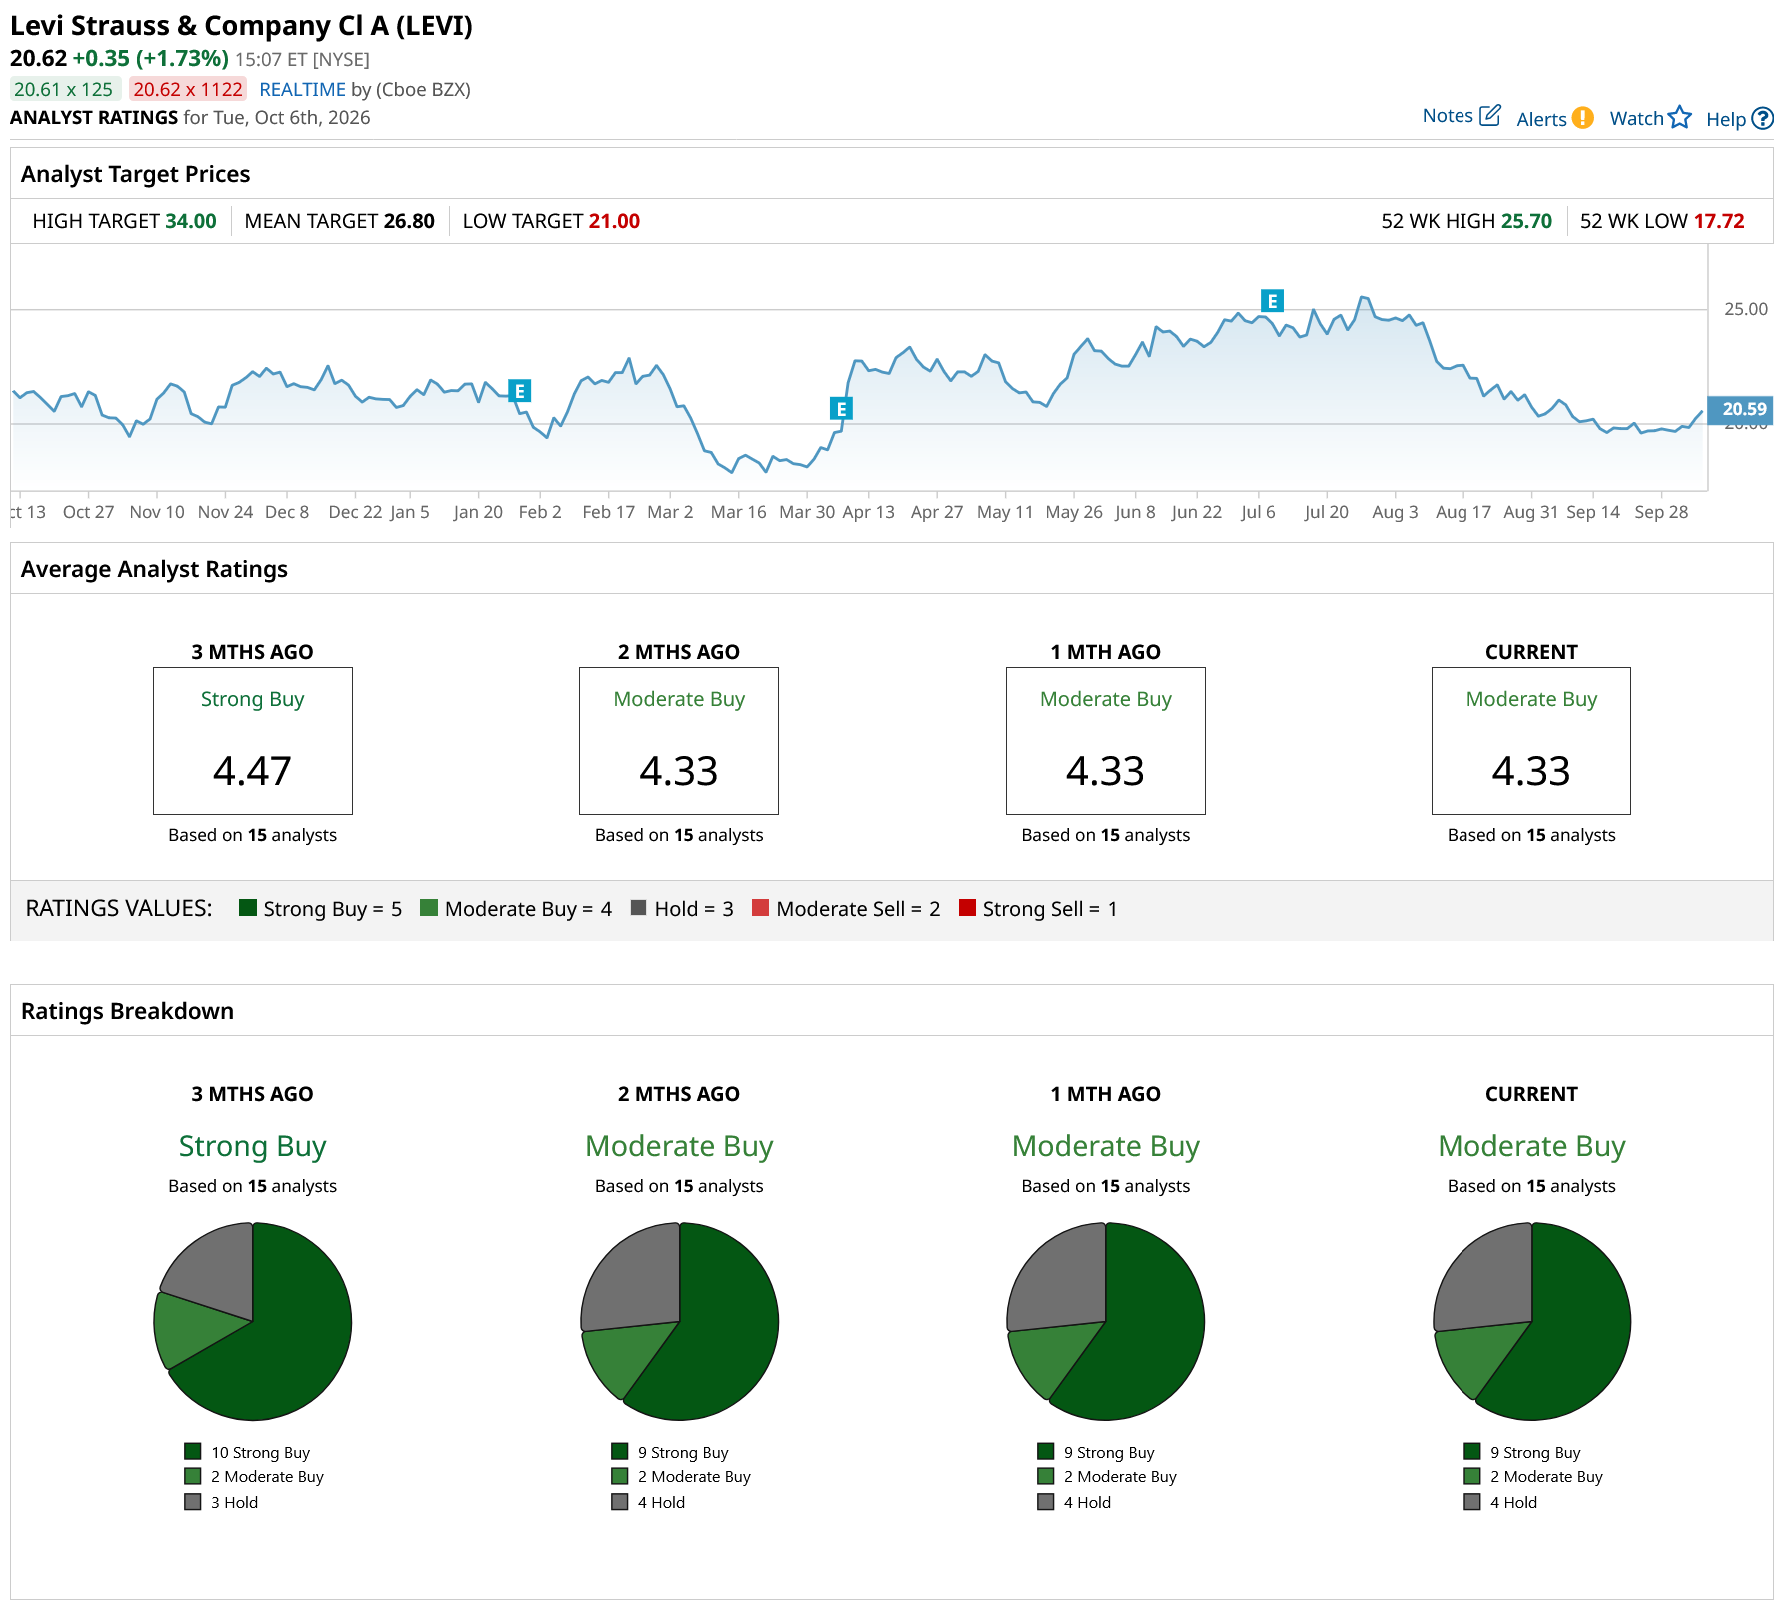
Wall Street analysts are soundly bullish on LEVI stock, with a consensus “Moderate Buy” rating. Of the 15 analysts rating the stock, a majority of nine analysts have given it a “Strong Buy” rating; two analysts suggested “Moderate Buy,” while four analysts are playing it safe with a “Hold” rating. The consensus price target of $26.80 represents 30% upside from current levels. Moreover, the Street-high price target of $34 reflects a 65% upside.
On the date of publication, Anushka Dutta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.