


Chugai Pharmaceutical (TSE:4519) is back in focus after Roche halted obesity trials for emugrobart and returned the rights to Chugai. The company is now preparing to restart development for spinal muscular atrophy.
The emugrobart update lands after a tough stretch for Chugai Pharmaceutical’s shares, with the 30-day share price return down 9.93% and the 90-day move down 16.68%. However, the 3-year total shareholder return is up 43.71% and the 5-year figure is up 74.49%, suggesting longer term holders have still seen meaningful gains despite the recent loss of momentum.
Scan how Chugai Pharmaceutical compares with other research driven healthcare players by reviewing our hand picked 10 healthcare AI stocks in the same broad space.
Bulls point to Chugai Pharmaceutical’s resilient multi year returns and solid recent revenue and net income growth. Bears focus on the emugrobart setback and share price slide. Which story does the current valuation support?
Most Popular Narrative: 0% Overvalued
Chugai Pharmaceutical closed at ¥6,120, essentially in line with the most followed narrative fair value of ¥6,100, which frames today’s debate around how much pressure future pricing and competition might create.
Heavy reliance on a narrow portfolio of blockbuster products leaves the company increasingly vulnerable to abrupt volume and pricing declines, as competitive threats intensify and major products lose market exclusivity. This makes future revenue streams highly uncertain.
Chugai's mid and late-stage R&D pipeline has shown mixed progression, with project discontinuations and ongoing delays in bringing new drugs to market. This creates a tangible risk of a future pipeline gap that will weaken long-term earnings momentum and reduce high-value new product launches.
See why 3 investors see Chugai Pharmaceutical as 0% overvalued.
Result: Fair Value of ¥6,100 (ABOUT RIGHT)
Still, Chugai Pharmaceutical could surprise if demand for Hemlibra or Tecentriq stays firm and the AI collaboration with Phylo accelerates drug discovery progress.
Find out about the key risks to this Chugai Pharmaceutical narrative.
Another View: Chugai Pharmaceutical Through A DCF Lens
A different yardstick tells a very different story on Chugai Pharmaceutical. Our DCF model points to a future cash flow value of ¥10,945.2 per share, which is well above the current ¥6,120 price. That gap suggests investors are heavily discounting the long term cash generation implied by this model. Is that caution justified or excessive?
Look into how the SWS DCF model arrives at its fair value.
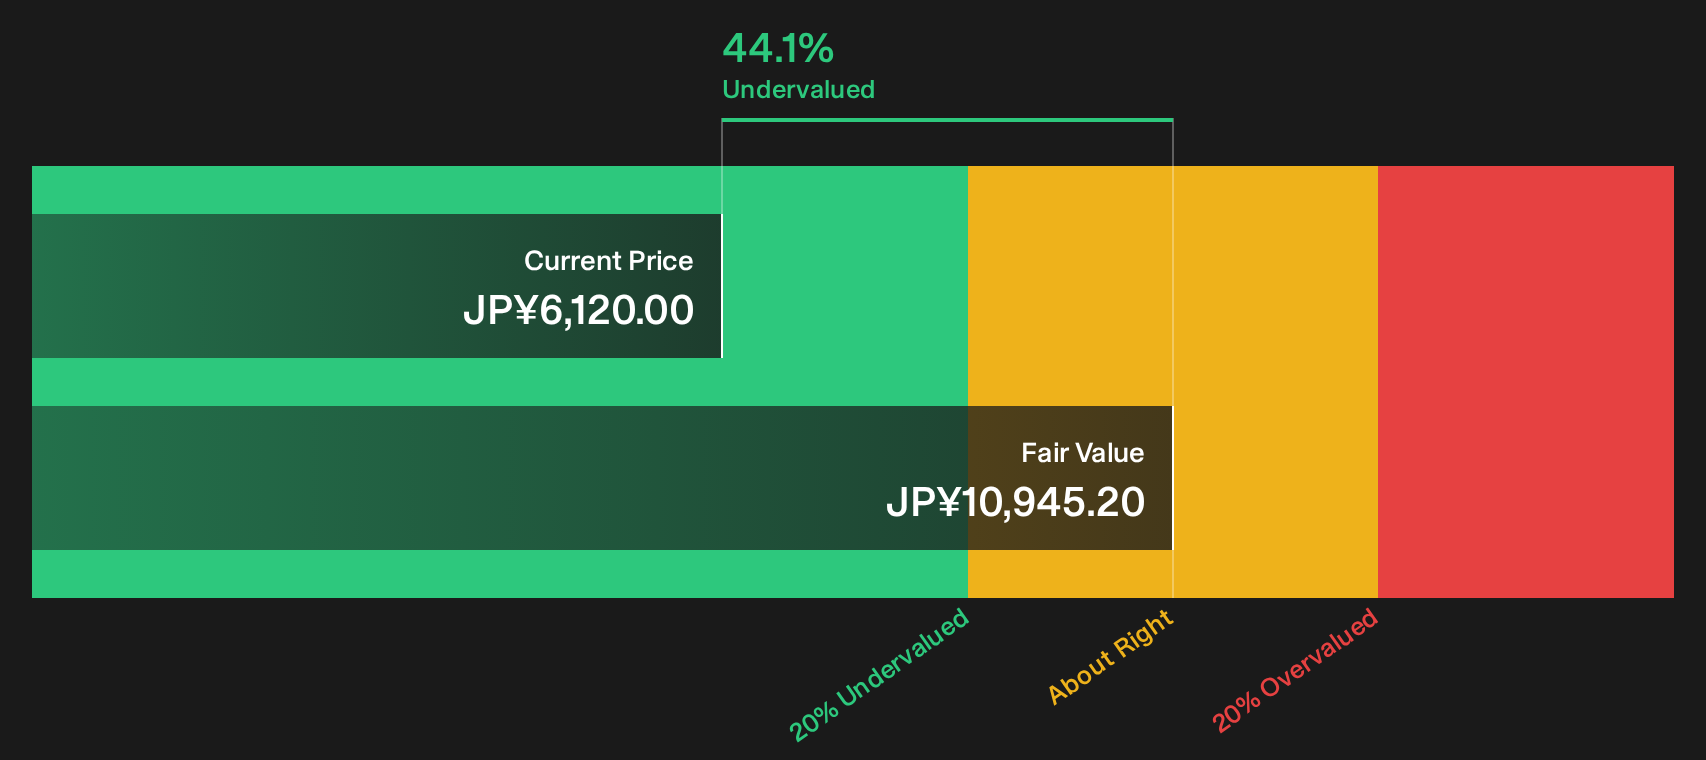
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Chugai Pharmaceutical for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Chugai Pharmaceutical can easily pull you in opposite directions, so it is important to move quickly, review the full picture, then weigh the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Chugai Pharmaceutical?
Do not stop at one stock. Broad, consistent opportunity usually comes from scanning multiple angles, comparing business quality, and building a watchlist that fits your own risk comfort.
- Target resilient compounding potential by focusing on companies that look attractively priced on fundamentals through our 14 high quality undervalued stocks.
- Strengthen your income stream by reviewing a curated set of businesses offering higher yields in the 21 dividend fortresses.
- Dial down portfolio risk by concentrating on financially healthier candidates using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com