


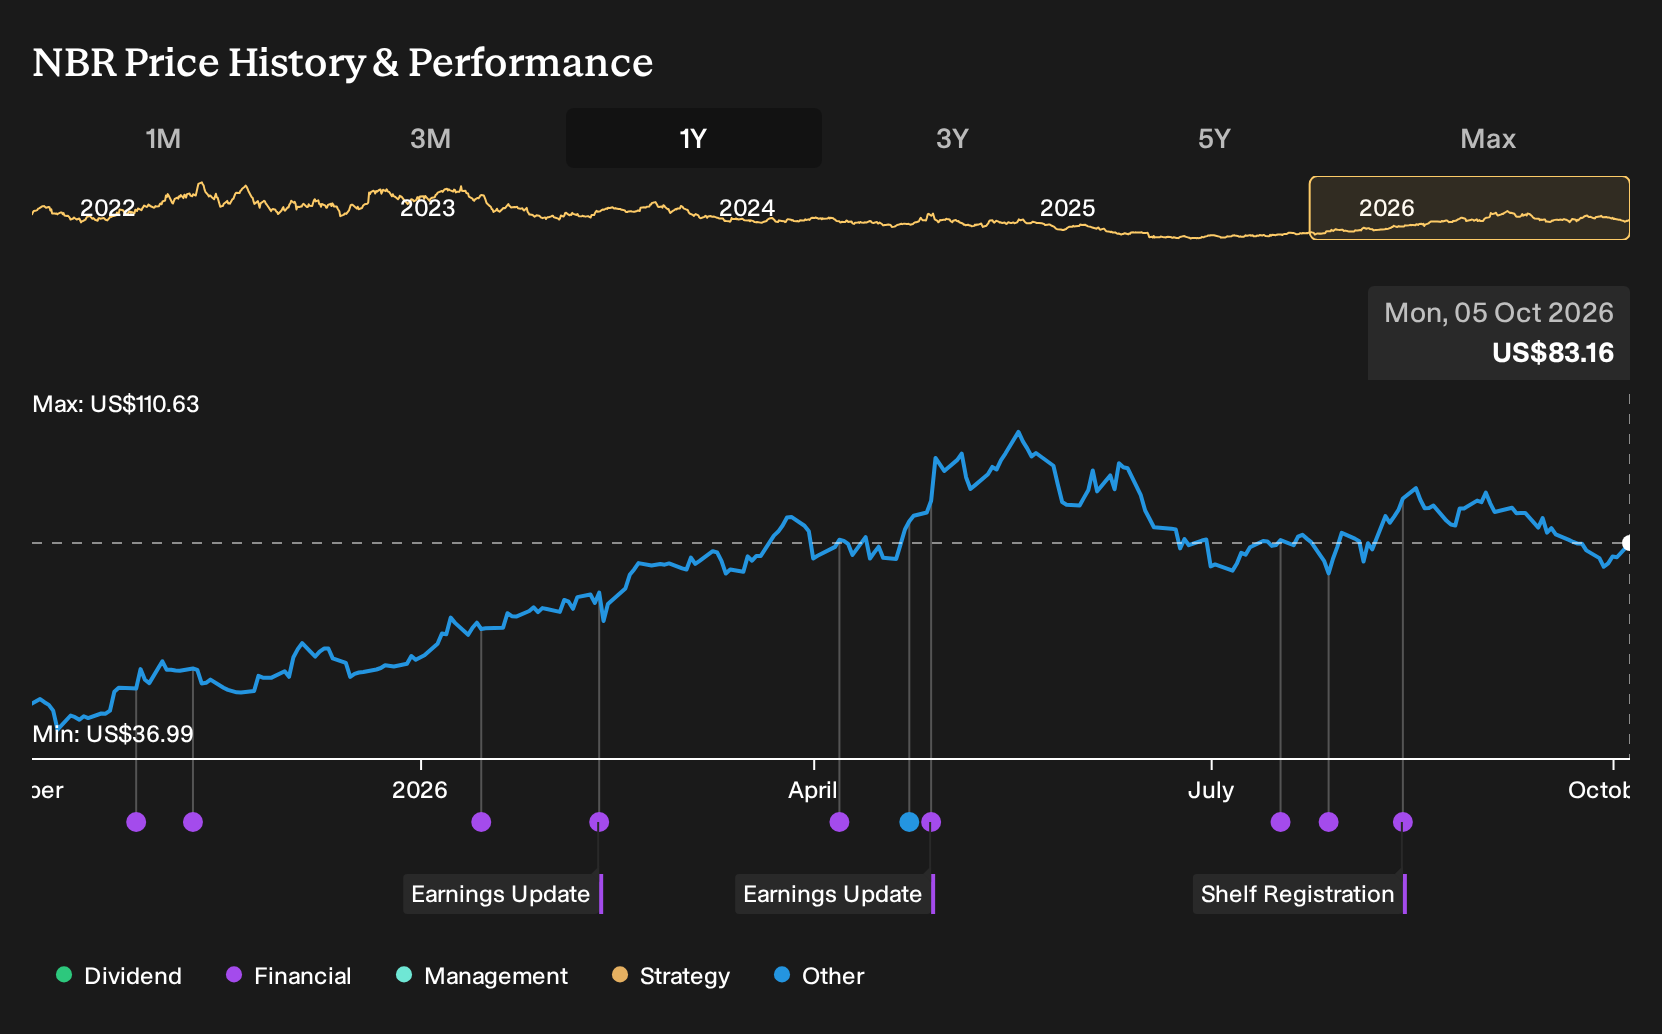
If one event captured what Nabors Industries was trying to become, it was the framework agreement to drill Project Obsidian, the first superhot geothermal plant, where Nabors secured exclusive drilling work and a 14% stake in Quaise Energy. Investors who held Nabors Industries over the past year are up 86.5%, including dividends. If you were deciding on 5 October 2025, what did you need to believe about rigs, technology and debt for that bet to feel sensible?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Nabors Industries has already moved. Pinpoint other ways to investigate the theme among 19 nuclear energy infrastructure stocks.
The Two Nabors Industries Stories Investors Had To Weigh
The shares cost US$42.78 at the start of the period, and anyone considering Nabors Industries had to choose between two very different but plausible stories.
The bullish narrative put fair value at US$50, built on 6.9% yearly revenue growth and a shift from a loss to a 7.0% profit margin, helped by high margin drilling technology and modular rigs.
The cautious narrative pointed to fair value of US$37.44, stressing high debt and ongoing margin pressure, even while assuming global energy demand kept rig activity and automation projects in play.
What The Results Changed For Nabors Industries
The key test for Nabors Industries was whether rigs and technology could offset balance sheet strain. Project Obsidian moved forward as Quaise closed a US$180 million Series B and granted Nabors exclusive drilling work, which favored the bullish, tech-led story. Reported Q2 2026 figures showed revenue slipping to US$814.8 million while the loss narrowed and net margin improved from -4.6% to -3.6%, so profitability remained unproven. Overall, the evidence cut both ways.
The lesson is simple. When a thesis leans on high margin tools and modular rigs overcoming debt, it can be helpful to track segment margins and net leverage alongside contract wins, rather than focusing only on headline revenue or share price movements.
What Nabors Industries' Recent Run Now Assumes
Nabors Industries trades at US$83.16 after a one year gain of 86.5%. The selected Narrative places its Fair Value below that price, reflecting concern that fossil fuel drilling economics and balance sheet progress may not fully offset longer term industry headwinds.
The Narrative leans on questions about renewables policy, shale cyclicality, talent costs and global competition. A buyer today is effectively assuming Nabors can keep rigs busy and margins resilient. How does that square with the source argument on structurally lower hydrocarbon demand and tighter carbon rules?
"The accelerating global transition to renewable energy and enhanced decarbonization targets are expected to structurally lower long-term demand for hydrocarbon drilling services, directly constraining Nabors Industries'' revenue growth as their core oil and gas customer base contracts. Heightened worldwide regulation and the introduction of more aggressive carbon pricing on fossil fuel extraction will significantly increase operational costs for oilfield service providers, eroding Nabors'' net margins and compressing profitability over time."
One Narrative disagrees with today's price. → See where this Narrative says Nabors Industries should trade
Where Nabors' World Connects Next
If Nabors Industries is your rig and drilling bet, another link matters. What keeps all that produced gas reliably moving to users?
Once wells are flowing, pressure rarely stays cooperative or predictable over time. Gas often needs heavy compression just to reach midstream systems and power plants.
One specialist business focuses on owning and running that compression hardware. It builds, operates and services large horsepower units under extended contracts.
The physics stay simple: shifting reservoir or delivery pressures demand more compression work. That translates into more equipment on the ground, quietly doing essential lifting.
If the drilling story matters to you, this compression layer could shape how much gas ultimately reaches end users.
That argument has a Narrative and a number behind it. → See the company one Narrative values 49% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com