


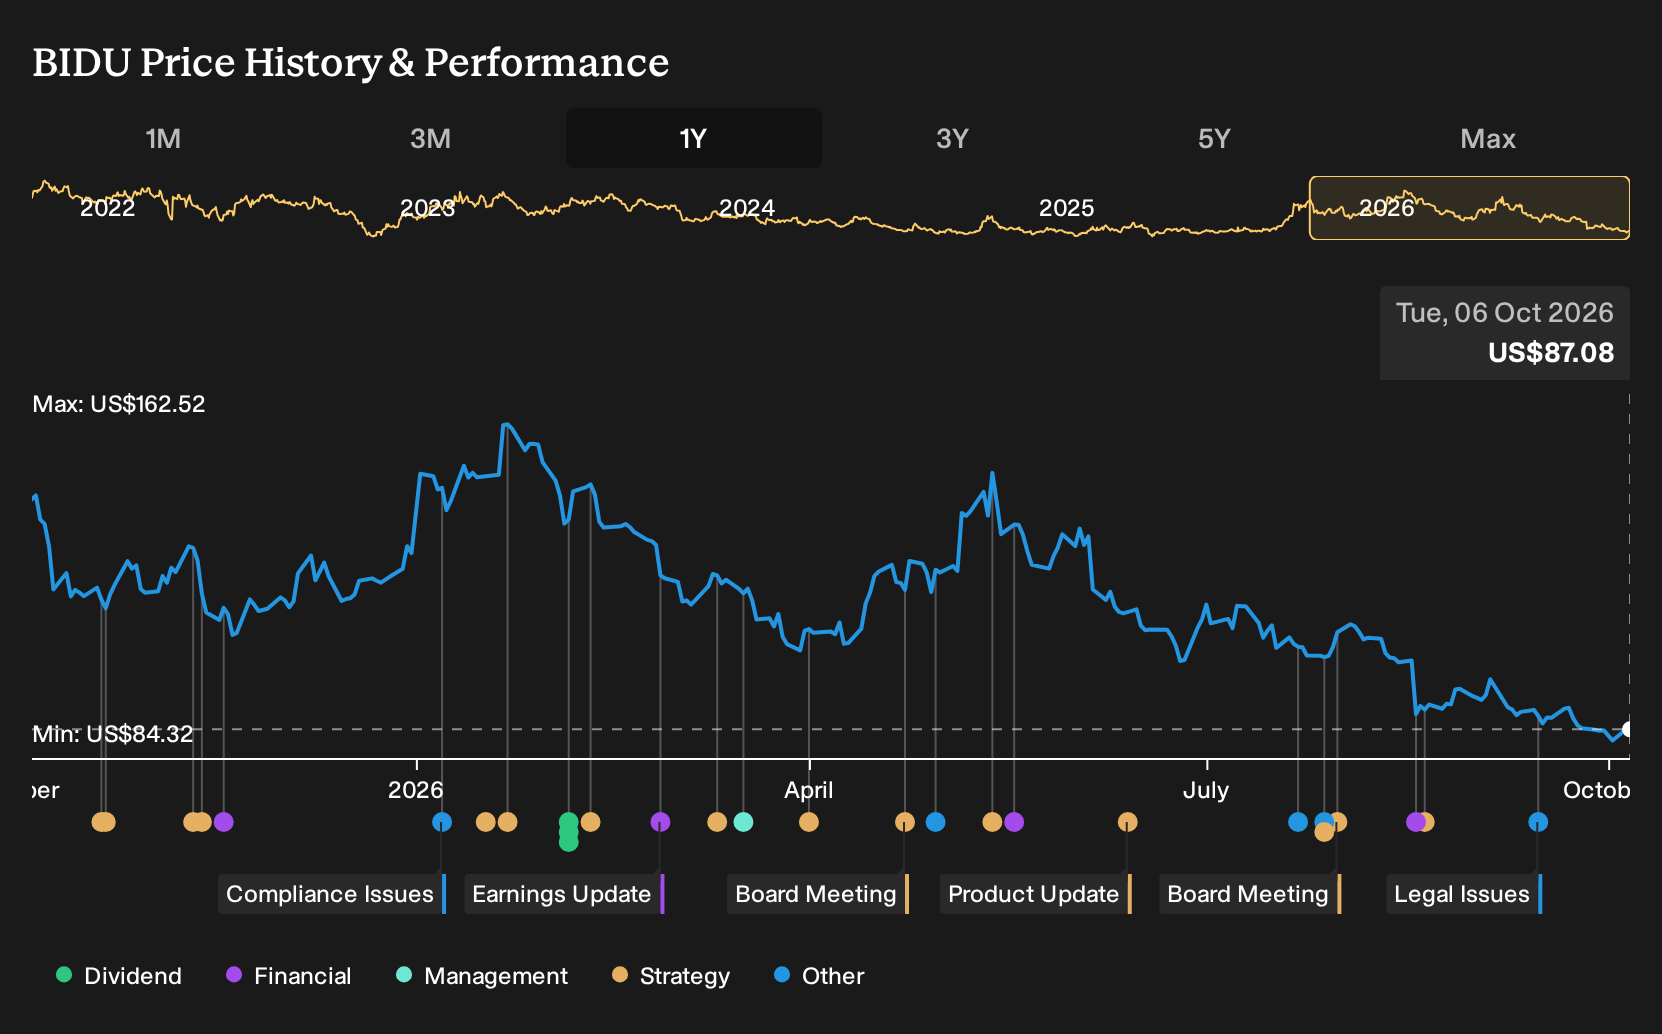
- Bernstein Liebhard LLP reported that a shareholder filed a securities class action against Baidu over alleged materially false and misleading disclosures about business operations, growth prospects, and financial stability for investors who bought securities between November 18, 2025 and August 17, 2026.
- The lawsuit directly targets how Baidu described its fundamentals, which matters for investors assessing AI investment spending, monetization timing, and overall financial resilience.
- This raises questions about how Baidu's investment narrative around AI driven growth is tested by allegations of misleading disclosures on fundamentals.
Broaden your options by comparing Baidu with other companies facing intense scrutiny on fundamentals, using our hand picked 31 resilient stocks with low risk scores as a potential reference point.
Baidu Investment Narrative Recap
To own Baidu today, you need to believe its heavy AI spending in search, cloud and autonomous driving can eventually turn an unprofitable internet platform into a healthier earnings story. The core question is whether AI search and AI cloud can compensate for weaker traditional online marketing and support more stable margins over time.
The securities class action focuses on past disclosures rather than operations. Unless it triggers regulatory action or distracts leadership, the near term catalyst still sits in clearer progress on AI monetization and cash flow. The main risk remains execution. High R&D spend and negative free cash flow leave little room for missteps if AI products underperform.
This lawsuit ties directly into how Baidu described its business health during a period when online marketing revenue had already declined 15% year over year and AI monetization was described as early stage. That makes any upcoming commentary on cost discipline, project based AI cloud revenue and profit timing especially important for investors watching cash burn.
No new operational announcements have been flagged alongside the legal filing. The most relevant disclosures remain management's own guidance that margins and revenue are under considerable pressure while AI initiatives scale. Your focus as a shareholder is whether future updates show improving free cash flow, steadier advertising trends and evidence that ERNIE, AI cloud and Apollo Go are progressing toward commercial scale.
Baidu's analyst narrative points to CN¥154.2b in revenue and CN¥16.2b in earnings by 2029, built on an expected 6.6% yearly revenue growth rate and a shift from today's reported earnings loss of CN¥4.6b to that future profit level. This implies an earnings swing of about CN¥20.8b over the period.
Uncover why Baidu's fair value indicates a 68% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Some bullish analysts focus on a different catalyst for Baidu. They point to AI driven services and Apollo Go reaching scale quickly, with forecasts before this lawsuit of CN¥187.7b in revenue and CN¥35.2b in earnings by 2029. That is far more optimistic than the consensus, and this legal action may yet reshape those assumptions.
Explore 6 other Baidu fair value estimates, including one that suggests the potential for as much as 135% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Baidu research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Baidu. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Baidu's overall financial health at a glance.
Looking for more investment ideas beyond Baidu?
Once you have a view on Baidu, it can help to cross check that thesis against other opportunities that line up with your risk tolerance, income needs and time horizon using the Simply Wall St Screener.
- If capital preservation is a priority, start with companies that historically show fewer financial red flags and review the 31 resilient stocks with low risk scores for a tighter focus on resilience.
- If value is the main angle, scan for strong fundamentals trading at what may be conservative expectations by checking the 27 high quality undervalued stocks for potential candidates.
- If income stability matters most, look at businesses that combine higher dividend yields with support from their balance sheets using the 7 dividend fortresses as your jumping off point.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com