


Why the latest Fonterra update matters for investors
Fonterra Co-operative Group (NZSE:FCG) has just combined a full year earnings release, fresh guidance for FY27 and both regular and special dividends, giving investors several new data points to reassess the stock.
The dairy group reported net income of NZ$1,346m for the year to July 31, 2026, with basic earnings per share of NZ$0.54 from continuing operations, alongside guidance of NZ$0.65 to NZ$0.85 per share for FY27.
At a share price of NZ$4.91, Fonterra Co-operative Group has logged a 14.99% 90 day share price return and a 22.75% year to date share price gain. The 44.81% one year total shareholder return and very large three and five year total shareholder returns suggest momentum has been building rather than fading around recent earnings, dividend and guidance announcements.
Scan beyond Fonterra Co-operative Group and compare this earnings and dividend story with other companies on our curated list of 185 high quality undervalued stocks.
Bulls point to Fonterra Co-operative Group’s higher earnings, richer dividend stream and upbeat guidance. Bears highlight the rapid share price run. Which story does the current valuation actually support?
Price-to-earnings of 8.7x for Fonterra Co-operative Group: Is it justified?
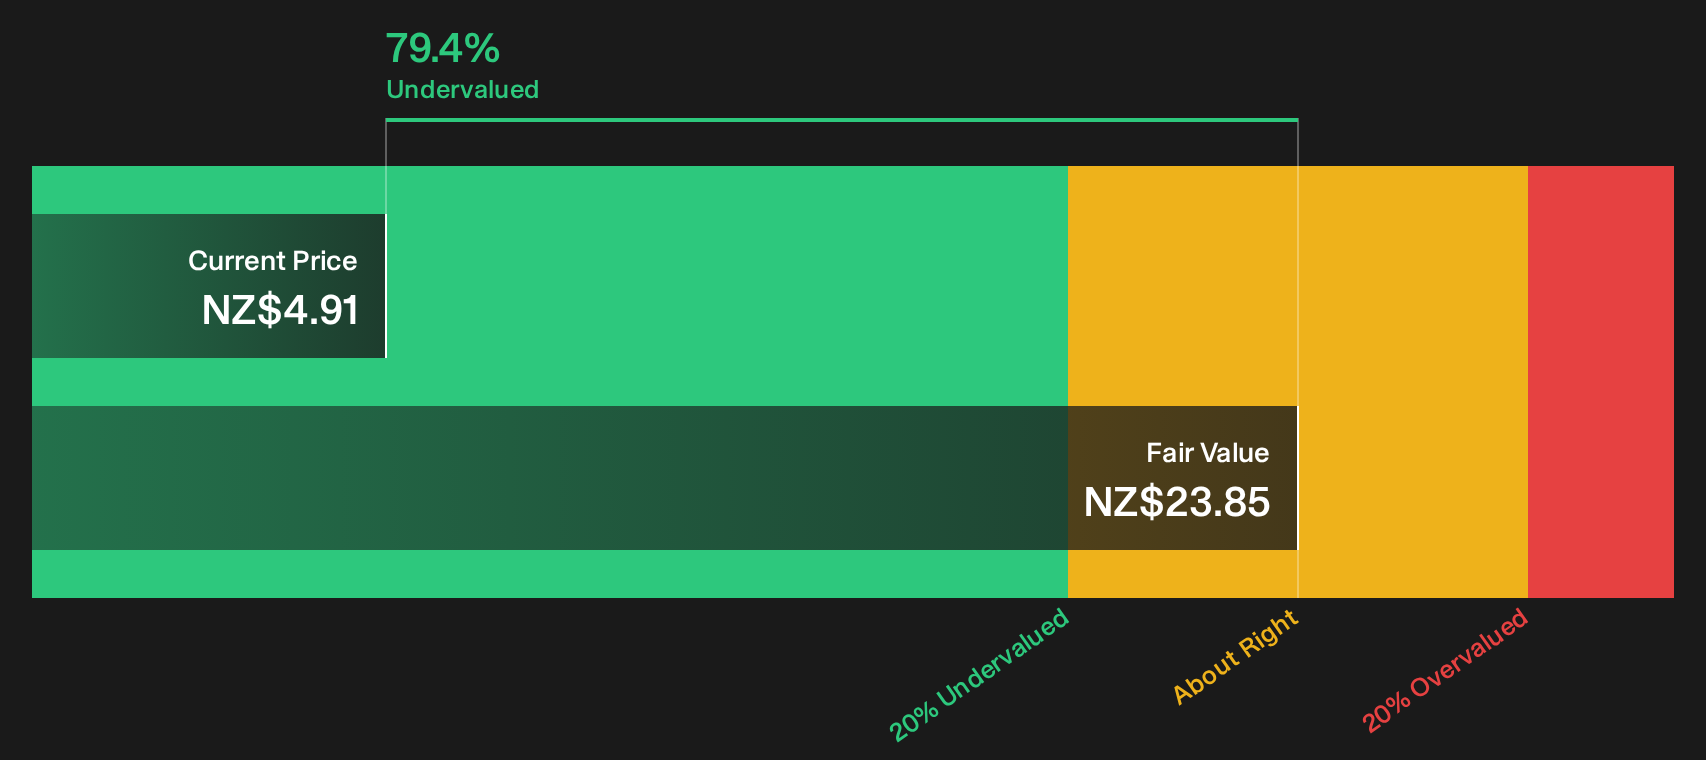
On the raw numbers, Fonterra Co-operative Group trades on a P/E of 8.7x at a share price of NZ$4.91, while our SWS DCF model points to a future cash flow value of NZ$23.85 that implies the stock is priced well below that estimate.
The P/E ratio compares what you pay per share with the earnings that Fonterra Co-operative Group generates per share. For a mature food producer with NZ$1,346m of net income and a long list of branded dairy products, this metric gives a quick sense of how the market is weighing current profits against the risks in the business.
Against that backdrop, the firm is described as trading at 79.4% below the internal fair value estimate, and its P/E of 8.7x sits well under both the Global Food industry average of 14.7x and the peer average of 15.6x. That gap suggests the market is assigning a significantly lower valuation to Fonterra Co-operative Group’s earnings than to comparable groups, even with its high 21.5% return on equity and a track record of earnings growth over the past five years.
The SWS DCF model adds another reference point by projecting future cash flows and discounting them back to today using a required return. For Fonterra Co-operative Group this results in a fair value estimate of NZ$23.85 against the current NZ$4.91 price. This framework focuses on the cash the business is expected to generate rather than just near term earnings multiples, and can be useful for investors who want a structured way to test whether today’s pricing aligns with their own expectations for the dairy group.
Look into how the SWS DCF model arrives at its fair value.
Result: Price-to-earnings of 8.7x (UNDERVALUED)
Still, the recent share price surge and reliance on dairy demand across regions like China and Asia mean any earnings setback could quickly challenge the Fonterra Co-operative Group story.
Find out about the key risks to this Fonterra Co-operative Group narrative.
Another view on Fonterra Co-operative Group’s value
The P/E discussion suggests Fonterra Co-operative Group looks inexpensive against peers. The SWS DCF model goes further, with a future cash flow value of NZ$23.85 per share versus the current NZ$4.91 price, indicating a much deeper undervaluation. If that gap narrows, which benchmark will matter more to you?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fonterra Co-operative Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 185 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of signals around Fonterra Co-operative Group point in different directions, so treat this as your prompt to move fast, review the full data set and decide where you stand. To weigh both the upside and the concerns in one place, take a close look at the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Fonterra Co-operative Group?
Do not stop with Fonterra Co-operative Group when there are other potential opportunities on your radar. Use the Simply Wall Street Screener to surface ideas that actually match your style, risk appetite and time horizon.
- Target dependable cash generators by reviewing companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (206 results).
- Hunt for mispriced opportunities by scanning our curated group of 185 high quality undervalued stocks that may align more closely with your return expectations.
- Spot potential outperformers early by scanning the 615 high quality undiscovered gems that the wider market may not yet be focused on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com