


REX American Resources (REX) has drawn investor attention after recent share price moves, with the stock last closing at US$44.04. Traders are weighing that valuation against the company’s ethanol focused revenue and earnings profile.
Recent trading has tilted in favour of REX American Resources, with a 1-day share price return of 1.45% and a 7-day gain of 3.40%, building on a 30-day increase of 6.22%, even though the 90-day move is down 7.26%.
For context, the share price return year to date sits at 35.93%, while total shareholder return over one, three and five years is 40.08%, 126.37% and 208.94% respectively. This indicates momentum that long term holders will likely view very differently from anyone focused only on the recent quarter.
Scan beyond REX American Resources and identify other momentum driven opportunities with strong fundamentals using our hand picked 27 high quality undervalued stocks.
After a sharp run and with REX American Resources trading at US$44.04, the gap between that price and fair value estimates is wide. Where does a reasonable valuation actually land within that range?
Preferred P/E of 12.1x for REX American Resources: Is it justified?
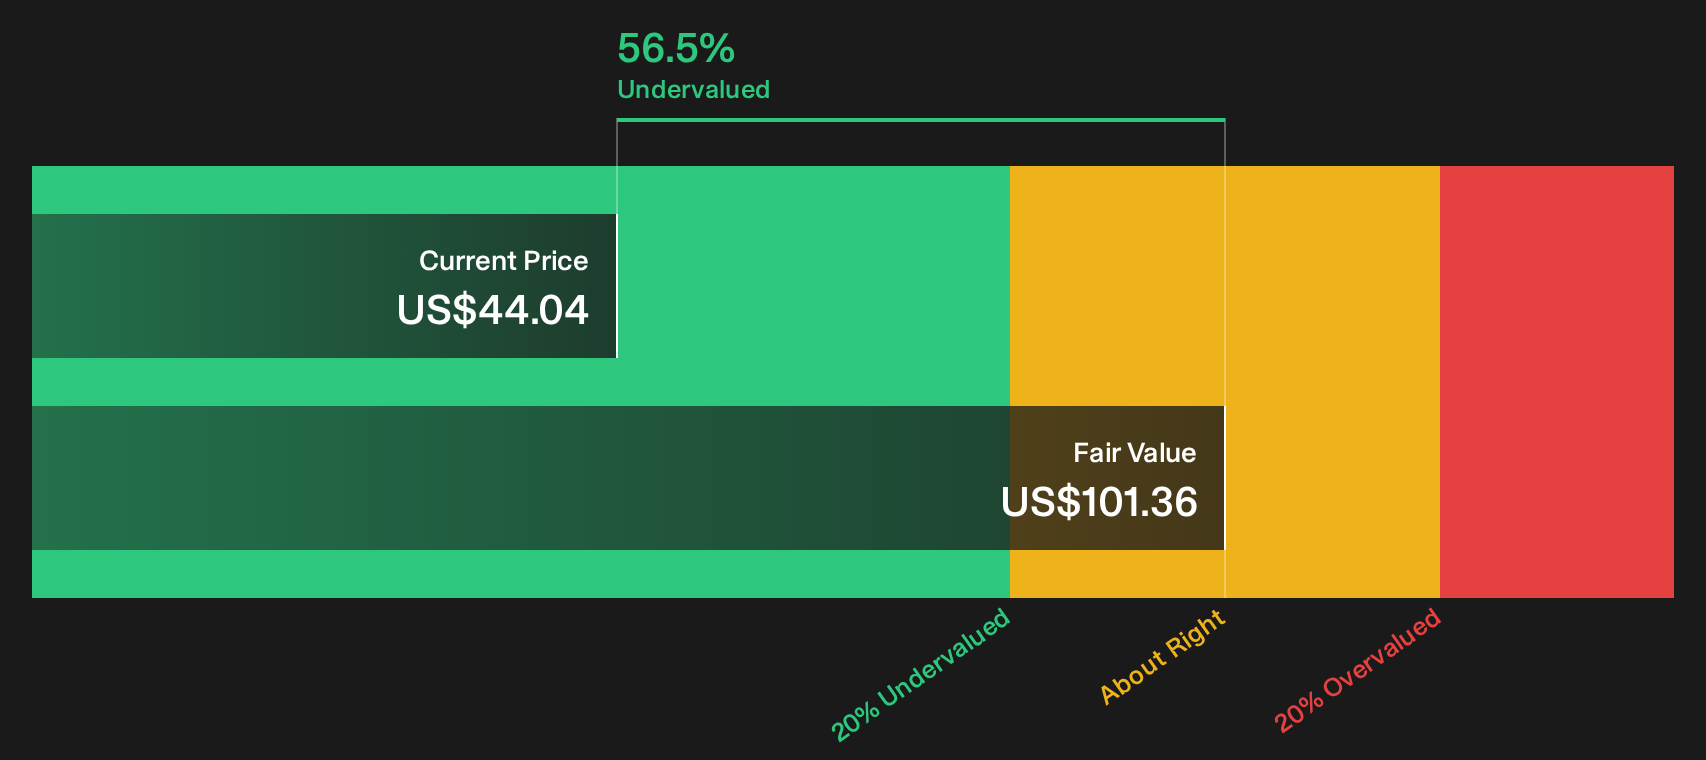
On simple earnings math, REX American Resources looks inexpensive, with a P/E of 12.1x against a last close of $44.04 and a DCF based fair value estimate of $101.36 suggesting a wide gap. That combination puts the current share price at a level where the market is paying a relatively low multiple for a business that is assessed as trading 56.5% below an internally modelled value.
The P/E ratio tracks how much investors are paying today for each dollar of profit, which is particularly useful for a producer like REX American Resources with an established earnings base. A 12.1x multiple is slightly lower than the 12.4x average for the broader US Oil and Gas sector and well below the 29.5x average for its peer group. This points to the market assigning a cheaper tag to REX American Resources earnings compared with both the industry and closer comparables.
That discount sits alongside several supporting fundamentals. Earnings grew by 134.6% over the past year, ahead of the 30.4% result for the Oil and Gas industry, while net profit margins of 18.3% compare with 7.9% a year earlier and are described as high quality. Return on equity of 17.8% is flagged as low against a 20% benchmark, and all liabilities are from higher risk external borrowing rather than customer deposits. As a result, the valuation is being set against a balance sheet and funding mix that carries some risk alongside that growth profile.
DCF work adds another layer. The SWS DCF model marks a future cash flow value of $101.36 per share versus the actual price of $44.04, and REX American Resources is described as trading at 56.5% below that estimate. That approach projects the company’s future cash generation and discounts those cash flows back to today, which can be helpful for a mature ethanol and by products producer where earnings and cash can be meaningful even without detailed external forecasts for revenue or profit growth.
Look into how the SWS DCF model arrives at its fair value using the Look into how the SWS DCF model arrives at its fair value..
Result: Preferred multiple of P/E 12.1x (UNDERVALUED)
Still, the REX American Resources narrative can be challenged if ethanol demand weakens, or if higher-risk external borrowing pressures future profitability and flexibility.
Find out about the key risks to this REX American Resources narrative.
Another view on REX American Resources valuation
There is also a cash flow lens to use for REX American Resources. The SWS DCF model points to a future cash flow value of $101.36 per share against a market price of $44.04. That gap suggests the stock is described as materially undervalued based on this method, but it is important to consider how comfortable you are with the assumptions baked into that cash flow curve.
To unpack those inputs and see exactly how the DCF result is built, take a closer look at the Look into how the SWS DCF model arrives at its fair value..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out REX American Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The valuation work around REX American Resources may sound compelling, but the real test is how the numbers line up with your own expectations. Take a moment to review the full picture of potential upsides through the 2 key rewards.
Looking for more investment ideas beyond REX American Resources?
If REX American Resources has sharpened your focus on valuation and quality, broaden your watchlist and give yourself more options for the next opportunity.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) that filters for financially robust businesses.
- Hunt for potential mispricing with the 27 high quality undervalued stocks that highlights financially strong companies trading at attractive levels.
- Spot underfollowed opportunities early using the 19 high quality undiscovered gems that surfaces quality businesses before they hit the mainstream.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com