


ON Semiconductor (ON) remains in focus after investors revisited the business following its latest financial disclosures and operational update, prompting fresh interest in how the three operating segments contribute to the current valuation.
ON Semiconductor’s recent disclosures have landed while momentum in the share price is rebuilding. The stock is up 13.64% over the past week and 16.04% over the past month, even after a 7.98% decline over the last 90 days.
At a share price of US$86.31, that rebound sits on top of a 52.22% year to date share price return and a 79.18% total shareholder return over one year. However, the three year total shareholder return of 7.51% lower shows that the longer journey has been far more uneven.
Capture ON Semiconductor’s momentum shift, then broaden your watchlist with hand picked 91 AI infrastructure stocks tied to the same power and data center themes driving attention today.ON Semiconductor now trades about 21% below the average analyst price target, while an intrinsic estimate points to a 12% premium. Is the market rewarding recent momentum or still pricing in risk?
Most Popular Narrative: 17% Undervalued
ON Semiconductor’s most followed valuation narrative places fair value at $103.69 against the latest close at $86.31. This frames the recent rally as a potential catch up move rather than froth and ties that gap directly to long term earnings expectations and discount rate assumptions of 12.02%.
The analysts have a consensus price target of $103.69 for ON Semiconductor based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $150.0, and the most bearish reporting a price target of just $75.0.
See why 123 investors see ON Semiconductor as 17% undervalued.
Result: Fair Value of $103.69 (UNDERVALUED)
Still, ON Semiconductor’s story can break if auto demand stays weak or if underused factories keep margins under pressure longer than the bullish narrative allows.
Find out about the key risks to this ON Semiconductor narrative.
Another View: ON Semiconductor Through The Cash Flow Lens
The popular story has ON Semiconductor trading below a US$103.69 fair value built around long term earnings forecasts. A different lens tells a cooler story. Our DCF model points to a future cash flow value of US$77.31, which puts the current US$86.31 price at a premium rather than a discount. Which set of assumptions do you find more convincing when real cash generation is the anchor?
Look into how the SWS DCF model arrives at its fair value.
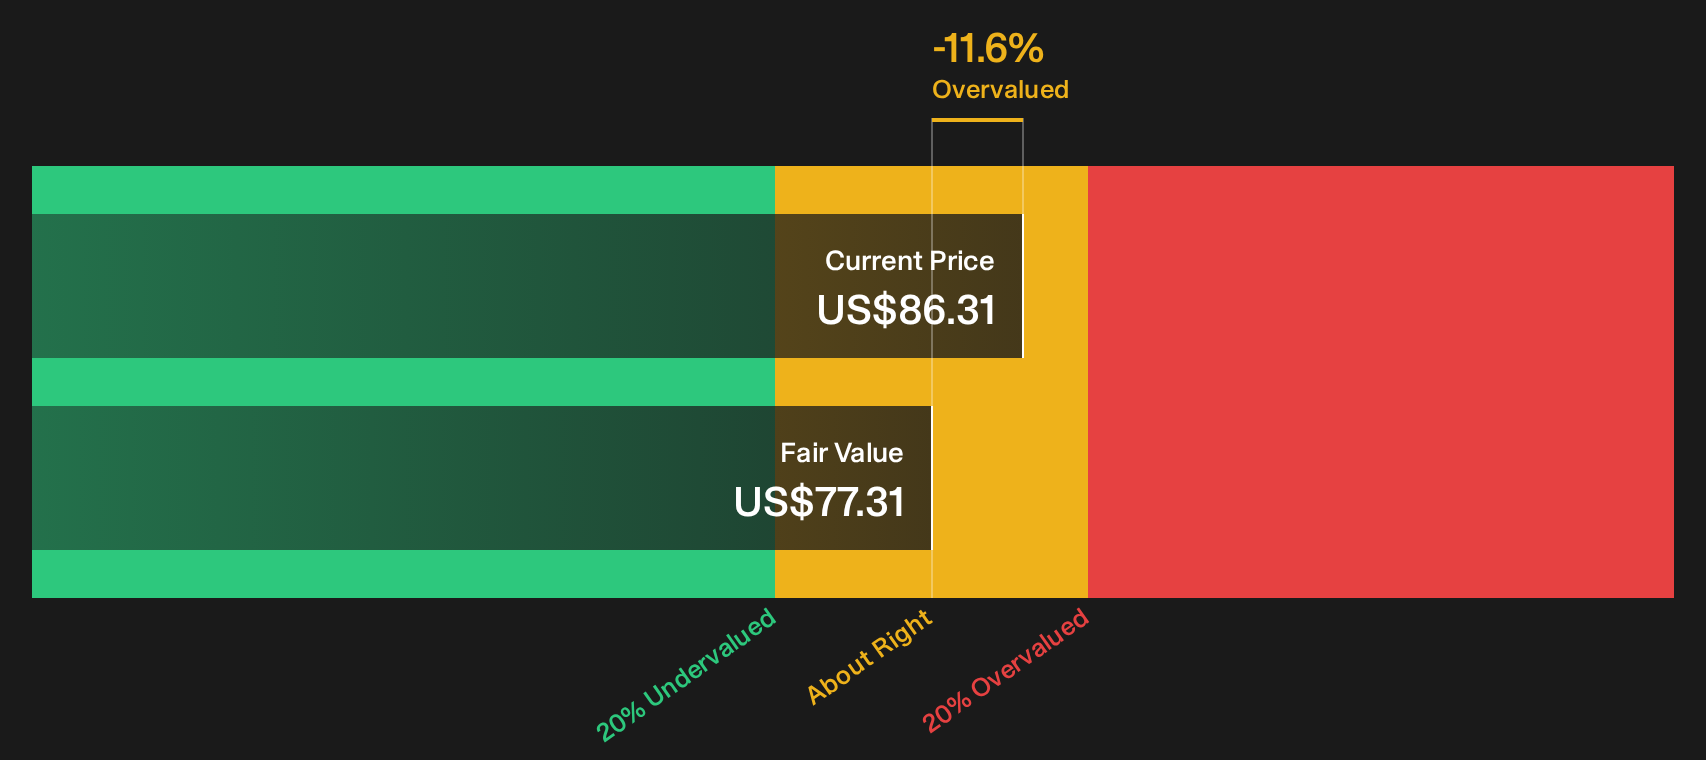
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ON Semiconductor for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals in ON Semiconductor’s story so far. Check the full data set, move quickly while sentiment is shifting, and weigh 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond ON Semiconductor?
ON Semiconductor might be front of mind today, but your next opportunity could be sitting in a completely different corner of the market.
- Target robust cash generators by scanning a 27 high quality undervalued stocks that combine quality fundamentals with prices that still sit below many investors’ radar.
- Build a steadier portfolio base by reviewing a list of solid balance sheet and fundamentals (25 results) that can help cushion tougher periods and reduce financial stress in your holdings.
- Hunt for tomorrow’s leaders early by checking out 19 high quality undiscovered gems before attention and capital crowd into the same familiar tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com