


Why Americas Gold and Silver is back in focus
Americas Gold and Silver (TSX:USA) has moved into the spotlight after management tied a six year global silver deficit to rising demand from artificial intelligence and electrification trends.
The miner is responding with heavier use of its Galena operation, including doubled hoisting capacity and plans to lift mill throughput, as it targets 3.2 million to 3.6 million ounces of silver output in 2026.
Recent attention on Americas Gold and Silver comes on top of a choppy share price pattern, with a 30 day share price return of down 14.4%, a 90 day share price return of up 6.5%, and a very large 3 year total shareholder return that signals longer term momentum.
Compare Americas Gold and Silver's AI driven silver story with hand picked peers powering similar trends through 36 elite gold producer stocks in the same space.
Americas Gold and Silver shares have pulled back over the past month but still show a very large 3 year total return. Does it make more sense to step in now or wait for a cleaner entry based on the numbers ahead?
Most Popular Narrative: 50% Undervalued
Americas Gold and Silver closed at CA$6.36, while the most followed narrative pegs fair value at CA$12.64 using a 7.88% discount rate. The gap between price and that modelled value is wide and invites closer scrutiny.
The company's growing exposure to silver (now 82% of revenue) aligns Americas Gold and Silver to benefit from increasing industrial and investment demand for silver in sectors like green technology and electronics, which could support higher realized prices and revenue growth.
The strengthening of the balance sheet via a $100 million term loan and premium-priced equity raise provides both stability and capital required for growth initiatives, reducing financial risk, supporting ongoing expansion efforts, and improving long-term earnings visibility.
See why 26 investors see Americas Gold and Silver as 50% undervalued.
Result: Fair Value of CA$12.64 (UNDERVALUED)
Still, that storyline can break if high all-in sustaining costs persist or if heavy use of debt and ongoing losses keep pressure on future equity value.
Find out about the key risks to this Americas Gold and Silver narrative.
Another View on Americas Gold and Silver's Value
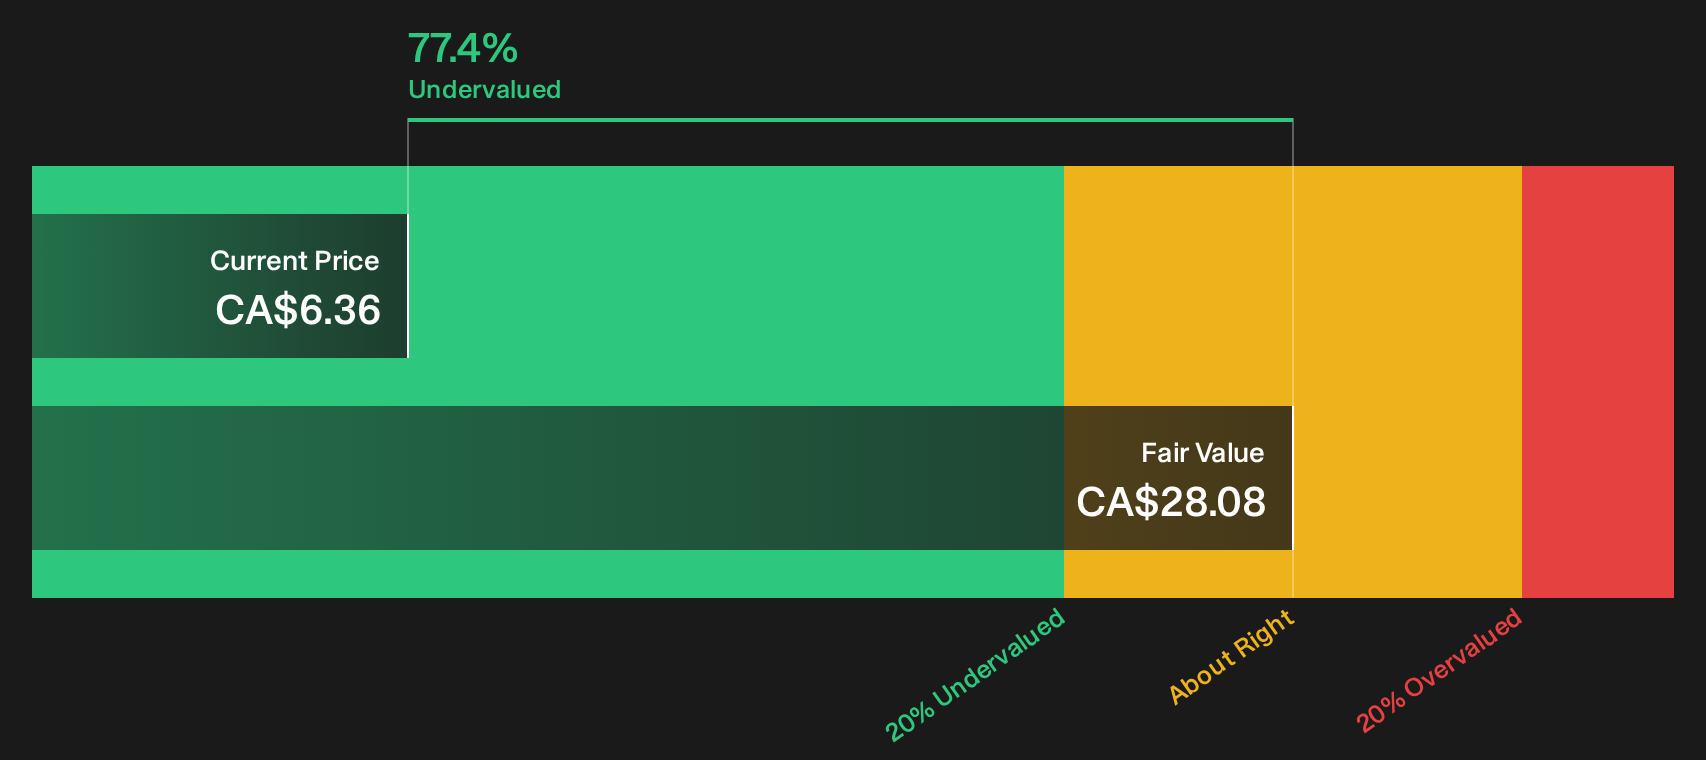
The SWS DCF model paints an even starker picture than the narrative fair value. With an estimated future cash flow value of CA$28.06 versus a share price of CA$6.36, it flags USA as heavily undervalued and raises a simple question: Are the cash flow assumptions too generous, or is the market too cautious?
For a closer look at how that future cash flow estimate is built and what would need to change for the DCF to move, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on valuation, risk, and potential rewards around Americas Gold and Silver mean you need to see the detail for yourself and move quickly before the narrative shifts. To weigh both sides of the debate in one place, start with the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Americas Gold and Silver?
If you stop with Americas Gold and Silver, you miss the broader opportunity set. Use the screener to surface ideas tailored to what matters most to you.
- Target potential mispriced opportunities by scanning for 7 high quality undervalued stocks that pair compressed valuations with fundamentals the market may not fully reflect.
- Explore income-focused ideas by reviewing 1 dividend fortresses that seek to combine higher yields with more robust payout profiles.
- Focus on capital preservation by concentrating on 8 resilient stocks with low risk scores that score better on balance sheet strength and business risk metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com