


PagSeguro Digital has seen sharp swings in investor sentiment over the past few years, which puts fresh focus on whether the current price around its recent close of US$10.72 is properly supported by its earnings. After such a mixed share price journey, the key issue for you is what those profits really justify today.
- The stock has fallen 67.7% over the past 5 years, which puts the spotlight firmly on whether the earnings power of the business lines up with that long term share price record.
- PagSeguro Digital earns money by processing payments and offering financial services, so the sustainability of its fees and the cost of funding its operations may support or constrain how much value investors can reasonably tie to its current earnings base.
- The analysts covering PagSeguro Digital have run their own numbers. See what analysts think PagSeguro Digital's shares could be worth.
The stock's next move may depend on whether PagSeguro Digital's current market price is in step with what its earnings suggest the business is worth.
If you are weighing whether PagSeguro Digital's earnings justify its current valuation and want more context, a focused stock screen built around 27 high quality undervalued stocks can be a helpful next step.
Is PagSeguro Digital Still Cheap on Earnings?
The P/E ratio fits PagSeguro Digital well because earnings remain the core anchor for how investors assess its payment and financial services platform.
At around 6.8x earnings, PagSeguro Digital trades at a substantial discount to the broader Diversified Financial group, where the average P/E is about 17.0x, and also sits well below the peer group average of roughly 31.3x. A tailored fair P/E multiple that factors in the business profile, profitability and risk points to a higher figure than where the stock trades today, which implies the current P/E screens as undervalued on this framework.
For you as a shareholder or potential buyer, that gap between PagSeguro Digital's current P/E and the level suggested by its fundamentals raises the question of whether the market is placing a heavy discount on its earnings power or underestimating the stability of those profits. Comparing that gap with your own view of the business quality and earnings sustainability is key before treating the low P/E as a clear positive signal. Explore the numbers behind PagSeguro Digital's P/E valuation.
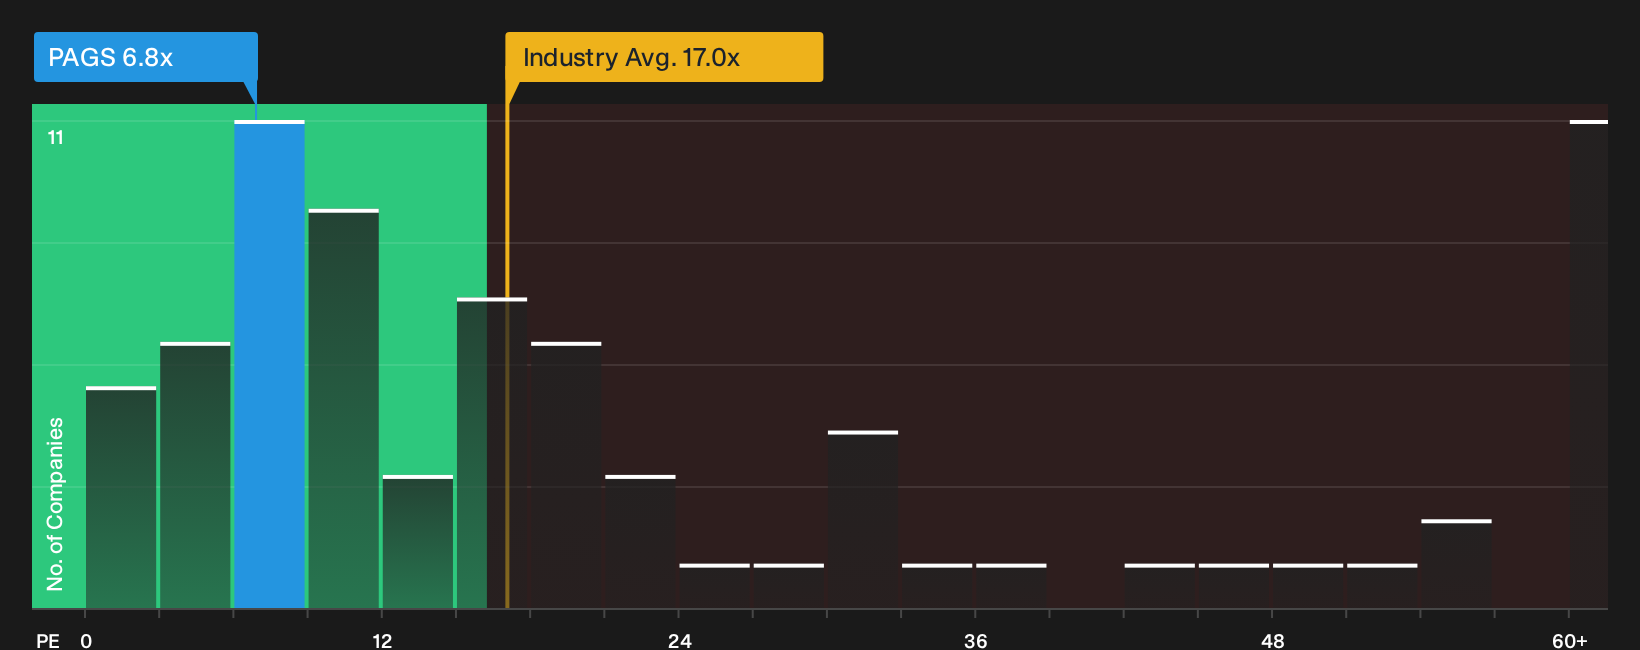
The PagSeguro Digital Narrative: What Would Justify Today's Price?
PagSeguro Digital's valuation puzzle only really makes sense once you spell out the future paths that could plausibly support a higher or lower P/E, based on growth, margins and earnings resilience. Narratives on Simply Wall St's Community page do exactly that by tying each potential storyline about PagSeguro Digital's catalysts and risks to a specific fair value, so you can observe over time which version of events is actually unfolding.
PagSeguro Digital attracts two very different readings, with one group leaning into the banking optionality and another stressing competition and margin strain.
Bull case: 44% undervalued
"The single biggest lever is the credit portfolio, it sits at roughly R$5 billion today and management targets R$25 billion by 2029..."
Discover why this Narrative puts PagSeguro Digital at 44% undervalued.
Bear case: 39% overvalued
"Intensifying digital competition from global fintechs and big tech platforms such as Apple, Google, and MercadoLibre is expected to erode PagSeguro's ability to acquire and retain customers..."
Explore why this Narrative puts PagSeguro Digital at 39% overvalued.
One more angle on PagSeguro Digital that deserves your attention
Before treating PagSeguro Digital purely as a low P/E story, it is worth knowing that our broader checks have flagged specific concerns that could change how you interpret everything you have just read. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com