


Epiroc (OM:EPI A) drew fresh investor attention after securing a sizeable underground mining equipment order from Sibanye-Stillwater for the mechanization of its Siphumelele platinum shaft in Rustenburg, South Africa.
Set against this contract win, Epiroc’s recent share price performance has been firm, with a 90 day share price return of 6.41% and a year to date share price return of 28.02% at a SEK269.1 closing price. The 5 year total shareholder return of 54.57% points to momentum that has been sustained over a longer period.
Scan other contract backed equipment suppliers benefiting from mining investment through the curated 90 robotics and automation stocks.
Epiroc’s contract win and strong recent share performance raise a sharper question for investors: Is the current SEK269.1 price already pricing in the good news, or is the 9.1% estimated discount leaving meaningful upside ahead?
Most Popular Narrative: 4% Undervalued
Epiroc’s most followed valuation storyline pegs fair value at SEK280.3, only modestly above the SEK269.1 close, which leaves a narrow margin for error and puts the focus squarely on how the business might earn into that gap.
Continued investment in automation and digital features (automation for core drilling rigs, expansion in BEV technology, and growing connected fleet of ~15,000 machines) aligns with the mining sector's shift toward digitalization and productivity, likely increasing long-term recurring revenues from software, data, and aftermarket services, supporting future margin expansion.
See why 10 investors see Epiroc as 4% undervalued.
The narrative applies a 6.62% discount rate and assumes revenue growth of about 10.2% a year, profit margins stepping up from 14.2% to 16.6%, and earnings reaching SEK13.8b by around 2029. On those forecasts, Epiroc would trade on a P/E of 29.8x in 2029, which is higher than the current 24.5x P/E for the Swedish Machinery industry that the narrative references, and it anchors today’s SEK280.3 fair value estimate.
Against the SEK269.1 market price, that framework implies roughly a 4% undervaluation, which is a relatively tight gap that leaves little room if mining activity, aftermarket penetration, or margin improvement were to fall short of the narrative’s path.
Result: Fair Value of SEK280.3 (UNDERVALUED)
Still, the whole Epiroc story can change quickly if mining customers pull back on equipment spending, or if production shifts and currency swings keep pressuring EBIT and cash generation.
Find out about the key risks to this Epiroc narrative.
Another View: Epiroc Looks Expensive On Earnings
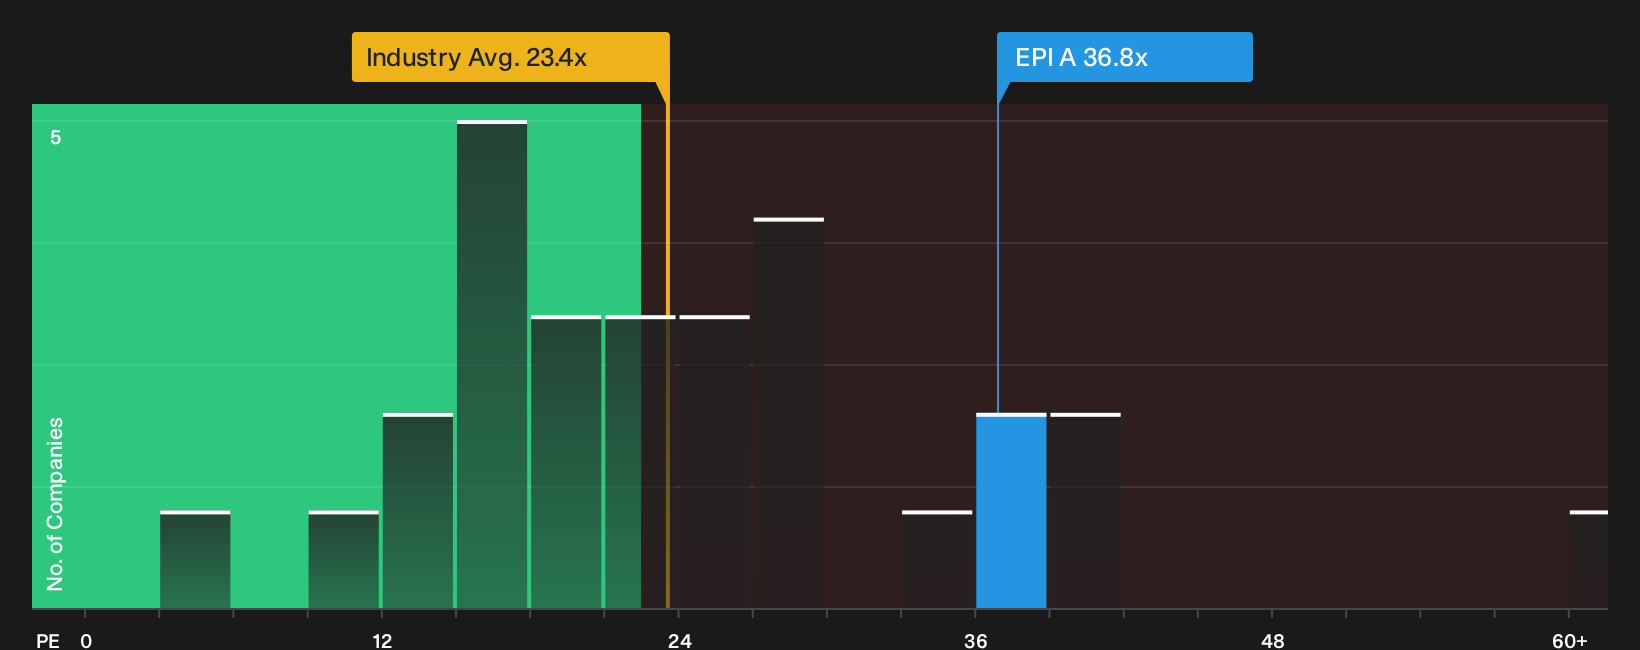
Epiroc screens as undervalued on cash flows and fair value estimates, yet the market is already paying a rich P/E of 36.8x. That is well above the Swedish Machinery industry at 23.4x, the peer average at 27.1x, and even the 32.1x fair ratio that the data suggests the market could move toward.
This gap points to valuation risk as much as opportunity, because any disappointment against earnings expectations could see the multiple drift closer to those lower benchmarks. The key question is whether you are comfortable paying a premium today for a business already priced ahead of its own fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mix of contract wins, fair value estimates and premium earnings multiples gives plenty to weigh up, so do not just take the headline view at face value. Spend a few minutes with the fuller breakdown of rewards that investors are focusing on through the 2 key rewards.
Looking for more ideas beyond Epiroc?
If you stop with Epiroc, you miss a wider set of opportunities that could fit your goals just as well or even better.
- Target potential mispricings by reviewing the 185 high quality undervalued stocks that combine solid fundamentals with room for a sentiment shift.
- Lock in potential income streams by scanning the 164 dividend fortresses that pair higher yields with business models focused on steady payouts.
- Dial down portfolio stress by checking the 227 resilient stocks with low risk scores that score well on financial strength and earnings stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com