


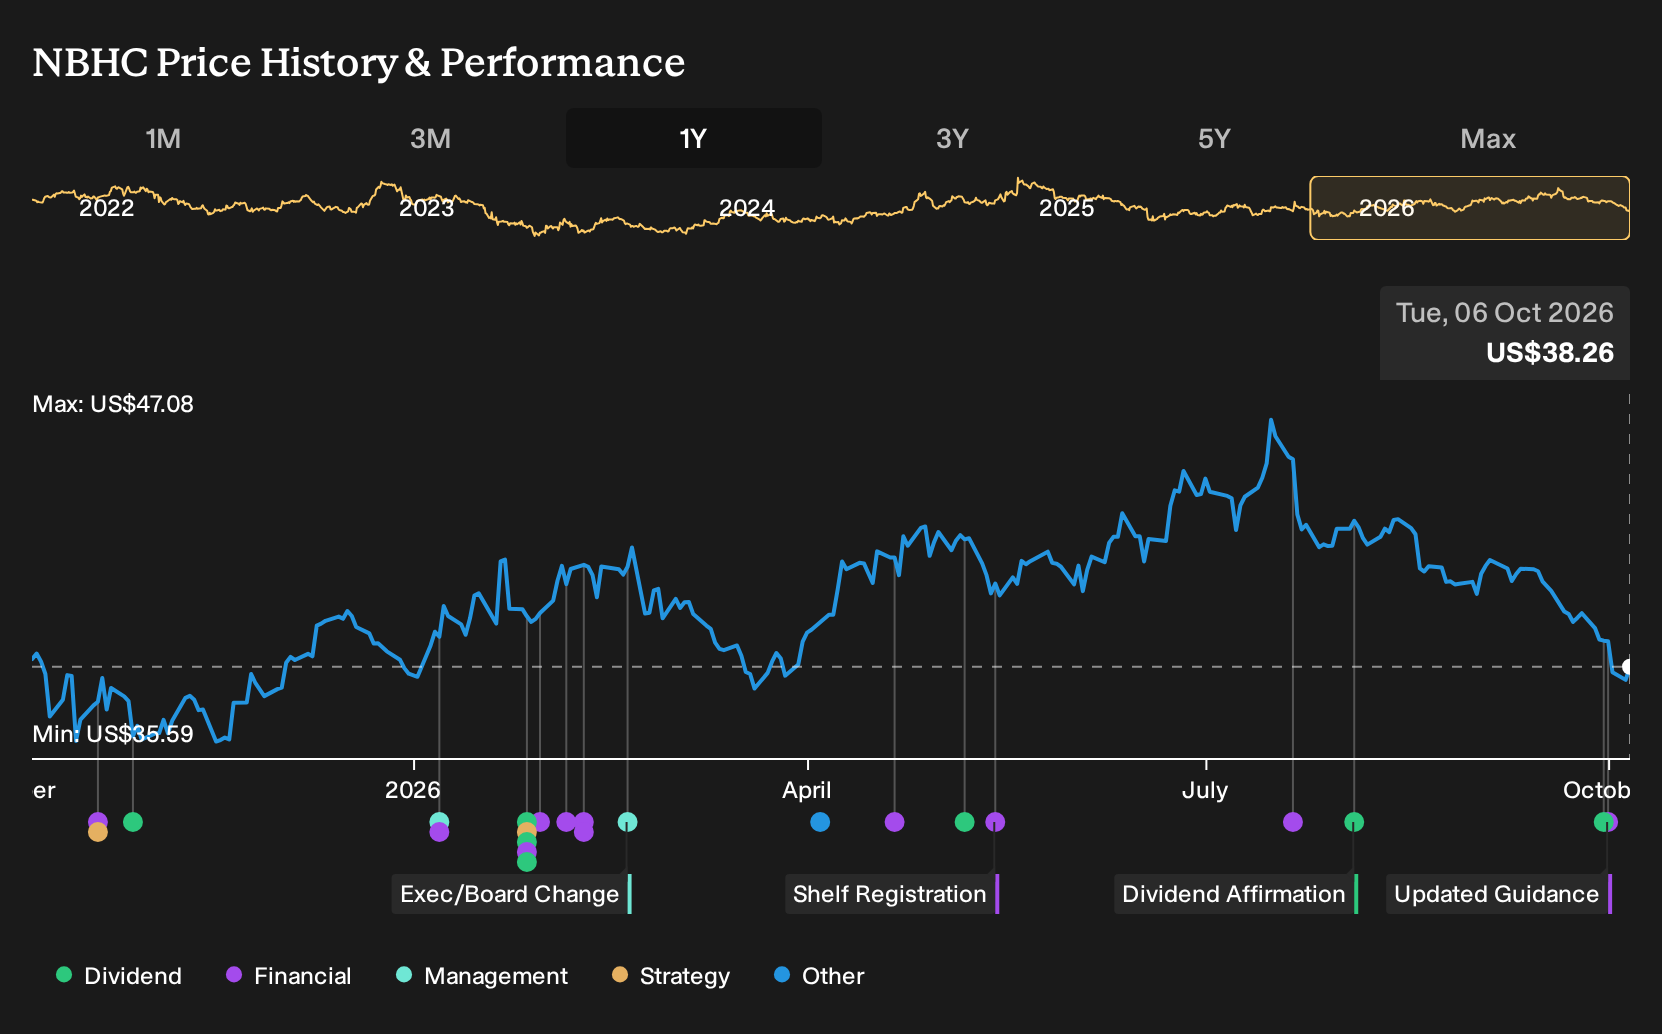
- National Bank Holdings Corporation reported in early October 2026 that earnings guidance for the three and nine months ended September 30, 2026 would be reduced by about $32.0 million to $34.0 million after tax, or $0.72 to $0.76 per diluted share. The company also separately increased its remaining share repurchase authorization to $40.1 million.
- The combination of lower expected profitability and a larger buyback pool highlights management balancing current earnings pressure against a decision to return more capital to shareholders. This raises questions about how sustainable the underlying earnings power of National Bank Holdings looks over the medium term.
- This development reshapes how investors might view National Bank Holdings' investment narrative in light of the newly signaled reduction in after tax earnings guidance.
What Is National Bank Holdings' Investment Narrative?
To own National Bank Holdings, you need to be comfortable with a straightforward regional banking story. The bank leans on traditional lending and deposit gathering across its Western and Midwest footprint, plus fee income from treasury services. The recent guidance cut of about $32.0 million to $34.0 million after tax points to near term earnings pressure, which matters if you care about capital generation to support loan growth, dividends and buybacks.
The higher remaining buyback authorization of $40.1 million signals that management still sees value in the stock and has room on the balance sheet to deploy capital. In the short term, the key swing factors remain credit quality, funding costs and loan demand. The combination of reduced earnings expectations and a larger repurchase pool will likely shape how investors judge whether those risks are being priced correctly.
That said, sitting behind this capital return story is one specific pressure point that could reshape how you think about NBHC if ...
There's only one way to know the right time to buy, sell or hold National Bank Holdings. Head to Simply Wall St's company report for the latest analysis of National Bank Holdings's Fair Value.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster between US$46 and about US$63.95 per share, which already shows how far opinions on National Bank Holdings can stretch. Those assessments were set before the earnings guidance cut and larger buyback, so treat them as a starting point and compare several alternative viewpoints yourself.
Explore another National Bank Holdings fair value estimate, including one that suggests it could be worth just $46.00!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your National Bank Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for National Bank Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Bank Holdings' overall financial health at a glance.
Looking for more investment ideas beyond National Bank Holdings?
If this National Bank Holdings update has you reassessing where you want risk, it can help to compare it with other opportunities that fit clear financial profiles. The Simply Wall St Screener lets you filter for businesses that align with the kind of balance sheet strength, income potential, or resilience you want to focus on next.
- If you care most about resilient businesses with strong finances, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without stretching their resources.
- For investors who want potential upside while still insisting on quality, scan through a 19 high quality undiscovered gems that combine healthy fundamentals with relatively low attention.
- If lower volatility and capital preservation sit higher on your priority list right now, narrow the field using a 31 resilient stocks with low risk scores that screens for stocks with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com