


As the Australian market gears up for the week, investors are cautiously optimistic despite mixed signals from global indices and concerns over bond yields. Penny stocks, often representing smaller or newer companies, continue to capture attention as they offer unique growth opportunities at accessible price points. In this article, we explore three penny stocks that stand out due to their solid financial foundations and potential for long-term growth.
Let's uncover some gems from our specialized screener.
Cleo Diagnostics (ASX:COV)
Simply Wall St Financial Health Rating: ★★★★★☆
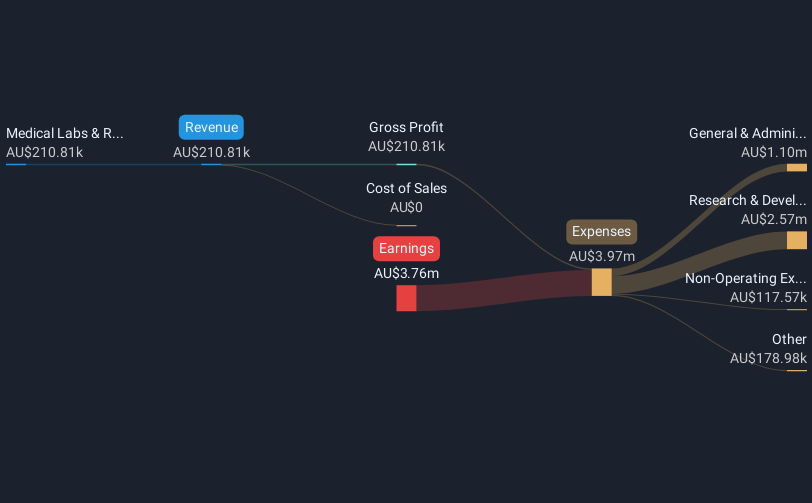
Overview: Cleo Diagnostics Ltd is a biotechnology company focused on developing and patenting a blood test for ovarian cancer detection in Australia, with a market cap of A$47.99 million.
Operations: The company generates revenue from its Medical Labs & Research segment, amounting to A$1.72 million.
Market Cap: A$47.99M
Cleo Diagnostics is a biotechnology company focused on ovarian cancer detection, currently pre-revenue with A$1.72 million from its Medical Labs & Research segment. Despite being unprofitable with a net loss of A$5.94 million for the year ended June 2026, it benefits from an experienced management team and board, each averaging four years in tenure. The company has no long-term liabilities and remains debt-free, though it faces less than one year of cash runway if historical cash flow reduction continues. Shareholders have not experienced significant dilution over the past year, maintaining stability in ownership structure.
- Click to explore a detailed breakdown of our findings in Cleo Diagnostics' financial health report.
- Explore historical data to track Cleo Diagnostics' performance over time in our past results report.
Finbar Group (ASX:FRI)
Simply Wall St Financial Health Rating: ★★★★★★
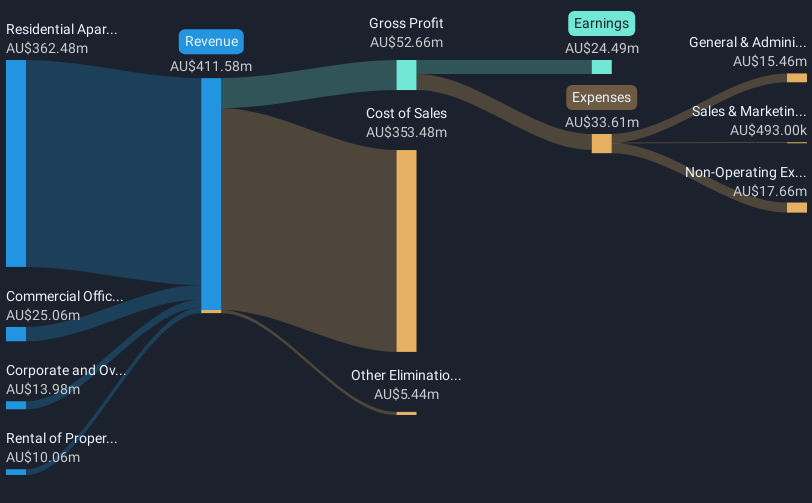
Overview: Finbar Group Limited, along with its subsidiaries, operates in the property development and investment sector in Australia with a market capitalization of A$194.57 million.
Operations: The company's revenue is primarily derived from Residential Apartment Development at A$175.72 million, followed by Commercial Office/Retail Development generating A$21.83 million, and Property Rental contributing A$6.76 million.
Market Cap: A$194.57M
Finbar Group Limited, with a market cap of A$194.57 million, reported a net income increase to A$20.26 million for the year ended June 2026, despite a revenue decline from A$284.47 million to A$204.32 million. The company's earnings growth of 40.9% outpaced the real estate industry average and its own five-year average of 20.1%. However, its dividend yield of 8.39% is not well covered by free cash flow, indicating potential sustainability concerns. Finbar's debt management is robust with more cash than total debt and operating cash flow covering 64.7% of its debt obligations, while maintaining stable shareholder equity without significant dilution over the past year.
- Jump into the full analysis health report here for a deeper understanding of Finbar Group.
- Examine Finbar Group's past performance report to understand how it has performed in prior years.
HMC Capital (ASX:HMC)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: HMC Capital Limited, along with its subsidiaries, owns and manages real estate-focused funds in Australia and has a market capitalization of approximately A$1.24 billion.
Operations: The company's revenue is derived from several segments, including Real Estate at A$88.6 million, Digital at A$51.2 million, Private Credit generating A$40.6 million, Corporate contributing A$0.2 million, and Private Equity at A$1.3 million.
Market Cap: A$1.24B
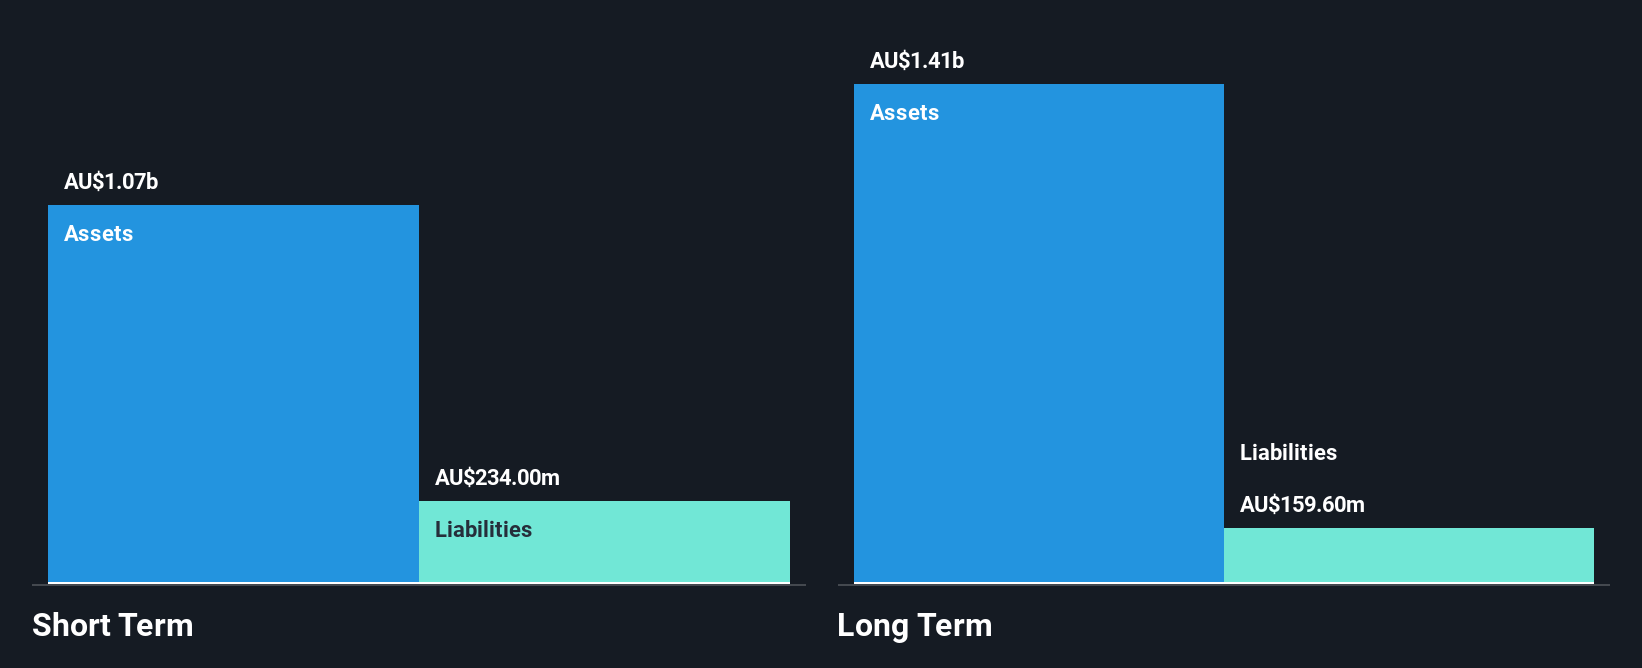
HMC Capital's market capitalization of A$1.24 billion positions it beyond typical penny stock territory, yet its recent financial performance raises concerns. The company reported a net loss of A$49.1 million for the fiscal year ending June 2026, with sales declining to A$181.9 million from the previous year's A$227.8 million. Despite stable weekly volatility and satisfactory net debt to equity ratio (6.8%), HMC faces challenges with negative operating cash flow and uncovered long-term liabilities by short-term assets (A$264.5M vs A$340.1M). Dividend growth is planned at 15 cents per share for fiscal year 2027, supported by recurring earnings growth but not well covered by current earnings or free cash flows, raising sustainability questions amidst a management team averaging only 1.8 years in tenure.
- Take a closer look at HMC Capital's potential here in our financial health report.
- Evaluate HMC Capital's prospects by accessing our earnings growth report.
Next Steps
- Get an in-depth perspective on all 393 ASX Penny Stocks by using our screener here.
- Ready To Venture Into Other Investment Styles? Outshine the giants: these 19 early-stage AI stocks could fund your retirement.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com