


- DNB Bank has restructured its Technology & Services unit, investing heavily in AI and digital tools and cutting about 400 FTEs. Related costs are booked in Q4 2026 and full cost effects are expected from Q2 2027.
- The lender is shifting routine work in areas like KYC, customer data handling and coding to AI agents. This reshapes its required skills mix and internal cost base.
- We will look at how DNB Bank's investment narrative is affected by AI driven restructuring and the 400 role reduction in Technology.
Scan how DNB Bank’s AI driven restructuring compares with other financial institutions by reviewing our curated 227 resilient stocks with low risk scores aimed at pairing resilient balance sheets with measured risk profiles.
DNB Bank Investment Narrative Recap
DNB Bank’s long term story still rests on a large Norwegian franchise, high asset quality and measured growth in both lending and fee income. For a shareholder, the key belief is that this franchise can absorb heavier tech spend while keeping returns acceptable as revenue is forecast to rise around 3.4% a year and earnings growth remains modest.
The AI driven restructuring is aimed squarely at the cost line, with 400 FTEs leaving Technology & Services and related charges booked in Q4 2026. That is material for near term expenses, although the biggest near term risks still look tied to margin pressure, funding mix quality and competition from digital first rivals.
The appointment of Mitra Hagen Negård as Head of Investor Relations is the clearest complementary development to this AI and restructuring update. Fresh IR leadership with long capital markets experience can sharpen how DNB Bank explains cost actions, capital priorities and digital spending to investors who already see only limited upside to consensus price targets.
Communication around catalysts now matters more. Shareholders will be watching how clearly the bank links Q4 2026 restructuring costs to later run rate savings, and how it frames credit quality, funding and fee trends. Effective IR execution can reduce uncertainty around earnings forecasts, especially when revenue growth expectations are moderate and return on equity is described as low.
DNB Bank's current narrative points to NOK 97.4b in revenue and NOK 40.1b in earnings by 2029, based on 3.6% yearly revenue growth and an earnings decline of NOK 0.1b from NOK 40.2b today.
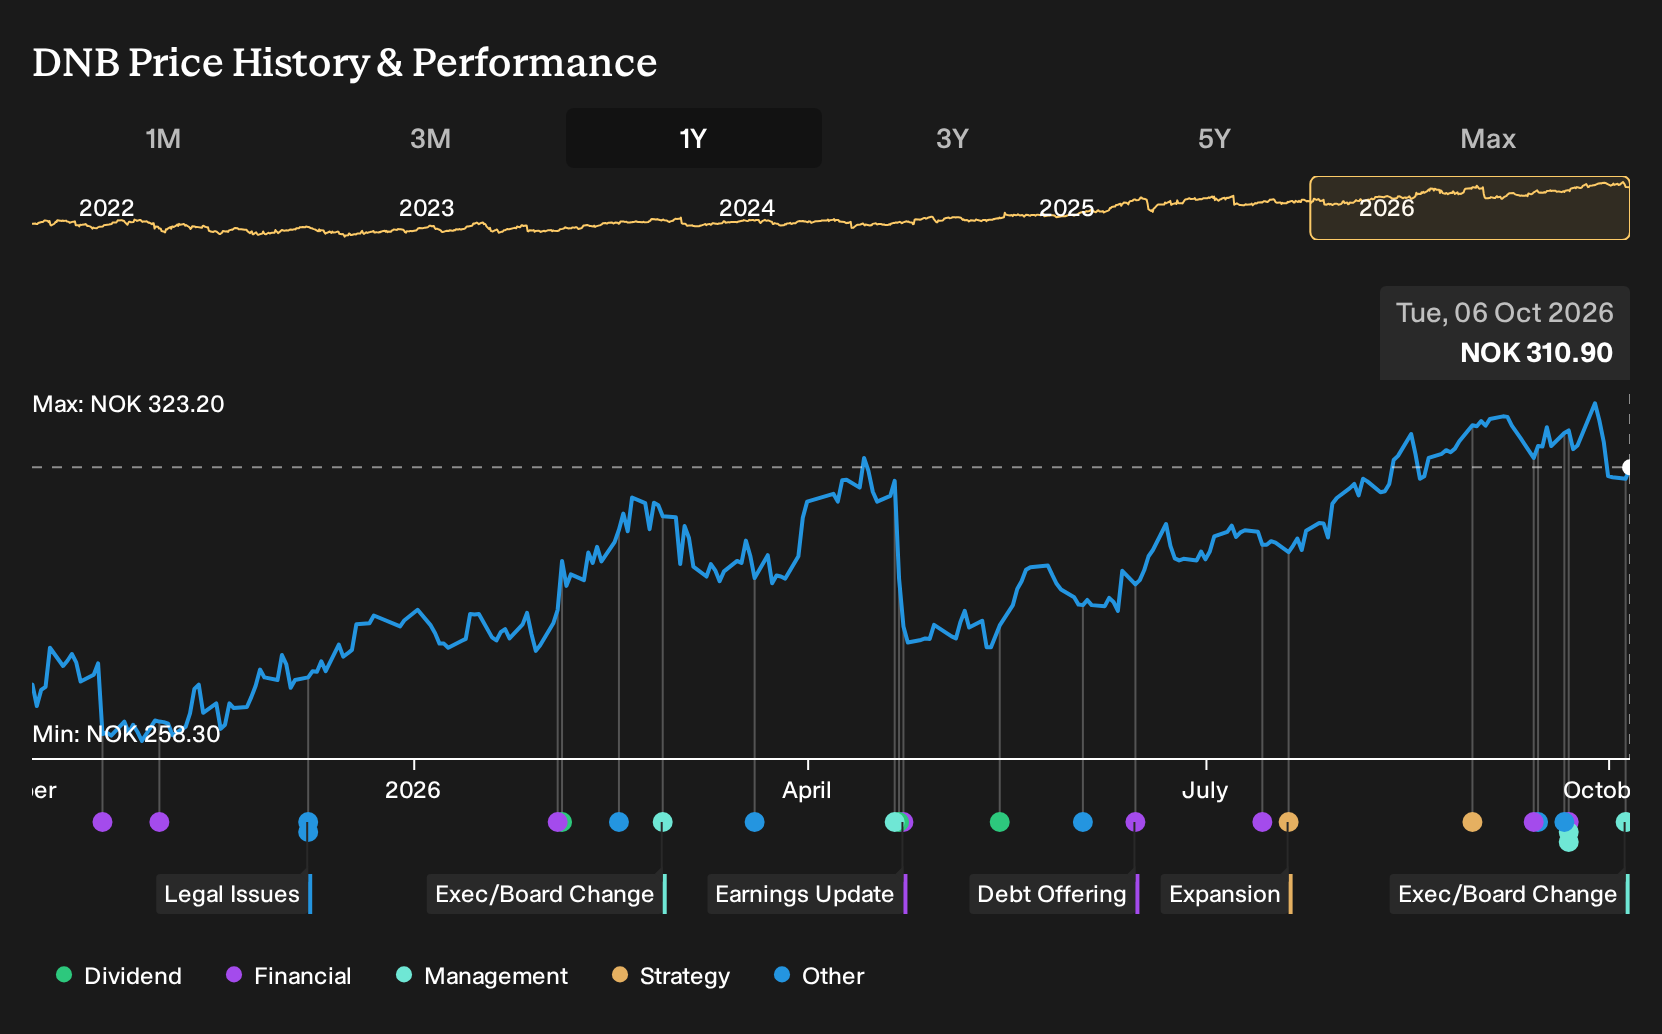
Uncover why the DNB Bank's fair value is essentially in line with its current price.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly NOK 317 at the low end to about NOK 507 at the high end, so individual views on DNB Bank differ sharply. Set that against rising use of AI, job cuts and tougher digital competition, and you are seeing genuine disagreement. Explore those alternative viewpoints before forming your own stance.
Explore 2 other DNB Bank fair value estimates, including one that suggests there may be as much as 63% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your DNB Bank research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for DNB Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate DNB Bank's overall financial health at a glance.
Looking for more DNB Bank investment ideas?
If you want to cross check DNB Bank against other opportunities, use the Simply Wall St Screener to source a few contrasting candidates and pressure test your thesis.
- For investors who care most about capital strength and muted downside risk, start with a curated list of solid balance sheet and fundamentals (206 results) that can sit alongside DNB Bank in a more resilient core portfolio.
- If your priority is finding stocks that trade below their assessed worth with solid fundamentals, compare DNB Bank with a carefully filtered 185 high quality undervalued stocks that might warrant deeper research.
- Income focused readers who want dependable payouts can balance DNB Bank with a hand picked 164 dividend fortresses that screens for higher yields backed by sturdier financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com